Best Rates on Personal Loans for High Income Individuals
Last updated: 2026-10-16
Securing immediate liquidity can feel like hitting a brick wall for those at the top of the income ladder. Even if your tax filings scream success, finding a lender capable of grasping your intricate cash flows or tax arrangements is often an uphill battle.
It is rarely just a matter of obtaining funds. Instead, the real challenge lies in locating a financial ally that values your time and recognizes your level of fiscal expertise.
For elite specialists—think surgeons, high-level executives, or niche engineers—the standard automated lending software often misses the mark entirely. These rigid algorithms frequently overlook the subtle intricacies that define your true economic status.
Your wealth might be tied up in stock options, seasonal bonuses, or deferred compensation that traditional pay stubs simply cannot communicate effectively. Consequently, you might face discouraging rejections or unfavorable rates, even when your net worth is undeniably stellar.
Selecting a provider involves more than just scanning interest rates for the lowest number. You must weigh the velocity of funding against the versatility of your repayment schedule and the intuitiveness of the online platform.
When you are managing heavy assets, bureaucratic friction can become a major obstacle. If you are currently finalizing a private equity play or a real estate acquisition, you simply cannot afford to waste days uploading documents to an antiquated bank.
Our selection emphasizes lenders that harmonize rapid execution with the unique requirements of affluent borrowers. We have prioritized companies that deliver a digital-first approach and provide swift access to capital.
Our goal is to showcase institutions that keep pace with your ambitions. We want to highlight lenders that won’t trip you up when you need to seize a fleeting opportunity.
- Discover
- Avant
- JetzLoan
- OneMain Financial
- LendingPoint
- Upgrade
Our Methodology for Assessing Top-Tier Lenders
Our research team centered their investigation on the distinct needs of affluent clients. We prioritized finding institutions capable of issuing substantial capital without demanding physical assets as collateral. For many executives, the ability to leverage future income remains vital for maintaining financial flexibility.
We specifically hunted for companies that implement “soft pulls” during the preliminary screening process. This method allows you to test different scenarios and interest rates without damaging your credit profile. It is essentially a risk-free way to see what you qualify for before committing to an application.
Time is of the essence when a golden opportunity arises. Whether you are eyeing a sudden property deal or a tactical market move, you cannot afford to wait weeks for a wire transfer. We placed a premium on institutions that can deliver funds in as little as sixty minutes or within a twenty-four-hour window.
Transparency was another non-negotiable standard in our selection process. We steered clear of lenders that bury “origination fees” in the fine print of massive documents. For a sophisticated borrower, clarity is just as important as the interest rate itself. If the math isn’t upfront, we crossed them off our list immediately.
The scale of the credit offered played a decisive role in our rankings. Small-scale loans under $5,000 are often a drop in the bucket for those managing significant wealth. They simply do not address the complexities of debt restructuring or large-scale lifestyle changes that high-net-worth individuals face.
Consequently, we focused on providers that offer impressive ceilings on their lending products. We sought out limits that typically start at $30,000 or much higher to ensure the liquidity actually moves the needle. Our goal was to find tools that facilitate true strategic financial planning rather than just minor expenses.
Comparing Leading Financing Options
Deciding where to park your debt is a lot like choosing a luxury vehicle; you want speed, reliability, and a smooth ride. For those moving large sums of cash, the fine print matters more than the flashy advertisements. Every lender brings a different flavor of service to the table, ranging from lightning-fast approvals to high-limit availability.
If you are in a pinch, some companies move like a lightning strike, while others take a more leisurely approach. It is vital to look past the surface-level promises and dig into how your credit score might react to the inquiry. Some banks are quite polite, allowing you to peek at rates without leaving a permanent scar on your report.
We have gathered the essential data below to help you weigh your options side-by-side. Whether you need a small boost or a significant injection of capital, this breakdown clarifies who offers what. Take a moment to scan the specifics before you dive into the deep end of the lending market.
| Company | Upper Limit | Time to Fund | APR & Interest Details | Credit Score Effect |
|---|---|---|---|---|
| Discover | $40,000 | By the next working day | 6.99% – 24.99% | Pre-approvals won’t affect score |
| Avant | Check website | Check website | Check website | Check website |
| JetzLoan | $50,000 | Minimum 24-hour turnaround | Check website | No hard credit pull required |
| OneMain Financial | $30,000 | Could take only 1 hour | From 11.99% APR | Checking rates has no impact |
| LendingPoint | $36,500 | Check website | Check website | No impact for checking |
| Upgrade | $50,000 | Rapid disbursement | Check website | Checking won’t change score |
Top-Tier Financing Options for High-Income Professionals
Discover
For those seeking the rock-solid foundation of an institution backed by the full faith and credit of the U.S. Government, Discover stands out. Their personal loan offerings are refreshingly uncomplicated, spanning from $2,500 to a maximum of $40,000. It is a dependable harbor for anyone craving the stability that only a long-standing, established entity can provide.
In a world where fintech startups can vanish or pivot their entire business model overnight, this lender offers a sense of permanence. You won’t have to worry about the rug being pulled out from under your feet. It is a sanctuary for the cautious investor or professional who values institutional security above all else.
The digital experience is as smooth as silk, allowing you to run a quick pre-approval check without any guesswork. This feature is a lifesaver for high-income earners who are protective of their credit scores. You can explore your potential terms without suffering a single point of damage to your rating.
Navigating the platform is a breeze because the interface is stripped of all the clutter. For the busy professional whose time is worth a premium, this streamlined design is a true luxury. You won’t find yourself lost in a labyrinth of unnecessary sub-menus or confusing digital dead-ends.
Pros:
- Capital can arrive as soon as the next business day.
- Flexible repayment terms are available with no hidden fees.
- Checking your pre-approval status won’t hurt your credit score.
Cons:
- The ceiling for loan amounts is set at $40,000.
Avant
Avant acts as a financial partner for those in the midst of a significant upward trajectory. They provide a diverse toolkit of products, from credit cards to loans specifically intended for home improvements or debt consolidation. It is a highly versatile option for anyone whose financial landscape is constantly shifting.
Life is rarely a straight line, and your financial needs will reflect that reality. For instance, your debt-to-income ratio might look quite different as you climb the corporate ladder from a junior associate to a senior partner. Avant offers the flexibility to pivot alongside your career evolution.
The company prides itself on human-centric support and adaptable choices, which helps demystify the often murky waters of personal debt. Whether you need a quick patch for a sudden expense or a grand strategy for long-term management, their tools are designed to simplify your life.
They don’t believe in a “one size fits all” philosophy. Instead, they provide a custom menu of options that match your specific financial velocity. It is less about rigid structures and more about finding a rhythm that works for your unique lifestyle and goals.
Pros:
- Customizable loan options tailored to diverse requirements.
- Intuitive digital management tools for your finances.
- Offers various different strategies for managing debt.
Cons:
- Specific details regarding loan limits and terms aren’t explicitly shared.
JetzLoan
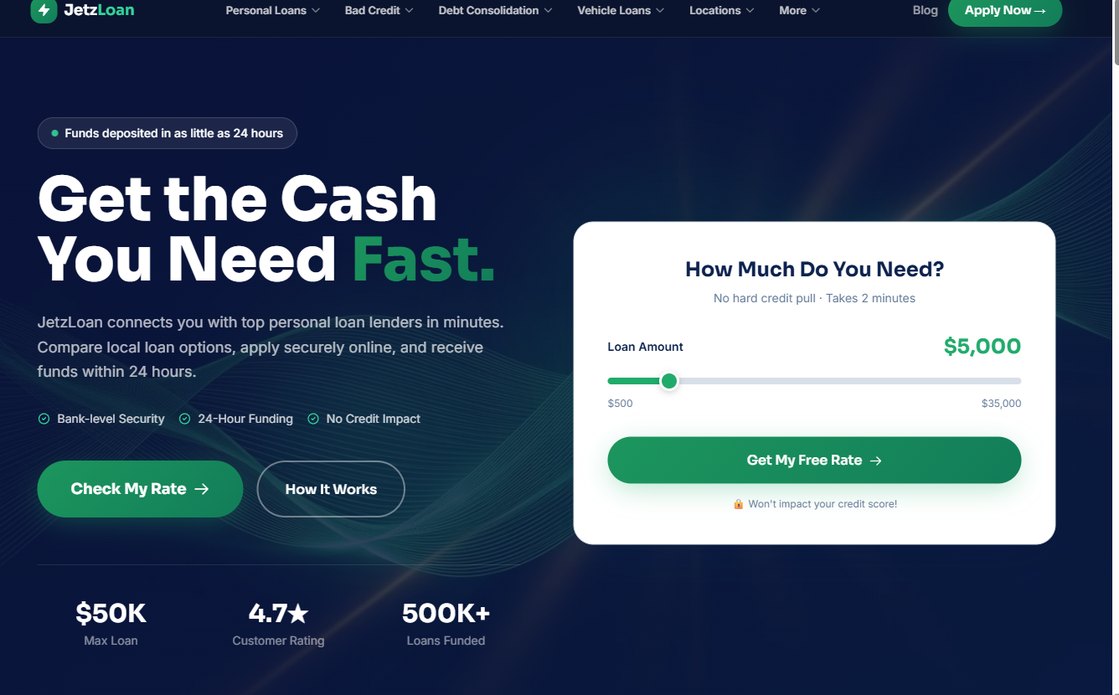
When time is of the essence and you need capital yesterday, JetzLoan is the high-speed engine you need. They act as a bridge, connecting you to premier lenders in just a few minutes. In some cases, they can even facilitate the movement of funds within a twenty-four-hour window.
This is the ideal solution for those who find the traditional banking system’s pace to be glacial. If a sudden investment opportunity lands on your desk—perhaps a high-stakes real estate auction or a lucrative private placement—the speed found here is a massive competitive edge.
The application process is incredibly lean, requiring less than two minutes to navigate a simple form. With loan ceilings reaching up to $50,000, they handle significant requests without the headache of a hard credit inquiry during the initial rate discovery phase.
By utilizing this marketplace model, you gain access to a wide array of options without the tedious task of applying to various banks one by one. It is a sophisticated way to avoid excessive administrative overhead while keeping your financial momentum high.
Pros:
- Incredibly rapid funding, potentially arriving in 24 hours.
- Initial rate checks do not require a hard credit pull.
- A substantial maximum loan cap of $50,000.
Cons:
- Functions as a middleman/connector rather than being a direct lender.
OneMain Financial
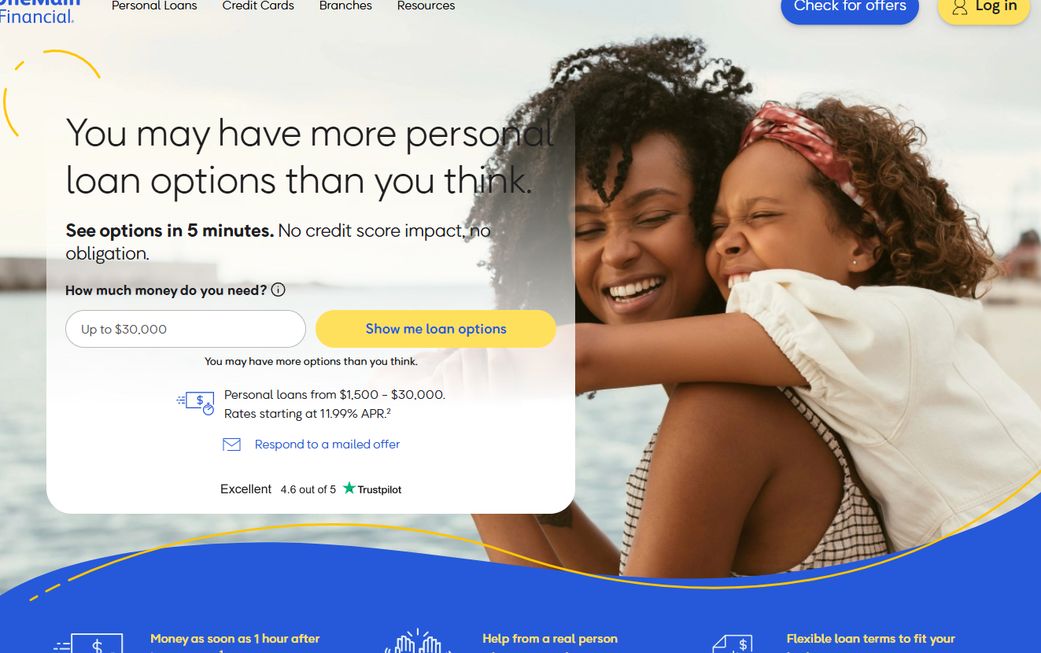
OneMain Financial serves as a powerhouse for those who want the best of both worlds: digital efficiency and human connection. Their personal loans range from $1,500 up to $30,000, with interest rates beginning at 11.99% APR. It is a robust option for those who require immediate liquidity.
The ability to access funds just one hour after signing your paperwork is a major advantage. In the unsecured loan market, such velocity is a rarity. This makes them a premier choice when an unexpected financial emergency requires an instant solution.
If you prefer looking a person in the eye while discussing money, you can visit one of their 1,300 physical branches. This hybrid approach is perfect for high earners who want the convenience of an app but still crave the security of face-to-face interaction.
Having a brick-and-mortar location can offer immense peace of mind. This is particularly useful if you need to navigate complex repayment schedules or provide specific documentation that a purely digital lender might find difficult to process.
Pros:
- Lightning-fast funding, sometimes within a single hour.
- A massive network of branches for in-person assistance.
- Flexible repayment windows ranging from 24 to 60 months.
Cons:
- Unsecured loan interest rates may exceed those of secured options.
LendingPoint
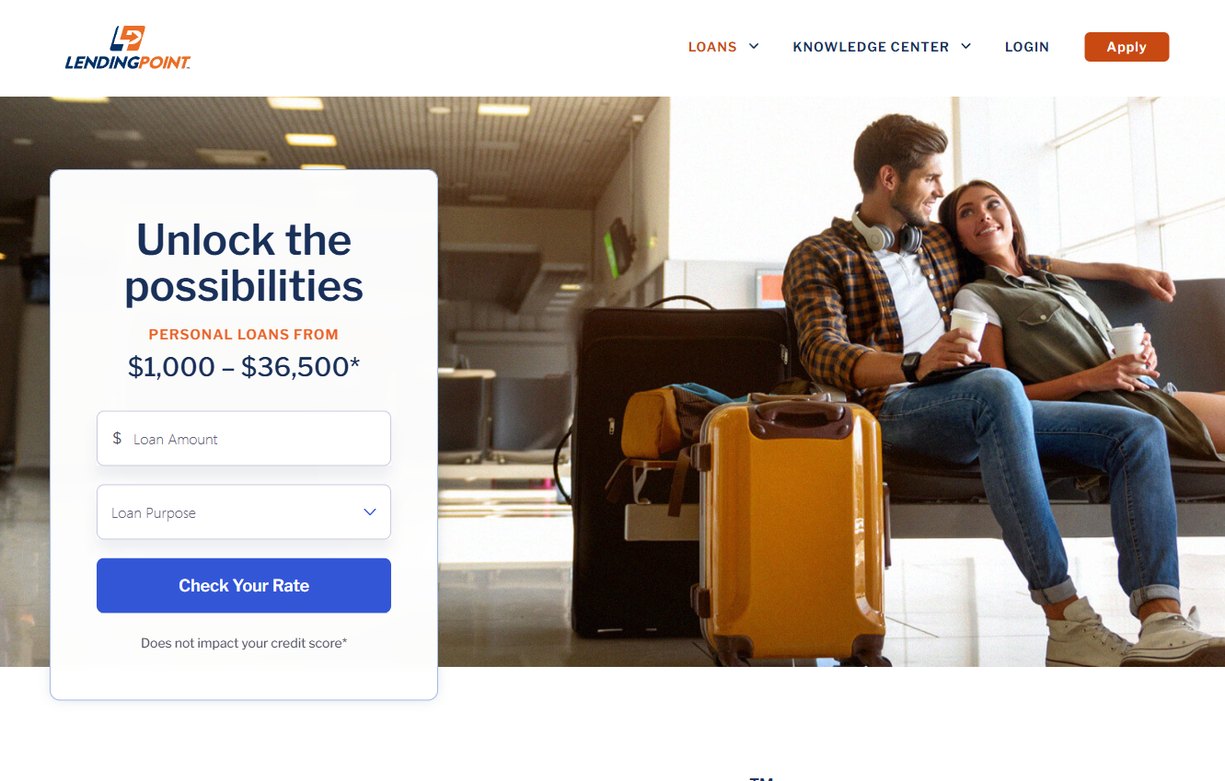
LendingPoint positions itself as a versatile solution for various life milestones, whether you are planning a wedding or managing medical costs. Their loans fall between $1,000 and $36,500, filling that middle ground between small micro-loans and massive mortgages. They provide a solid stepping stone for significant expenses.
Their underwriting process is notably more sophisticated than your average consumer lender. Rather than just looking at a single number, they tend to evaluate your entire financial health. It is a more nuanced way of assessing a borrower’s true capacity.
The platform is built for ease of use, allowing you to shop around for rates without any impact on your credit score. This “window shopping” capability is vital for high-earning professionals who are managing multiple credit lines and demand precision regarding their debt costs.
By letting you compare options without penalty, they empower you to make informed decisions. You can weigh your various choices with surgical precision, ensuring that every dollar borrowed is working exactly as intended for your financial strategy.
Pros:
- Supports a broad spectrum of loan purposes.
- Compare rates without any damage to your credit score.
- Generous loan limits reaching up to $36,500.
Cons:
- The maximum amounts are slightly lower than some specialized lenders.
Upgrade
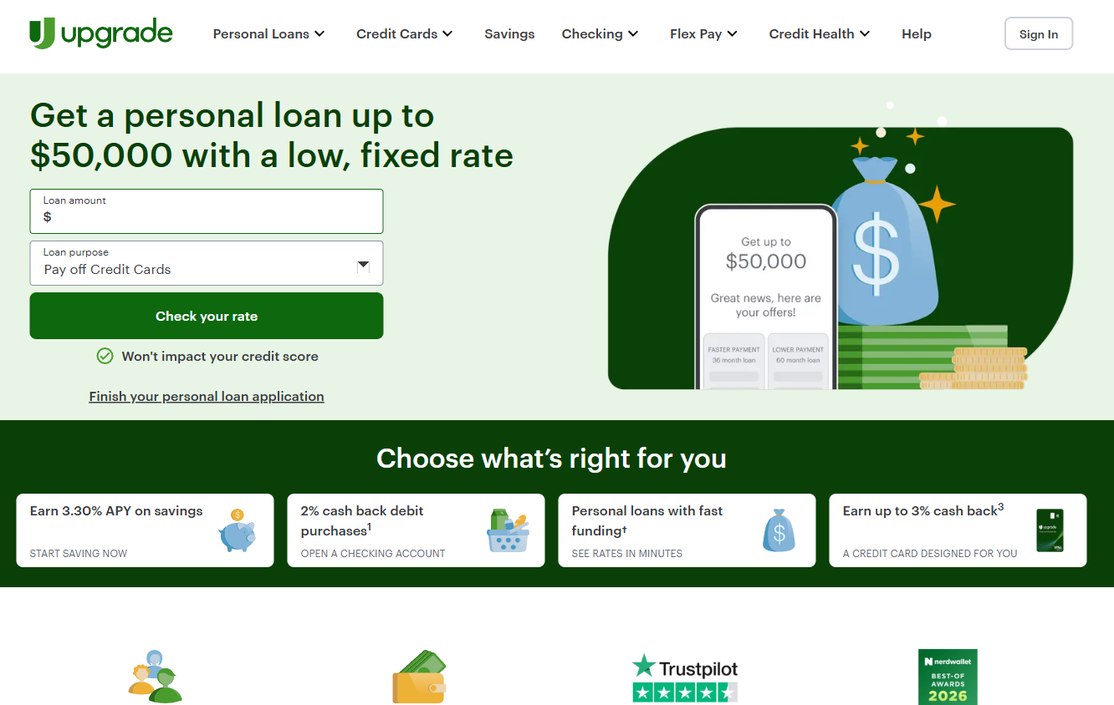
Upgrade serves as a comprehensive financial hub for the modern consumer, providing personal loans with limits reaching $50,000. They prioritize speed and high-tech integration, often presenting rates in a matter of minutes. It is a streamlined choice for those who value efficiency above all.
Their ecosystem is remarkably robust, offering features like cash back on transactions and high APY on savings accounts. It is a true “one-stop-shop” that appeals to high earners who want to consolidate their entire financial life into a single, elegant digital interface.
This integrated approach helps reduce the “friction of friction” in your daily life. By centralizing your checking, savings, and loans, you can maintain a clear, real-time view of your total liquidity. Such visibility is a cornerstone of sophisticated cash flow management.
The technology-forward design ensures there are fewer hurdles between your application and the actual disbursement of funds. It is built for the person who wants their financial tools to work as hard as they do, without unnecessary delays or digital roadblocks.
Pros:
- High credit limit of up to $50,000.
- A unified ecosystem including checking and savings.
- Rapid rate checking that leaves your credit score untouched.
Cons:
- The sheer depth of the ecosystem may feel complex for some users.
Leveraging Credit as a Tool for Wealth Expansion
High earners often mistake the nature of personal debt. Instead of seeing it as a burden, smart money managers treat these loans as tactical instruments for liquidity. It is all about moving pieces on a chessboard to maximize your overall net worth.
When applied with precision, a loan acts as a bridge. It connects your current liquid assets to much larger, lucrative ventures. Rather than letting an opportunity slip through your fingers, you can deploy borrowed capital to strike when the iron is hot.
Consider the various ways a sophisticated individual might deploy this capital. It isn’t just about borrowing money; it is about timing the market and optimizing your financial architecture. The goal is to ensure your cash works harder for you than the interest works against you.
-
Capitalizing on Arbitrage: If a rare chance arises—perhaps a distressed property sale or a private equity play—liquidity is king. A personal loan provides the immediate funds required to seal the deal. This is vital if you are waiting for a bonus or a property sale to finalize. You simply weigh the interest cost against the projected profit margin.
-
Optimizing Cash Flow: While you won’t get a tax deduction like you would with a mortgage, these loans are excellent for managing your movement of money. During years when your tax bracket is particularly punishing, using a loan to cover massive expenses can preserve your own cash. This keeps your reserves free for other high-yield maneuvers.
-
Streamlining Liabilities: Many successful professionals find themselves juggling several credit lines or premium cards with different rates. Consolidating these into one structured personal loan can be a breath of fresh air. It simplifies your monthly obligations and cuts down on the total amount of interest you’re bleeding every year.
Navigating Common Lending Traps
Earning a significant salary doesn’t make you immune to financial missteps that can bleed your net worth dry. It is remarkably easy to get seduced by a modest monthly bill while ignoring the heavy toll of the total cost of credit. For instance, when securing a $50,000 loan, a mere 2% variance in interest rates can siphon thousands of dollars away from your long-term investments.
To truly understand the weight of your debt, you must prioritize the APR over the individual monthly installment. This specific metric is your best friend because it incorporates both the interest rate and any required fees. Looking solely at your payment schedule is like looking at the tip of an iceberg; the APR reveals the massive, hidden cost beneath the surface.
Another pitfall involves a failure to balance the velocity of capital against the urgency of your financial needs. Sometimes, speed is a commodity that justifies a premium price tag. If you are staring at a golden opportunity that requires a 24-hour turnaround, that 12% loan arriving in an hour is worth its weight in gold compared to a 7% loan that leaves you waiting ten days.
On the flip side, when your goal is long-term debt consolidation, speed should move to the backseat. In that scenario, your primary mission is to hunt down the lowest possible APR. Slow and steady wins the race when you are trying to minimize the total interest paid over several years of repayment.
Finally, do not let the fine print slip past your eyes, especially regarding those pesky prepayment penalties. High earners often experience sudden bursts of liquidity and might want to settle their debt ahead of schedule to save on interest. If your lender punishes you for paying early, that seemingly “cheap” loan can quickly turn into a financial headache.
Before you put pen to paper, be direct and ask the lender: “Is there a penalty for paying this loan off in full within the first twelve months?” For professionals with fluctuating cash inflows, having the freedom to clear debt early is not just a luxury; it is a non-negotiable requirement for any savvy lending partnership.
Leave a Reply