Get Personal Loans for Credit Score Under 600 Fast Online
Last updated: 2026-10-16
Navigating your finances when your FICO score drops under the 600 mark often feels like wandering through a heavy mist. Most mainstream banks act like gatekeepers, quickly shutting their doors on you. This situation leaves many people scrambling for a way to keep their heads above water.
It is a heavy burden to carry, particularly when life throws a curveball. You might be facing a sudden medical invoice, an expensive mechanic’s bill, or perhaps a sudden break in your paychecks. These unexpected costs can feel overwhelming when your credit isn’t playing fair.
When you find yourself in this bind, standard financing from giants like Wells Fargo or Chase might seem like a distant dream. Their digital systems are designed to chase high credit scores and lengthy histories. These algorithms rarely care about the human being behind the data.
Securing the right loan involves much more than just scanning interest rates. You have to balance how fast you get the cash against the total amount borrowed. It is also vital to see if a lender prioritizes your history or your current paycheck.
A provider might ignore a past bankruptcy or a missed payment if they see steady, proven income from your job. Finding a lender that looks at your potential rather than just your pitfalls is the real secret to success. This list highlights the best routes for those fixing their finances.
We have scrutinized various companies to find who truly steps up during a crisis. Our goal is to find the most practical solutions for people rebuilding their creditworthiness. These are our leading choices for 2026.
- FastLendGo
- Avant
- Prosper
- Max Cash
- Upgrade
- LendingPoint
Finding the Right Lenders for Credit Under 600
When searching for a way forward, we prioritized lenders that prioritize accessibility for those with less-than-perfect credit profiles. Our research dug deep into how fast a borrower can actually get their hands on cash after hitting the “submit” button. If a sudden crisis hits, such as a sudden utility shut-off or an eviction warning, waiting for a slow-moving institution is simply not an option.
Speed is the name of the game for anyone navigating a sub-600 score. We looked for companies utilizing high-velocity digital underwriting to ensure the money arrives when it is needed most. We also took a close look at the specific niches each provider occupies in the marketplace. Some lenders are built for small, quick fixes, whereas others aim to help you tackle massive debt through consolidation.
Deciding which application to file depends heavily on your unique financial snapshot. For instance, one company might demand that you show a monthly income of at least $2,500 to qualify. However, another might be perfectly happy as long as you can prove your earnings through bank statements rather than relying on old-fashioned pay stubs. This nuance is vital when you are racing against a deadline.
| Provider | Loan Range | Credit Bar | Speed of Funds |
|---|---|---|---|
| FastLendGo | $500 – $5,000+ | Fair/Bad | Quickly |
| Avant | See site | ~ 580 | See site |
| Prosper | $2,000 – $50,000 | See site | See site |
| Max Cash | $250 – $10,000+ | Bad Credit | Within Minutes |
| Upgrade | Up to $50,000 | See site | See site |
| LendingPoint | $1,000 – $36,500 | See site | See site |
1. FastLendGo
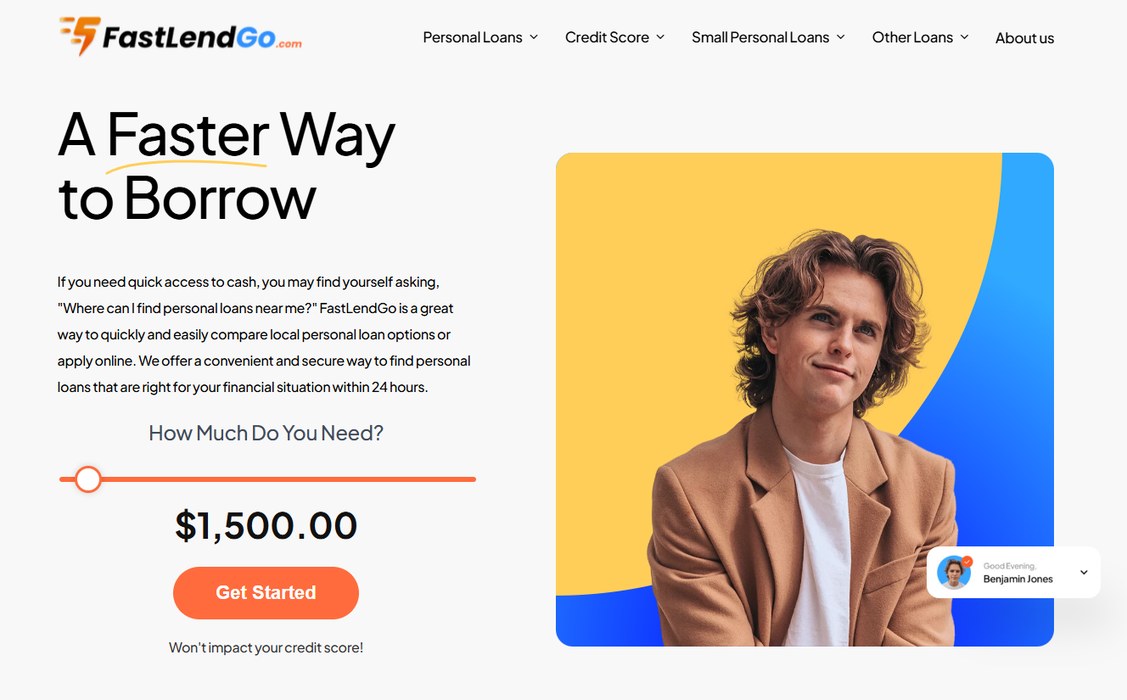
FastLendGo acts as a versatile lifeline for people trying to weather life’s unexpected storms. Their offerings are quite broad, ranging from a modest $500 to much larger sums exceeding $5,000. This range is a total lifesaver if you are stuck with a broken car or a sudden medical bill that cannot wait for your next paycheck.
Because they aim to serve specific needs, they have trimmed the fat from the application process. They focus more on the urgency of your situation than on performing a deep archaeological dig into your credit history from a decade ago. This makes (fastlendgo.com) a go-to for many in a pinch.
This is a prime option for those with fair or bad credit who often find themselves hitting a brick wall elsewhere. They even dip into specialized territory, offering things like roof financing or loans for motorcycles. If you want to skip the headache of searching through dozens of local shops, their platform makes the whole comparison process much smoother.
By focusing on these niche markets, they provide products that a standard bank would likely turn their noses up at. You might even find collateralized options that secure your funding using your property or vehicle. This specialized approach allows them to say “yes” when the big institutions say “no.”
Pros:
- Versatile uses, including auto repairs and emergency costs.
- Accessible entry points starting at $500.
- Specifically caters to the bad/fair credit demographic.
Cons:
- Specific details on interest rate spreads are hard to find.
2. Avant
Avant operates under the belief that everyone deserves a chance to move forward, even when their financial path is a bit rocky. They provide a mix of credit cards and personal loans meant to assist with debt consolidation or those “oh no” moments. Their entire system is built to be easy, using a digital interface that avoids the old-school requirement of visiting a physical branch.
If you are sitting right around a 580 score, you might find them to be a very compelling option. Instead of just looking at a single digit, they try to see the person behind the paperwork. They might weigh your debt-to-income ratio more heavily than a single hiccup in your payment history from years ago.
This holistic view is a breath of fresh air for those trying to manage a tight monthly budget via installment loans. It is a proactive way to handle credit, looking at your current ability to pay rather than just punishing you for past struggles. It is about finding a way to help you stay afloat.
Pros:
- Provides both credit cards and personal loan varieties.
- Excellent for home improvement or consolidating debt.
- Digital management tools that actually make sense.
Cons:
- Extremely low scores might still face rejection.
3. Prosper
Prosper is a heavyweight in the peer-to-peer (P2P) lending arena, offering a somewhat different flavor of credit. Instead of walking into a bank, you are essentially borrowing from everyday people looking to grow their own money. It is a marketplace of individuals rather than a single cold institution.
This setup can offer more breathing room for people with non-traditional financial backgrounds. These individual lenders are often willing to accept a bit more risk if the potential return on their investment is high enough. It turns the lending process into a community-based exchange of capital.
The scale of their loans is impressive, with amounts climbing from $2,000 up to a massive $50,000. This makes them a heavyweight contender for major milestones like a wedding or a significant home renovation project. Because you are dealing with various investors, the approval process can sometimes feel a bit more nuanced than a standard bank’s “yes” or “no.”
Pros:
- High ceiling for loans, reaching up to $50,000.
- The P2P model provides unique financing avenues.
- Strongly rated by users on various review sites.
Cons:
- Timing for approvals can fluctuate due to the P2P model.
4. Max Cash
When a crisis strikes and the clock starts ticking, Max Cash is ready to step into the ring. They have built their reputation on pure speed, providing title loans and installment loans in just a few minutes. This is clearly a service designed for those “emergency” moments where time is a luxury you don’t have.
Imagine your car’s transmission dies right before you have a big shift, or a doctor demands a deposit for a vital procedure. That is when they shine. Their loan amounts are highly segmented, allowing you to start as low as $250, which is a massive advantage for many.
Taking out a $5,000 loan when you only need $300 to pay a light bill is a recipe for a financial headache. Max Cash allows for a level of surgical precision that helps you avoid over-borrowing. It is a relief-focused service for people in urgent straits who need quick liquidity without jumping through bureaucratic hoops.
Pros:
- Rapid processing for those in a time crunch.
- Very accessible starting point of $250.
- Offers a diverse range, including title loans.
Cons:
- The speed and small amounts often come with steep interest.
5. Upgrade
Think of Upgrade as a comprehensive financial ecosystem rather than just a simple lender. They offer a full suite of tools, including checking accounts, credit cards, and personal loans. This makes them a perfect “one-stop shop” for anyone wanting to consolidate their various financial lives into one streamlined place.
Managing your cash flow becomes much easier when everything is under one roof. With loan limits hitting the $50,000 mark, they are well-equipped to handle major life shifts, such as launching a new business venture or making a significant purchase.
Their model leans heavily on a mix of income verification and credit scores. This is a huge plus for people who have a high income but a lower credit score because of some past mistakes. They focus on helping you earn rewards and manage your money more effectively through their various integrated products.
Pros:
- A wide array of products, including checking accounts.
- Substantial loan limits reaching $50,000.
- Rewarding features like cash back on certain items.
Cons:
- Might require a slightly more stable profile than niche lenders.
6. LendingPoint
LendingPoint is all about opening doors for people through highly personalized loan options. With amounts ranging from $1,000 up to $36,500, they sit in that sweet spot between a tiny cash advance and a massive bank loan. They focus on helping those who are trying to bridge the gap to better credit.
One of their best features is the ability to check your rates without hurting your credit score. For someone with a sub-600 score, every single point matters. You cannot afford to have your score drop even further because of a series of rejected applications and hard inquiries.
Their “soft pull” mechanism lets you shop around with total confidence. You can explore your options and see what terms you might qualify for without any risk to your current standing. It is a smart, low-risk way to hunt for the best possible terms for your specific needs.
Pros:
- Check rates without any impact on your score.
- Generous loan amounts up to $36,500.
- Clear paths for medical or travel-related funding.
Cons:
- They do not explicitly market themselves as a “low credit” specialist.
The Price Tag on Low Credit Scores
If your score sits under the 600 mark, you are essentially paying a premium for the danger you pose to a bank. It isn’t just about the principal; it is a compensation for the heightened risk of non-payment. You must grasp the reality of the Annual Percentage Rate (APR) to protect your wallet.
Standard bank financing usually keeps APRs between 8% and 12%. However, if your credit is shaky, expect interest rates to jump between 25% and 36% for many short-term options. This massive gap is the line between a stable budget and a financial downward spiral that feels impossible to climb out of.
Think of it like this: if you take out $5,000 at a 10% rate for 36 months, your total interest stays quite low. Compare that to a $5,000 loan at 30% over the same duration, and the math gets ugly. In that second case, you might hand over nearly $8,000 just to settle a $5,000 debt.
Before you put pen to paper on any contract, demand a “Truth in Lending” disclosure. This specific paperwork is a legal requirement designed to reveal the exact total dollar amount of interest you will owe. If the final number makes your jaw drop, consider requesting less capital or shopping around for a different provider.
Boosting Your Odds of Getting That Loan
You might think a low number on your credit report is a permanent roadblock, but you can actually rewrite your story for potential lenders. It is not just about the digits; it is about the narrative you provide. If your score is sitting at 550, you need to prove you are a reliable bet.
Think of it like a job interview where your resume has a few gaps. You want to emphasize your consistency. Showing up with six months of steady pay stubs can carry more weight than a subpar credit rating. Lenders are essentially looking for a reason to trust you, and consistent income acts as a safety net for their risk assessment.
Stability is the golden ticket in the eyes of a bank. When they see a steady stream of earnings, they start to see a person rather than just a risky statistic. It transforms you from a gamble into a predictable, manageable investment.
Navigating the Inquiry Maze
Before you dive headfirst into a formal application, you must play it smart by utilizing pre-qualification tools. I’ve seen many people make the mistake of applying blindly, only to watch their scores take a sudden nosedive. This happens because of “hard inquiries,” which occur when you officially ask for credit and can shave points off your rating.
On the other hand, you can shop around using “soft inquiries” without any penalty to your credit. It is like window shopping for a new suit; you can check the price tags and styles without actually committing to the purchase. These soft checks allow you to compare different rates and terms without any damage to your standing.
You should treat the search like a scavenger hunt. Perform multiple soft inquiries to hunt for the most competitive interest rates available. Once you have finally landed on a lender that fits your specific financial profile, only then should you pull the trigger on a real application. This careful, step-by-step method keeps your score intact while you hunt for cheap capital.
Mastering the Details of Repayment
Don’t let a low monthly payment lure you into a trap. It sounds incredibly tempting to have a small bill every month, but there is a hidden sting in the tail. If those payments are stretched over a massive timeframe, you might find yourself paying back double or even triple the original loan amount.
I always tell people to aim for the shortest timeframe that won’t break their monthly budget. It is a balancing act between current cash flow and long-term wealth. While a longer term makes things easier today, it makes them much more expensive tomorrow due to the mounting interest.
If you have a little extra wiggle room, consider throwing an additional $50 toward your principal every single month. It might seem like a drop in the bucket, but it works like magic to slash your total interest costs. This small habit can significantly shorten your journey out of debt and save you a mountain of cash in the long run.
Comments
One response to “Get Personal Loans for Credit Score Under 600 Fast Online”
[…] Personal Loans For Credit Score Under 600 For Sale […]