Get First Time Personal Loans No Credit History Online Today
Last updated: 2026-10-16
Attempting to secure a loan from a major bank without an established credit background is a bit like stumbling through a dark hallway without a lantern. You might find yourself feeling invisible if you have never utilized a credit card or taken out an auto loan before. It is a maddening loop where lenders demand proof of reliability that only comes from having existing debt.
This financial paradox leaves countless individuals stuck in a waiting room. Newcomers to the country, recent graduates entering the workforce, or anyone bouncing back from a fiscal stumble often face a closed door. It frequently feels as though the entire economic machinery was built to leave you standing on the curb, watching others move forward.
However, the landscape of lending has undergone a massive transformation throughout 2026. Financial institutions are no longer obsessed with a single FICO digits to determine your eligibility. Instead, they are peering into your real-world earnings, the stability of your current employment, and how you manage your daily cash flow.
Your track record with rent payments and monthly utility bills carries significantly more clout now than it did back in 2021. By evaluating your entire fiscal personality instead of just one numerical snapshot, banks can finally say “yes” to millions of people once deemed uncalculable. This move toward non-traditional data means your steady paycheck is your strongest ally.
- JetzLoan
- Discover
- OppLoans
- OneMain Financial
- Coastline Credit Union
Our Methodology for Assessing Lenders for First-Time Borrowers
Our primary mission while constructing this list was locating options for individuals lacking a financial history. We hunted for institutions that permit “soft pulls” or preliminary qualification checks. This distinction is a total game-changer for anyone starting out.
Using a soft pull allows you to scout potential interest rates without risking your standing. Think of it like window shopping; you can browse various deals without incurring any penalties or negative consequences to your profile.
In contrast, a “hard inquiry” carries a different weight entirely. This occurs once a bank scrutinizes your full report to finalize an application, which can knock points off your FICO score. We focused on firms utilizing soft inquiries early on to shield your nascent credit from harm.
Efficiency and honesty served as our next major benchmarks. A company that buries extra costs in tiny text or drags out deposits for weeks is a non-starter during a crisis. When your transmission dies or a doctor sends a surprise bill, you need liquidity, not empty promises.
We prioritized providers that offer straightforward amounts, rapid disbursements, and accessible customer service. It is vital to be able to speak with a real person when things get complicated. We filtered for clarity and speed above all else.
Transparency regarding the APR was a non-negotiable requirement for our team. This specific figure tells the actual story, as it incorporates both interest rates and any compulsory service charges. Examining the APR reveals the true weight of the loan’s cost over its lifespan.
Finally, we analyzed if a loan functions as a stepping stone or a financial anchor. We leaned toward lenders providing steady, predictable monthly installments. Steer clear of predatory structures that trigger a downward spiral of debt.
We scrutinized the mechanics between simple and compounding interest. Because compounding can make your total debt swell much faster than anticipated, we prioritized lenders that won’t let your obligations spiral out of control.
| Company | Borrowing Range | Cash Delivery | Impact on Score | Duration Limits |
|---|---|---|---|---|
| JetzLoan | $500 – $35,000 | 24 hours or less | No hard credit pull | see site |
| Discover | $2,500 – $40,000 | Next business day possible | No impact to credit score | see site |
| OppLoans | see site | Same-day funding available | Does not affect FICO score | see site |
| OneMain Financial | $1,500 – $30,000 | 1 hour after signing possible | No credit score impact | 24-60 months |
| Coastline Credit Union | see site | see site | see site | see site |
Leading Loan Providers for 2026
1. JetzLoan
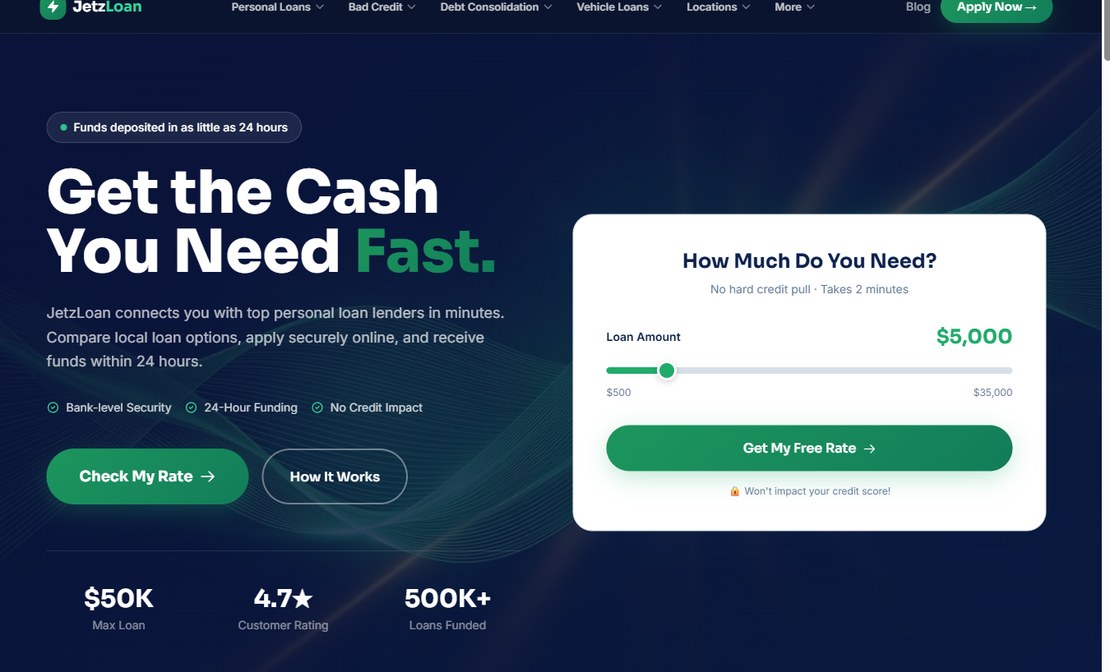
Navigating the murky waters of a thin credit profile can feel overwhelming for anyone. JetzLoan acts as a compass, bridging the gap between you and a variety of premier lenders to simplify your search. It is a lifesaver if a sudden car repair or urgent debt consolidation leaves your bank account feeling a bit thin.
Instead of running in circles and applying to a dozen different places, which can trigger multiple hard inquiries, JetzLoan streamlines the entire process. They consolidate your various options into one smooth experience. This approach protects your score while you are still getting your feet wet with financial decisions.
The application process is a breeze, typically wrapping up in about two minutes. Because they utilize a “no hard credit pull” method during the initial phase, you can explore your options without any anxiety. You can even check your eligibility for up to $35,000 without any pressure at all.
This setup is a godsend for first-time borrowers. If you are still learning to decode the fine print of loan offers, you can browse without risking your financial standing. It is a safe way to test the waters before committing to a long-term agreement.
Pros:- Capital delivered within 24 hours
- Availability up to $35,000
- Rapid two-minute application
- No credit score impact during initial check
- Requires filling out a basic form to begin
2. Discover
As a giant in the banking world, Discover provides the kind of rock-solid stability that most new borrowers crave. Their personal loans aren’t just about a quick injection of cash; they are designed for individuals seeking a long-term financial partner. With rates starting at 6.99% APR, they offer a legitimate ladder for upward mobility.
If you are transitioning from having “no credit” to actively rebuilding, Discover provides a structured roadmap. They reward those who stay disciplined and pay on time. Their pre-approval method is remarkably transparent and does not touch your credit score. Should you receive the green light, funds can arrive as early as the following business day.
For anyone with a steady paycheck looking to partner with a major institution, they are a reliable choice. Their digital infrastructure is top-tier thanks to their massive scale. You can easily manage your monthly payments, view statements, and track your financial growth through a very intuitive mobile app.
Pros:- Loan caps reaching $40,000
- Competitive APRs from 6.99%
- Funds arrive by the next business day
- Highly reputable and FDIC-insured institution
- Income verification may be more stringent
3. OppLoans
OppLoans is built for the person who has been told “no” by every big-name bank in town. Rather than fixating on a static FICO score, they look for other reasons to say “yes” to your application. This makes them a vital lifeline for those just starting their credit journey or those facing a temporary setback, like a sudden medical bill.
They prioritize your current capacity to repay, often analyzing your real-time bank activity instead of just a single bureau number. The platform is designed for lightning speed, sometimes offering same-day funding. It serves as a much safer alternative to the often-predatory payday loan market.
While payday loans are famous for crushing interest rates that can soar above 400% APR, OppLoans provides a structured path forward. You can address your immediate cash needs without falling into a debt trap fueled by hidden fees and astronomical terms. It is a more responsible way to bridge a gap.
Pros:- Potential for same-day funding
- FICO score remains unaffected
- Tailored for those denied by traditional banks
- Transparent terms with no hidden fees
- Interest rates might exceed traditional bank rates
4. OneMain Financial
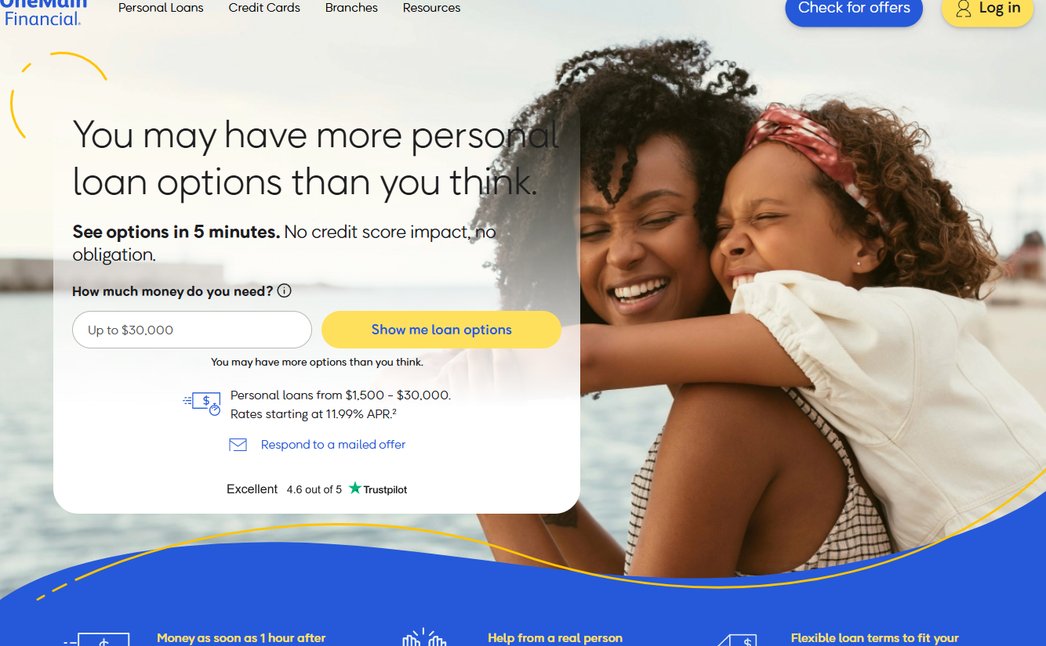
OneMain Financial hits the sweet spot between modern digital convenience and personal human connection. If you find chatbots frustrating and would rather chat with a real person, their 1,300 local branches are a massive advantage. This is ideal if you need to sit down with an expert to explain a unique situation, like a recent shift in your employment.
That human touch can often be the deciding factor between a rejection and an approval. They offer various repayment terms, ranging from 24 to 60 months, allowing you to mold a monthly payment that fits your specific budget. With loan amounts starting at $1,500, they cover everything from minor home repairs to larger debt restructuring.
The speed of their service is quite startling. You could potentially see your funds available just one hour after you sign the paperwork. It is rare to find such rapid turnaround from a lender that maintains such a massive physical footprint across the country.
Pros:- Massive branch network for face-to-face support
- Rapid funding (just 1 hour after signing)
- Flexible repayment terms up to 60 months
- No-obligation pre-qualification check
- Interest rates can vary widely
5. Coastline Credit Union
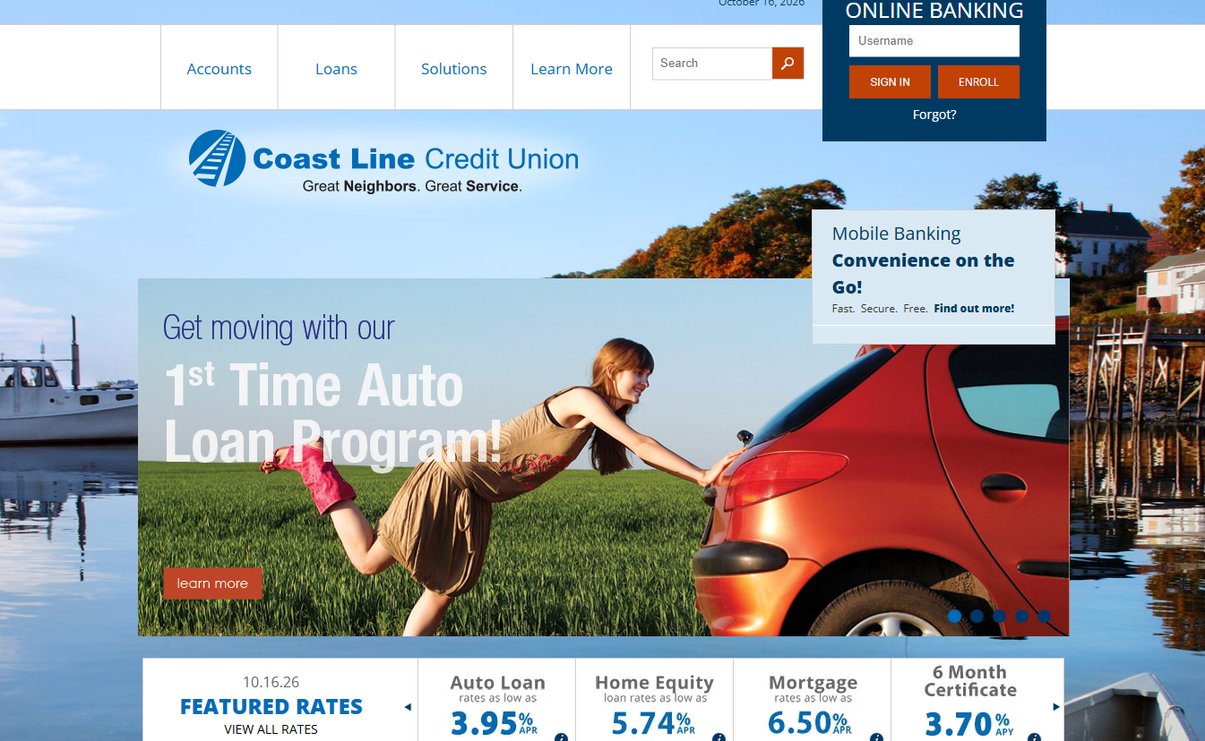
Credit unions are frequently the best-kept secret for individuals entering the world of borrowing. Coastline Credit Union utilizes a member-first philosophy, which typically translates into more personalized service. Unlike commercial banks driven by shareholder profits, these are cooperatives owned directly by the people who use them.
Their mission is centered on community service, which often leads to more flexible underwriting for local residents. While you may need to meet specific membership criteria—such as living in a certain area or working in a specific industry—the benefits often outweigh the effort. They provide various lending solutions and digital tools to keep your finances in check.
This is a “slow and steady” approach to building a solid financial foundation. The lender is genuinely invested in your long-term prosperity, rather than just trying to squeeze every possible cent of interest out of you this month. It is about growing together over time.
Pros:- Service model focused on members
- A wide array of financial products
- Possible for better rates in the long run
- Specific membership requirements may apply
Decoding Interest Costs: APR vs. Simple Interest
Navigating the fine print of loan advertisements can feel like walking through a minefield without a map. You’ll likely encounter two distinct figures that seem to tell different stories. To protect your hard-earned money, you must learn to distinguish between them before signing any papers.
The first figure you will encounter is the Simple Interest Rate. Think of this as the raw price tag for borrowing the principal amount. While it sounds straightforward, relying solely on this number is a recipe for financial heartbreak.
It fails to account for the hidden hiccups that can inflate your debt. It essentially tells you only a fraction of the true cost. It is merely the baseline, not the full picture of your commitment.
On the other hand, the Annual Percentage Rate (APR) is the real heavyweight in this equation. This figure provides a much more honest look at your financial obligation. It combines the basic interest rate with every extra cent required to finalize the deal.
This includes sneaky additions like documentation costs or origination fees. If you want to know how much is actually leaving your pocket, the APR is your best friend. It is the ultimate yardstick for comparison.
Imagine you secure a $5,000 loan. The lender promises a 10% interest rate, but they tuck away a $500 “processing fee” in the fine print. Suddenly, your real cost—the APR—is significantly higher than that initial 10% figure.
Always treat the APR as your North Star when weighing different lenders. Suppose Lender A advertises a 7% rate but piles on heavy fees. Meanwhile, Lender B offers an 8% rate with zero extra charges. In this scenario, Lender B is actually the better bargain for you.
Don’t let a shiny, low interest rate distract you from the reality of your debt. It is easy to get hooked by a “headline” rate that looks great on a billboard. Always check the APR to ensure you aren’t paying more than you intended.
Core Principles for First-Time Borrowers
Stepping into the world of credit can feel like walking a tightrope without a net. To ensure you don’t lose your balance, you must adhere to a few fundamental guidelines that safeguard your wallet and your peace of mind.
Think of these principles as your financial compass. They might seem strict, but they are the difference between a helpful tool and a heavy anchor around your neck.
Follow these guidelines closely to navigate your debt journey safely:
- The 30% Monthly Limit: Never let your installment obligations exceed 30% of your net income. For instance, if your monthly paycheck is $3,000, your debt obligations should remain significantly lower than that threshold. If a lender demands half of your take-home pay, you are effectively flirting with bankruptcy.
- Resist the Urge to Stretch Terms: It is incredibly easy to get seduced by a 60-month loan because it makes the monthly bill look tiny. However, this is a classic trap. By extending the time, you end up feeding the interest monster. Over a 60-month period, the interest could nearly double your original debt. If your budget allows, always opt for a 36-month term to save money.
- Calculate the Full Repayment Amount: Before putting pen to paper, always ask yourself, “How much cash will have actually left my pocket by the final installment?” This figure represents the real price of your loan. If you take out $2,000 but the total repayment reaches $3,500, you have paid a $1,500 premium for that credit. Checking this prevents nasty surprises when your bank statements arrive later.
Strategies for Securing Your Initial Loan
Before you press that submission button, you must draw up a blueprint. Think of a loan as a long-term pact to pay back funds, rather than a simple cash injection. You should determine the precise figure you require to avoid the trap of over-borrowing. It is far less stressful to settle a modest debt than a mountain of debt.
I once knew a friend who grabbed the maximum limit just to feel secure. Instead, he ended up throwing money down a drain of interest on funds he never touched. This is a classic mistake that turns a small help into a heavy burden. Aim for precision instead of excess to keep your finances healthy.
Do not let a low monthly installment blind you to the real cost. You must scrutinize the APR alongside the cumulative total you will repay by the end of the term. Often, a tiny monthly bill is just a mask for a much longer duration. This can ultimately bleed your wallet dry through excessive interest charges.
Grab a digital tool to play with the numbers. You might find that adding just $25 to your monthly payment can shave hundreds from your total interest. Small adjustments today act as a shield for your future self. It is better to be proactive now than to be drowning in debt later.
Collect all necessary paperwork before you dive into the application process. Even if a provider claims a hard credit check isn’t required, you’ll still need to verify your identity and salary to finalize things. Being prepared keeps the momentum going when you are halfway through the digital forms.
Keep your latest pay slips, bank records, and government ID close at hand. If your goal is debt consolidation, ensure you have all your current creditor statements lined up as well. Some lenders prefer to settle those old balances for you directly. This particular shortcut can make the entire ordeal feel like a breeze.
Leave a Reply