Best Rates for Bad Credit Loans California: Quick Approval Online
Last updated: 2026-10-16
Navigating your finances in the Golden State can feel like wandering through a dense mist, especially if your credit rating isn’t quite where it needs to be. Many people across the state are constantly searching for a lifeline to handle unexpected expenses.
Sometimes it is an urgent trip to the mechanic in Los Angeles, and other times it is a sudden hospital bill in San Diego. When life throws these curveballs, standard banking institutions often slam the door shut before you can even explain the situation.
Searching for the right lender requires looking beneath the shiny surface of flashy commercials. You have to dig into the nitty-gritty details, such as the actual speed of fund disbursement and the interest rates hiding in the fine print.
It is incredibly easy to fall for the siren song of “small monthly installments.” However, the real weight of your obligation is dictated by your loan term and the Annual Percentage Rate (APR). Do not let marketing speak fool you.
The following selection showcases the premier choices for California residents who require adaptability. These companies provide a genuine chance at securing funds, even if your previous financial journey has been a bit of a bumpy ride.
- OneMain Financial
- Avant
- FastLoans CA
- Upgrade
- VivaLoan
- GreendayOnline
- United Finance
Sizing Up California’s Options for Subprime Borrowers
Finding a reliable source for cash when your credit score is acting up feels like searching for a needle in a haystack. To make sense of the chaos, we scrutinized several specific metrics. We looked at approval odds for those with less-than-stellar credit, how quickly money lands in your pocket, and the honesty of their fine print.
It is vital to realize whether a company will perform a hard credit pull before you sign on the dotted line. Navigating these waters without knowing the rules can be a recipe for disaster. You want to avoid any surprises when you’re already feeling the financial squeeze.
A “soft pull” acts like a window shopper’s glance, allowing you to gauge your odds and interest rates without touching your score. Conversely, a “hard pull” is a deep dive into your financial history. This occurs during a formal request and can cause your rating to take a temporary tumble.
Understanding this nuance is like having a shield for your creditworthiness. It keeps your score from taking unnecessary hits while you’re just window shopping. Knowing the difference might just be the lifeline your credit score needs to stay afloat during a rough patch.
We also weighed how much you can borrow against how long you’ll be paying it back. A massive loan limit sounds great until you realize the interest rates are predatory. It’s a bitter pill to swallow when a high APR turns a manageable debt into a lifelong burden.
Consider a $5,000 loan at a 36% APR over 36 months. The total interest you’ll pay is a mountain compared to a $5,000 loan at 15% APR for that same term. Our list highlights lenders that offer transparent structures and a clear, fair path toward debt freedom.
| Provider | Borrowing Limits | Transfer Speed | Credit Standards | Primary Advantage |
|---|---|---|---|---|
| OneMain Financial | $1,500 – $30,000 | 1 hour or less | Check website | Local branch access |
| Avant | Check website | Check website | Check website | Adaptable options |
| FastLoans CA | $1,000 – $35,000 | Within 24 hours | No hard credit pull | CA state licensed |
| Upgrade | To $50,000 | Check website | Check website | Debit card cash back |
| VivaLoan | $100 – $15,000 | By tomorrow | All credit levels ok | Low starting amounts |
| GreendayOnline | $100 – $5,000 | Same day | No credit check | Instant emergency funds |
| United Finance | Up to $20,000 | Check website | Check website | Operating since 1922 |
Comparing Collateralized and Non-Collateralized Lending Options
As you navigate your various borrowing alternatives, you will inevitably encounter two primary categories: secured and unsecured options. Distinguishing between these two pathways is absolutely critical for your ongoing fiscal stability and your approach to risk management. It can truly mean the difference between a minor bump in the road and a full-blown financial catastrophe.
An unsecured loan, which includes many personal loan products offered by Avant or Upgrade, operates without requiring any collateral. You are not forced to hand over your house deed or your car title to access the necessary funds. Because the bank assumes a higher level of danger by not having a physical asset to grab if you miss a payment, the interest rates tend to be steeper.
Nevertheless, for a significant portion of the California population, having no direct threat to personal property makes this the most attractive choice. It feels much safer to avoid tying your lifestyle to a piece of metal on wheels. This peace of mind often outweighs the slightly higher cost of borrowing.
On the flip side, securing a loan requires you to offer up an asset—perhaps a savings account or a vehicle—to act as collateral. Should you find yourself unable to meet your repayment obligations, the creditor possesses the legal authority to take that asset to recover their money. It is a high-stakes gamble for anyone playing with limited funds.
While these secured arrangements frequently come with more favorable, lower interest rates, the threat of losing your transport can trigger a massive hardship. You must carefully balance the savings on interest against the terrifying possibility of losing your belongings. It is a delicate dance between cost and security.
Top-Rated Lending Options
1. OneMain Financial
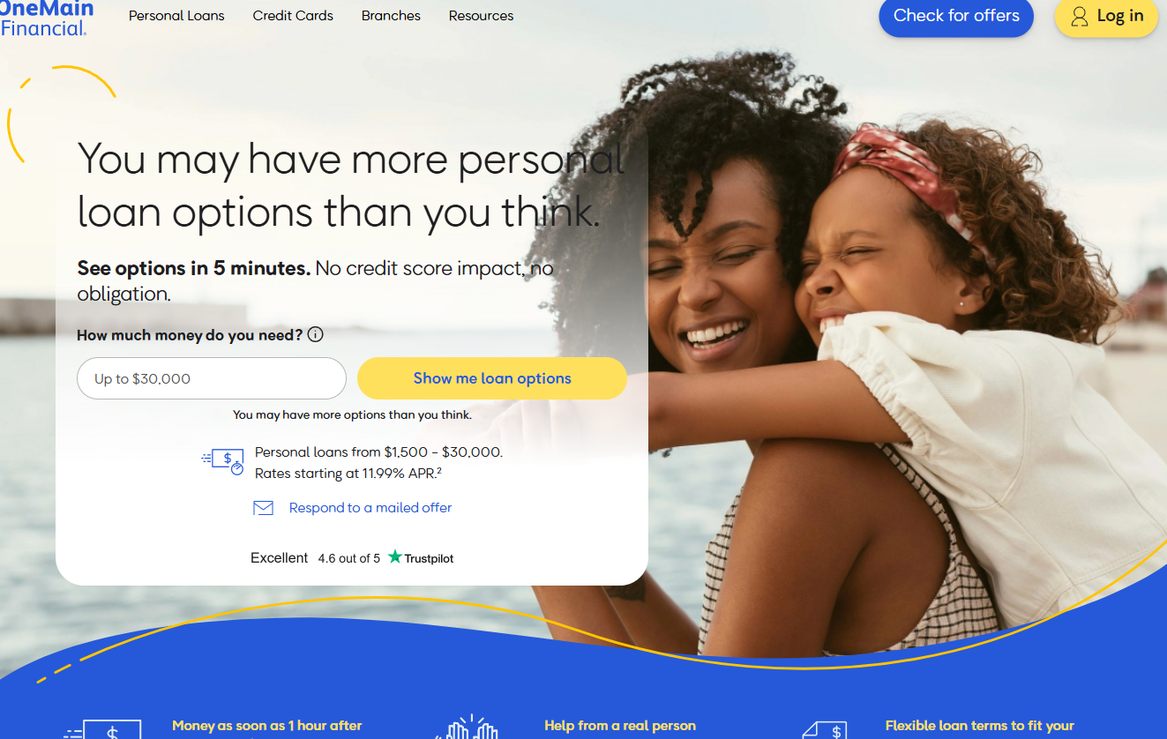
If you are the type of person who prefers looking someone in the eye when discussing money, OneMain Financial might be your best bet. They maintain a massive footprint of over 1,300 branches, blending high-tech digital tools with the classic, face-to-face support you might crave. It is a perfect safety net for anyone who feels uneasy signing away large sums of cash through a tiny smartphone screen.
Sometimes, sitting down in a local office—perhaps in Fresno or Sacramento—can turn a mountain of confusion into a molehill. That physical presence builds a bridge of trust that digital apps simply cannot replicate. Their personal loan options are quite flexible, covering everything from $1,500 up to a substantial $30,000 for those larger life expenses.
Budgeting becomes much easier when your monthly outlays are set in stone. They provide fixed payments on terms ranging from 24 to 60 months, ensuring your costs don’t jump around even if the economy goes through a rough patch. With interest rates starting at 11.99% APR, you get a clear, structured roadmap to tackle your debts.
Pros:
- A vast network of physical locations for in-person assistance.
- Rapid distribution, with funds potentially arriving an hour after signing.
- Predictable monthly costs to simplify your household budget.
Cons:
- Demands more active engagement than purely app-based lenders.
2. Avant
Think of Avant more as a financial co-pilot than just another place to grab a quick loan. They aim to provide a toolkit for your entire financial journey, whether that involves building credit via a new card or cleaning up old debts. It feels less like a cold, one-time transaction and more like a dedicated service for your growth.
This approach is a godsend for anyone trying to roll several high-interest obligations into one single, manageable monthly bill. They understand that life is messy and unpredictable, so they focus on providing various solutions like debt consolidation, home improvements, or emergency cash. It is a flexible way to keep your head above water.
Their digital setup is tailor-made for the person on the move, allowing you to sort out your finances during a commute or a quick coffee break. This makes them a top contender for those needing targeted assistance to steady their ship during turbulent times.
Pros:
- Focuses on helping you make long-term financial progress.
- A diverse array of products, from loans to credit cards.
- A digital interface that is incredibly smooth and intuitive.
Cons:
- Specific interest rates and terms aren’t always crystal clear from the start.
3. FastLoans CA
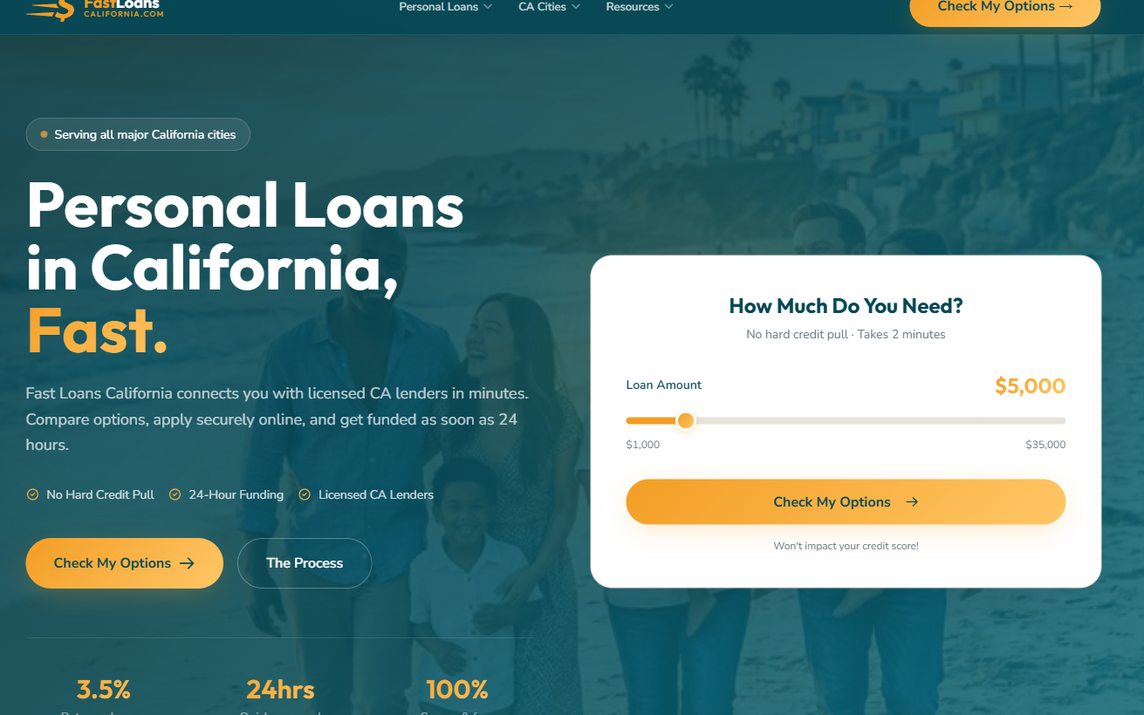
When California residents find themselves in a real bind, FastLoans CA acts as a bridge to licensed lenders throughout the Golden State. They prioritize lightning-fast service, aiming to get funds into your hands within 24 hours. Their streamlined process means you can check your eligibility in just a few minutes.
When a pipe bursts or a medical bill lands on your desk like a bombshell, every second counts. This speed is vital for those urgent, time-sensitive moments where cash is needed immediately. Perhaps the biggest perk is that checking your options won’t trigger a hard credit pull, meaning your score remains untouched during the inquiry.
With loan limits reaching as high as $35,000, they can handle everything from a small repair to a major renovation. Because they focus specifically on the California market, they are well-versed in the local legal landscape, offering an extra layer of security for every borrower they serve.
Pros:
- Checking your options won’t hurt your credit score.
- Extremely rapid approval and fund disbursement.
- Provides assistance to a huge number of families across California.
Cons:
- Interest rates might be much higher than what a traditional bank offers.
4. Upgrade
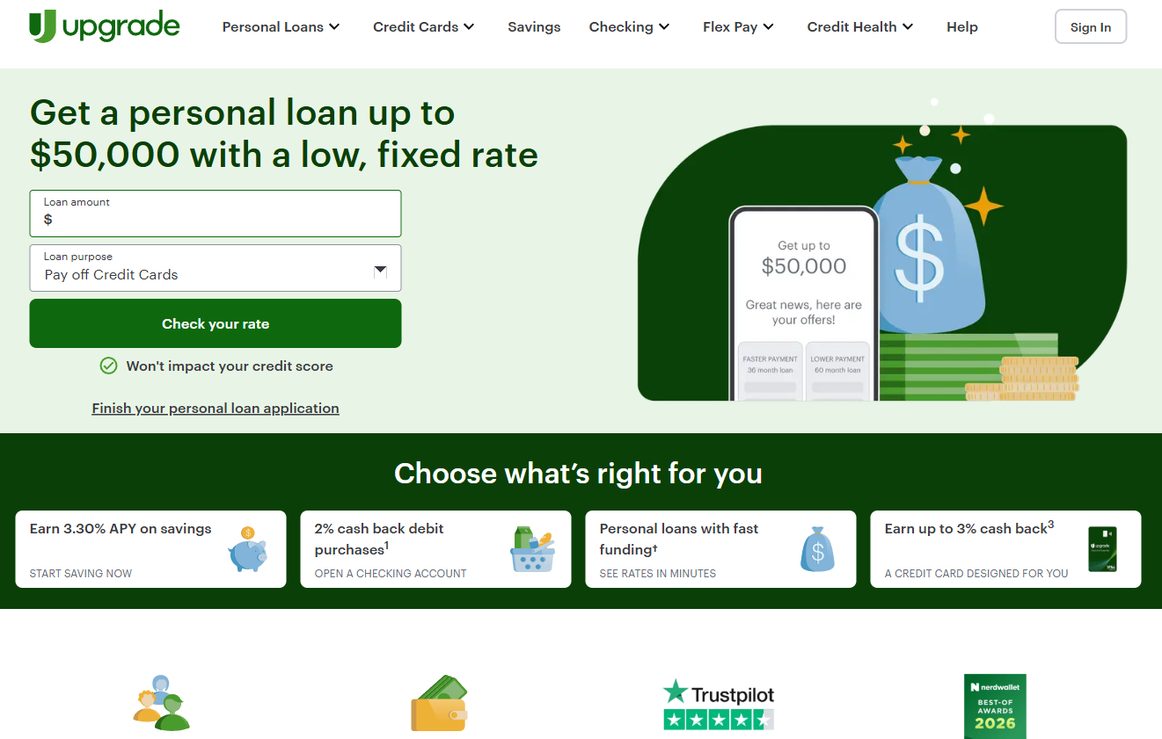
Upgrade is a heavyweight in the personal loan arena, having assisted over 8 million customers. With loan ceilings hitting $50,000, they are an ideal choice for significant milestones or aggressive debt restructuring. If you are looking to sweep away high-interest credit card balances, their generous limits offer a very real path to freedom.
They offer more than just a way to borrow; they provide a full suite of financial tools, including checking accounts. Some of these accounts even offer 2% cash back on your purchases, which is a nice little bonus. It is a clever way to blend your daily banking habits with your long-term borrowing needs.
By keeping your banking and your loan under one roof, you can view your entire financial picture on a single dashboard. It is a massive time-saver for anyone who is tired of jumping between five different apps to see where their money actually went.
Pros:
- Impressive loan limits that reach up to $50,000.
- Offers checking accounts that include rewarding features.
- Allows for quick rate checks without dinging your credit.
Cons:
- The best rates are often reserved for those with stronger credit.
5. VivaLoan
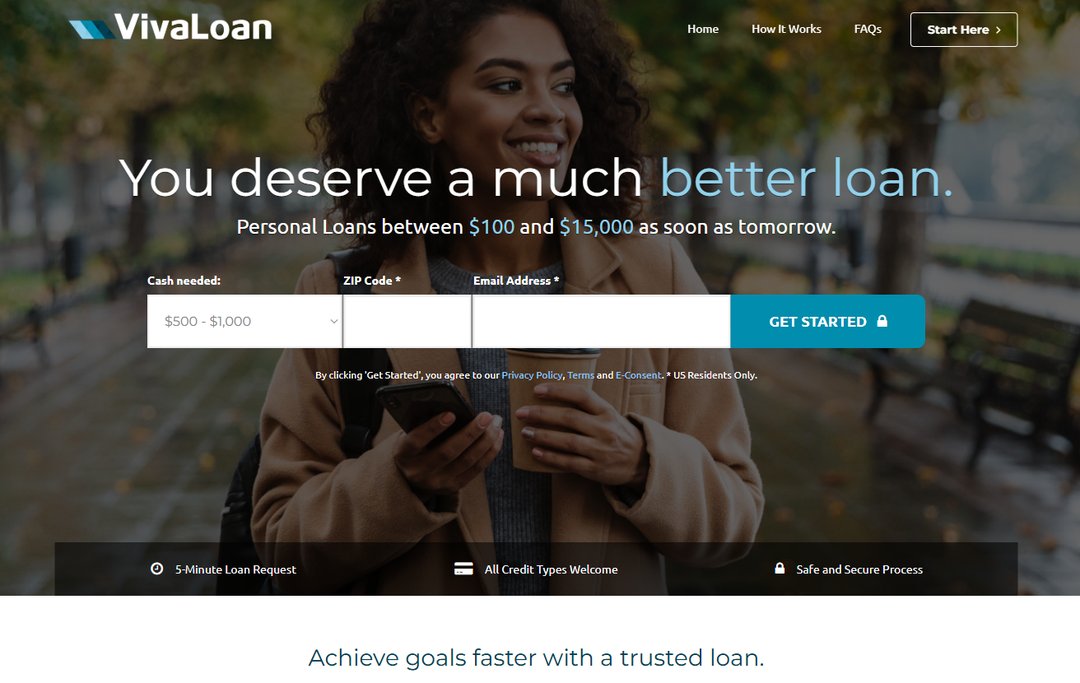
If you just need a small amount of cash to plug a hole, VivaLoan is a fantastic option. They offer micro-loans starting at just $100, which is perfect for those “life happens” moments like a sudden flat tire. It’s a smart way to handle a minor crisis without getting tangled in massive, long-term debt.
The whole process is built for speed, taking roughly five minutes to complete a request. Once you get the green light, you can typically expect your money via direct deposit by the very next business day. For anyone who feels like they need cash “yesterday,” this turnaround is hard to beat.
The simplicity of their application is really where they shine. By cutting through the red tape and the mountain of paperwork found at big banks, they make it easy for people to solve their immediate problems without a headache.
Pros:
- Very accessible entry point with $100 minimums.
- Funds are often available by the next business day.
- An incredibly straightforward and quick application.
Cons:
- There is a ceiling on how much you can borrow, capped at $15,000.
6. GreendayOnline
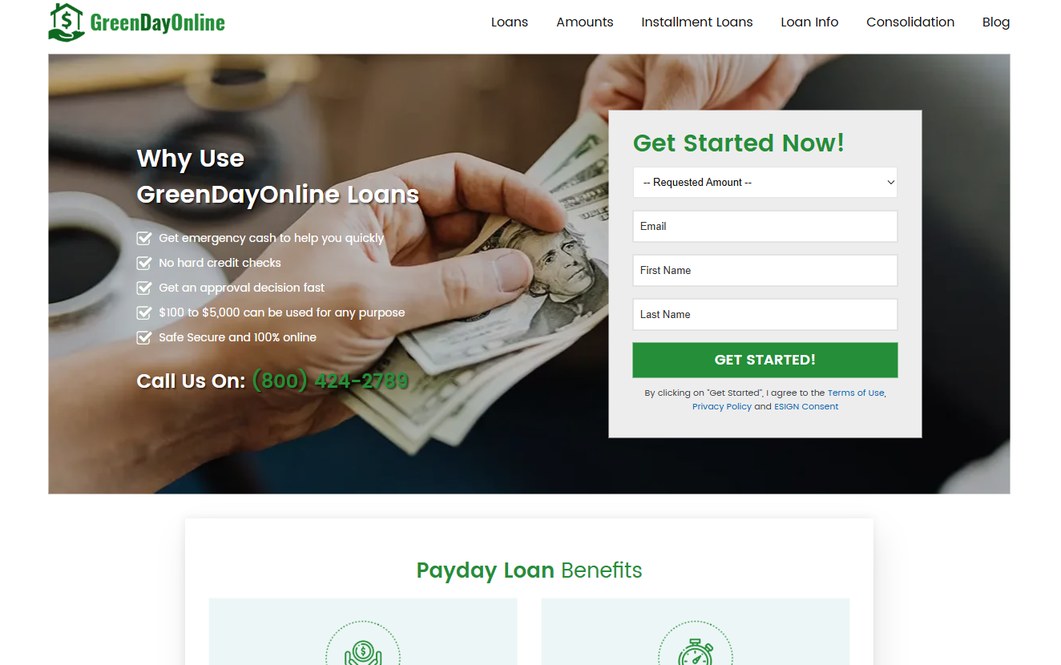
When an absolute emergency strikes and you’ve run out of options, GreendayOnline provides specialized installment loans designed for those in a pinch. They cater specifically to those with poor credit by avoiding hard credit checks entirely. For anyone who has been frozen out of the traditional banking world, this can be a vital lifeline.
This is often the “last resort” for individuals facing severe credit damage or those navigating the complexities of bankruptcy. With amounts between $100 and $5,000, you can get quick liquidity for immediate needs. Their online form is built for speed, aiming to get you an answer almost immediately.
While these are high-speed options, they are structured as installment loans. This means you pay the money back over time rather than in one lump sum, making the repayment process much more digestible than a standard payday loan.
Pros:
- No hard credit checks are required for the approval process.
- Potential for receiving cash on the very same day.
- A very simple and user-friendly application.
Cons:
- The interest rates on these types of loans can be quite steep.
7. United Finance
United Finance brings a sense of old-fashioned stability to the modern lending market, having been operating since 1922. While many newcomers are digital-only, United Finance offers a sense of history that provides comfort when you are navigating sensitive financial decisions. A century of business is a powerful way to prove you aren’t going anywhere.
They handle both personal and auto loans, with personal options going up to $20,000. Their philosophy centers on keeping things simple and accessible for the everyday borrower. If you want a traditional lending experience that prioritizes peace of mind, they are a very reliable choice.
Having survived everything from the Great Depression to today’s digital age, their longevity is impressive. This can give a significant boost of confidence to cautious borrowers who are wary of flash-in-the-pan digital lenders that might vanish overnight.
Pros:
- A long and established track record in the industry.
- Provides both personal and vehicle loan products.
- Maintains a focus on accessible, personalized lending.
Cons:
- Lacks some of the cutting-edge, instant digital features of newer apps.
Boosting Your Approval Odds
Having a bruised credit score doesn’t necessarily mean you’re out of the running for a loan. Many California lenders cast a wider net, looking past your FICO number to see if you can actually manage the repayment process. Think of it like a job interview; you want to show up fully prepared rather than scrambling for details when they ask.
Getting your ducks in a row early can prevent a series of frustrating denials. Every time a lender pulls your file, it leaves a mark on your report. By prepping your paperwork beforehand, you avoid unnecessary inquiries that might further damage your standing.
Before you dive into the digital application, make sure you have these essential items sitting on your desk:
- A legitimate, state or federal ID, such as your Passport or Driver’s license.
- Evidence of your California residence, perhaps a rental contract or a recent bill for utilities.
- Verifiable earnings, which usually entails your latest bank records or two most recent pay stubs.
- Your Social Security number to confirm you are who you say you are.
Making sure your revenue stream is crystal clear is absolutely vital. For those navigating the gig economy or working as freelancers, the path is slightly more uphill. If you can present a neat stack of tax filings or a steady trail of bank deposits, you’ll be in a much stronger position.
Another critical factor is your debt-to-income ratio, often referred to by pros as your DTI. Lenders want to ensure your monthly bills don’t swallow up too much of your gross monthly earnings. It’s a delicate balancing act that dictates whether they see you as a risk or a reliable borrower.
If you have a little extra cash lying around, consider chipping away at a small credit card balance before you hit the “apply” button. This small nudge can improve your DTI and present a much more polished version of your financial life to the bank.
Steering Clear of Financial Traps
Before you put pen to paper, you must grasp the full price tag of your debt. A small monthly installment can be a siren song, pulling you into deep waters. If the repayment period stretches too far, you might find yourself handing back twice your original principal.
Picture a $5,000 loan where the bill is $200 each month. It feels light on the wallet, right? However, if that agreement spans 36 months, your total payout hits $7,200. That $2,200 gap is the actual penalty for your borrowing.
Don’t just look at the monthly bite; demand to know the exact dollar amount you will have paid by the end. It is the only way to see the forest through the trees. If you only focus on the monthly chunk, you might miss the mountain of interest growing in the background.
Another blunder involves sprinting through the application without scrutinizing the tiny print. Some lenders are masters of camouflage, tucking administrative charges or early exit fees into the shadows. These hidden costs can snowball faster than a mountain avalanche.
Keep a sharp eye out for “prepayment penalties.” These are essentially fines that punish you for being responsible. If you find yourself with extra cash and want to clear your debt ahead of schedule, these clauses will make it incredibly expensive to do so.
You deserve the flexibility to crush your debt early and dodge extra interest without getting slapped with a fee. Take a moment to pause, weigh the various APRs, and ensure the plan aligns with your real-world paycheck. Being a hawk today stops a nightmare from haunting you tomorrow.