Top-Rated Personal Loan with Co Signer: Secure Your Best Rates Today
Last updated: 2026-10-17
Navigating the world of lending while carrying a low credit score is much like steering a ship through a dense mist without any compass. You might find yourself knocking on a family member’s door or asking a trusted buddy to step in as a co-signer. Their solid financial history acts as a sturdy bridge over your credit hurdles.
Sometimes, this small gesture is the only thing standing between a denied request and the funds required for a sudden hospital visit or an unexpected trip to the mechanic. Without that helping hand, many applicants find their financial goals completely out of reach. It is a gamble that can change your immediate circumstances entirely.
As you survey your choices, avoid falling into the trap of focusing solely on your monthly installments. It is vital to grasp the entire landscape of your debt. You must calculate the speed of fund delivery alongside the long-term cost of borrowing. Digging deeper prevents nasty surprises down the road.
A tiny monthly bill might seem like a dream, but it often hides a 72-month commitment that causes interest costs to soar. Furthermore, companies marketing rapid payouts often bury heavy origination fees in the fine print. These hidden costs can make a quick loan far pricier than anything offered by a standard bank.
- FastLendGo
- OneMain Financial
- Upgrade
- Together Loans
- U.S. Bank
- MoneyLion
- MedLoan Finance
Our Methodology for Ranking Providers
Our team poured countless hours into auditing the current lending landscape, specifically targeting products that accept a co-signer. We wanted to peel back the curtain on how these institutions manage files involving two separate applicants. It was vital to determine if the co-signer’s obligations were stated plainly or if they were hidden deep within a maze of legal jargon.
We took a hard look at whether a lender demanded a joint application or if they permitted the second party to act merely as a guarantor. This distinction is the difference between a shared burden and a safety net. We prioritized firms that offered a seamless path forward rather than those that buried borrowers under a mountain of redundant paperwork.
Honesty acted as our North Star throughout this investigation. We hunted for lenders offering rapid responses, legible interest rates, and diverse borrowing limits. We also measured the “friction” of the digital journey. We weighed factors like the volume of required uploads, the simplicity of electronic signatures, and how clearly the Annual Percentage Rate (APR) was communicated.
| Company | Borrowing Limits | Rate Details/Terms | Payout Speed | Credit Profile |
|---|---|---|---|---|
| FastLendGo | $500 – $5,000+ | check website | check website | Poor to Excellent Credit |
| OneMain Financial | $1,500 – $30,000 | Starting at 11.99% APR | Within 60 minutes | Friendly to Low Credit |
| Upgrade | Maximum $50,000 | Fixed-rate options | Rapid disbursement | Improving Credit Scores |
| Together Loans | Up to $10,000 | 24 to 60 months | 1-day turnaround | Reliability/Low Credit |
| U.S. Bank | check website | check website | check website | Traditional Banking |
| MoneyLion | Maximum $100,000 | check website | Quickly available | Score Enhancement |
| MedLoan Finance | $500 – $100,000 | 0% Interest for 12-18 Months | check website | Healthcare Focused |
Leading Co-signer Loan Providers for 2026
1. FastLendGo
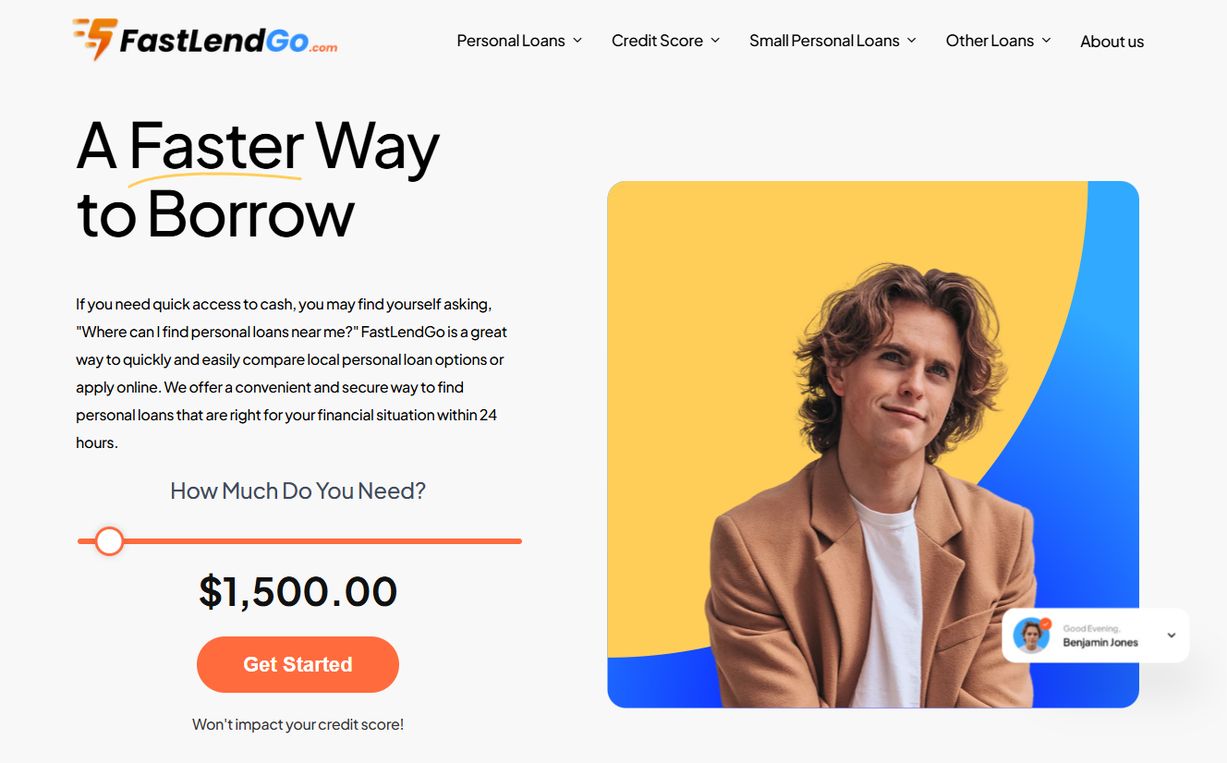
FastLendGo serves as a vital bridge for individuals chasing quick liquidity without facing endless red tape. Whether you are staring down a $500 emergency repair or seeking substantial capital for a life pivot, they have you covered. Their criteria are far more forgiving than a traditional mortgage department’s rigid standards.
This makes them a dream come true for freelancers or anyone living paycheck to paycheck with irregular income. (fastlendgo.com) If your credit history is somewhat “thin,” you might feel like a ghost in the eyes of major banks. Traditional scoring models often miss the mark when you haven’t cycled much credit through your accounts.
They offer tailored pathways for high-income earners and those with less-than-stellar credit scores alike. By bringing a co-signer to the table, you can effectively use their established history to anchor your own unproven financial stability. It is a clever way to unlock doors that might otherwise remain shut.
Pros:
- Starting amounts at $500 are ideal for minor financial hiccups.
- Funding can cover specific costs like car repairs or dental care.
- A variety of structures exist to suit diverse credit profiles.
Cons:
- The specialized focus means they might fall short for general debt restructuring.
2. OneMain Financial
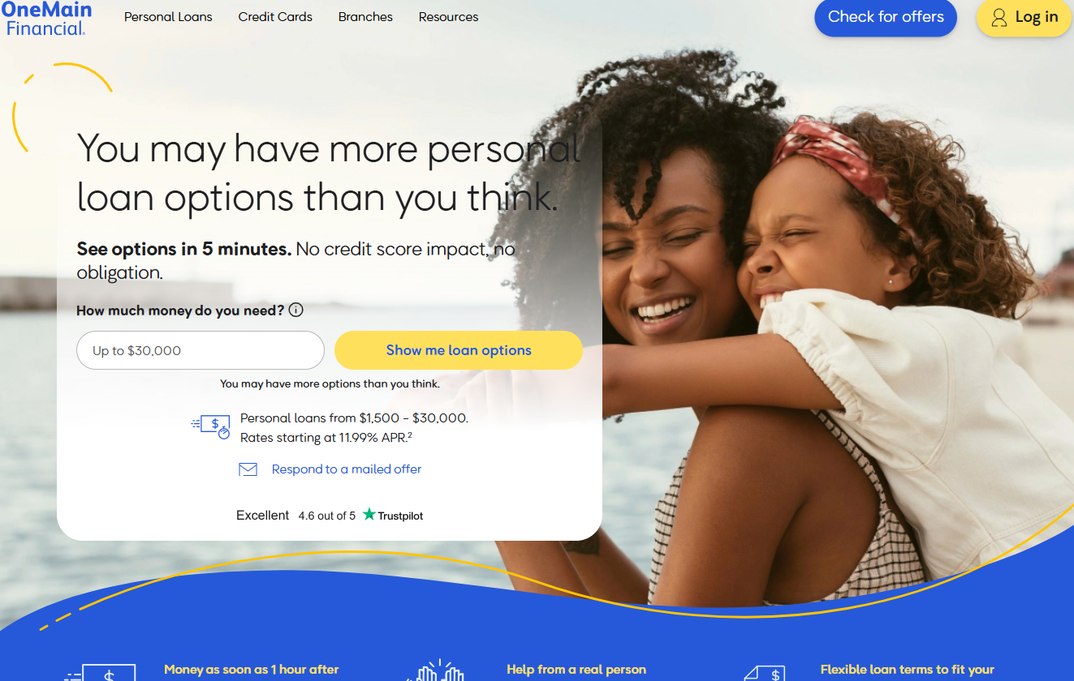
For those who find digital apps cold and impersonal, OneMain Financial offers a human touch. They maintain a massive physical presence with over 1,300 local branches. This allows you to walk through a door and speak face-to-face with a professional rather than shouting into the digital void.
Sitting down with a loan officer can provide a level of confidence that an algorithm simply cannot replicate. They move at the speed of light, sometimes delivering funds just sixty minutes after the ink dries. This efficiency is a godsend when time is of the essence.
Their joint loan structures are particularly intuitive, making it easy for family members or partners to share the burden. It removes the “what if” anxiety often associated with adding a co-signer to a contract. It is a seamless way to tackle finances together.
Pros:
- Funding can arrive in as little as one hour.
- An extensive branch network provides easy access to in-person support.
- Joint loans from $1,500 up to $30,000 simplify the co-signer process.
Cons:
- Lower credit scores may lead to steep interest rates over the loan term.
3. Upgrade
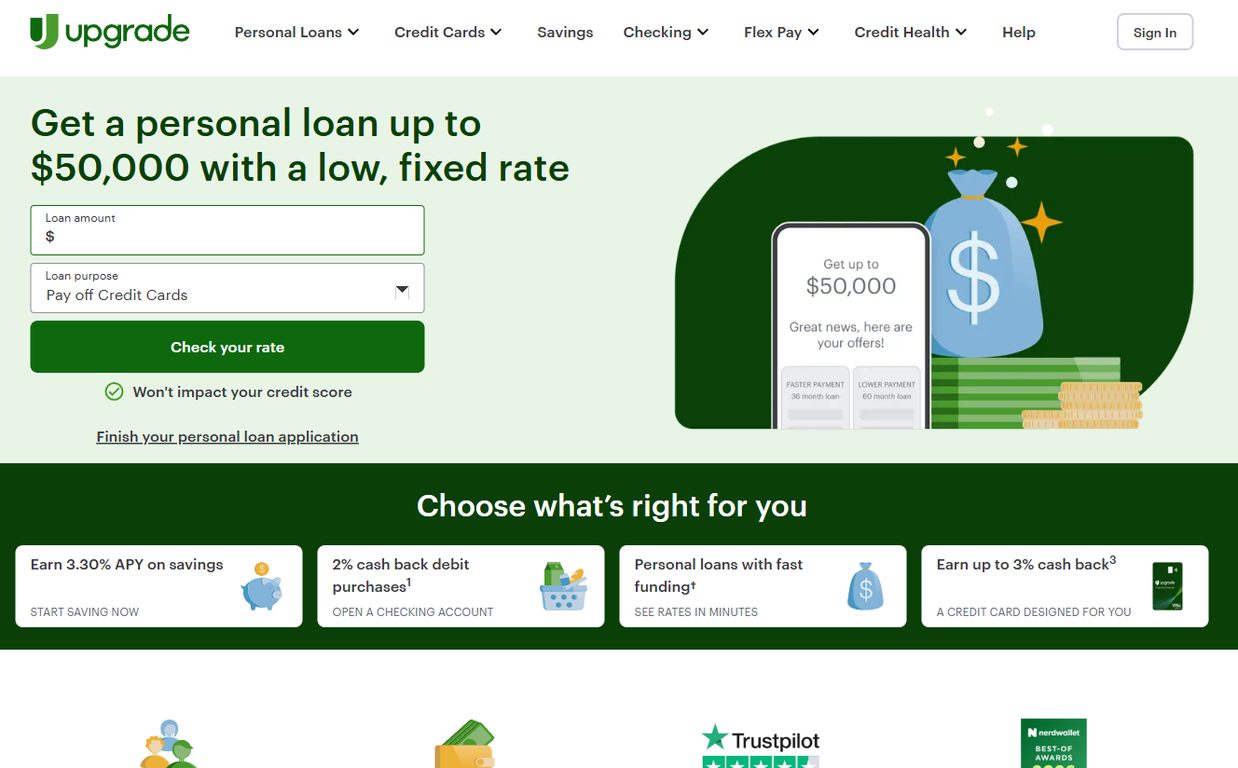
Upgrade takes a holistic view of your financial journey rather than just looking at a snapshot. They aim to be a comprehensive toolkit for your wallet, offering everything from savings accounts to credit cards. Their digital interface is incredibly intuitive and user-friendly.
The platform allows you to simulate different repayment scenarios before you ever commit to a contract. If you are looking to roll your debts into a single payment or fund a major purchase, the application process is remarkably smooth. It’s a friction-free experience for the modern borrower.
One standout feature is their “soft pull” credit inquiry. You can scout your potential APR and monthly obligations without leaving a dent in your credit score. This makes shopping for the best deal a stress-free endeavor.
Pros:
- Rate inquiries do not negatively impact your credit score.
- Funds are versatile, applicable to everything from debt to home upkeep.
- Select products offer the benefit of cash back rewards.
Cons:
- The wide array of products might feel overwhelming if you seek a single solution.
4. Together Loans
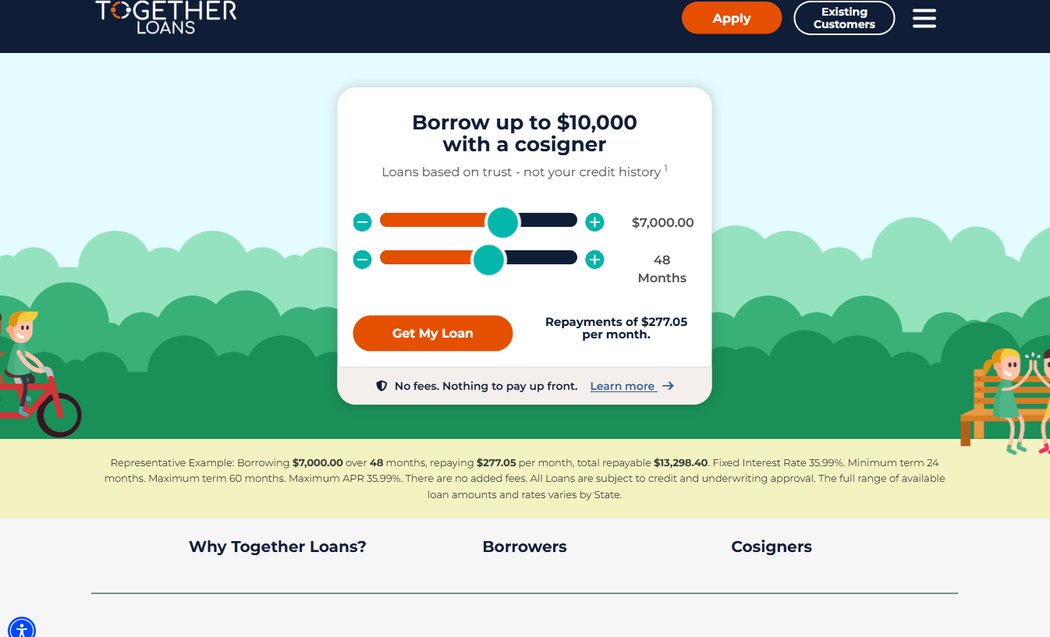
Together Loans operates on a philosophy of trust, looking past the cold numbers of a digital score. This approach is a game-changer for anyone with a solid co-signer but a checkered credit history. They understand that life is messy and unpredictable.
A sudden job loss or a single medical emergency can derail a credit score overnight. These lenders look at the human narrative behind the data points. They specialize in loans reaching up to $10,000, providing a lifeline when it is needed most.
With approvals often arriving within 24 hours, they are built for speed and urgency. Adding a co-signer here can act as a powerful lever to secure significantly better interest rates. It is about finding a way forward despite past setbacks.
Pros:
- They emphasize personal circumstances over rigid, automated math.
- The 24-hour approval turnaround is ideal for emergencies.
- No upfront fees mean you receive the full amount requested.
Cons:
- Interest rates can be somewhat high, so reading the fine print is vital.
5. U.S. Bank
If you find comfort in the shadows of a massive, established institution, U.S. Bank is a rock-solid choice. For those who are already part of their ecosystem, the benefits are clear. Having an existing relationship can make the verification process move like lightning.
Since they already have your cash flow data on hand, they can verify your stability quite quickly. While they might lack the breakneck speed of a trendy fintech startup, they offer a depth of infrastructure that is hard to beat. They are the “old guard” of the banking world.
Their services span from basic checking accounts to complex wealth management. For major milestones like a wedding, the sheer stability of a big bank provides a sense of peace of mind. You are banking with a giant that isn’t going anywhere.
Pros:
- Provides a high degree of financial stability and consumer protection.
- A comprehensive suite of financial services is available in one place.
- Management is seamless for existing customers of the bank.
Cons:
- Loan eligibility requirements can be more stringent than niche lenders.
6. MoneyLion
MoneyLion is clearly designed for the smartphone generation. Their application is more than a banking tool; it functions like a digital financial assistant. It is built to help you track daily spending while simultaneously working to polish your credit profile.
They offer substantial loan limits, reaching as high as $100,000. This is enough capital to fund major life shifts, such as returning to university. Their focus on credit education helps you build the muscle needed to eventually stand alone.
The ultimate goal is to move from needing a co-signer to being entirely self-sufficient. With an easy-to-navigate mobile interface, managing your financial future is literally in the palm of your hand. It is modern finance at its most accessible.
Pros:
- Extremely high loan ceilings for significant financial projects.
- The app provides various tools to boost credit awareness.
- The mobile experience is highly intuitive and sleek.
Cons:
- Rapid cash access features may carry additional service fees.
7. MedLoan Finance
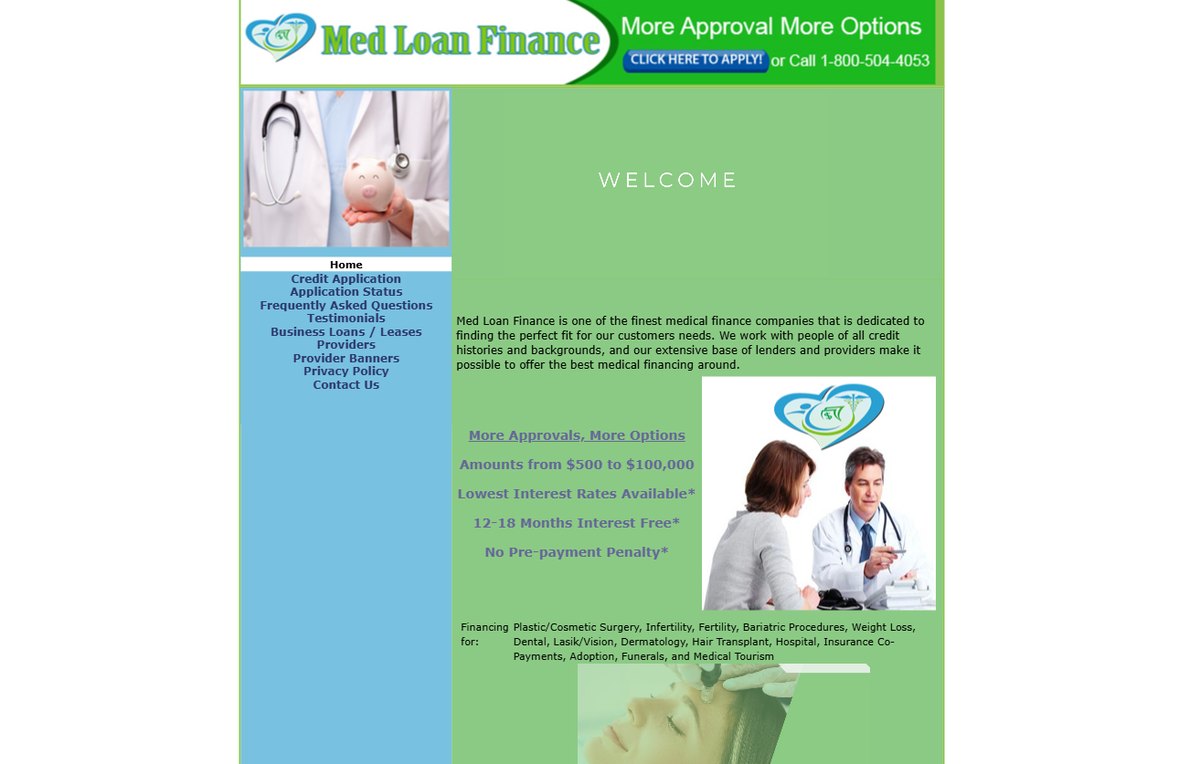
MedLoan Finance has a laser-focused mission: tackling medical debt. If you are looking to fund a LASIK procedure, dental work, or a major surgery, these are your people. They understand the specific rhythms of the healthcare industry in a way general lenders do not.
They offer diverse loan amounts and even provide interest-free windows for certain timeframes. This can be a massive advantage for those facing upcoming surgical costs. It is a specialized tool for a very specific job.
Using a healthcare specialist can often be much more economical than taking a standard personal loan. Instead of fighting high interest rates, you can find terms tailored to your medical needs. It is about making healthcare more manageable.
- Tailored specifically for elective and dental medical procedures.
- 12-to-18-month interest-free windows can provide significant savings.
- They facilitate large medical expenses up to $100,000.
- Funds are strictly limited to medical-related expenditures.
The Real Weight of Signing for Someone Else
Stepping up to co-sign a loan is no small feat. When a loved one asks for your signature, they aren’t merely offering a character reference. They are essentially tethering their financial future to yours. It is a binding legal promise to settle the entire debt if your payments fall through.
If you slip up and miss a deadline, the bank won’t just call your phone. They will come knocking on the co-signer’s door for the total balance. This includes the principal, any accrued interest, and those pesky late penalties. It turns a simple favor into a potential legal nightmare.
Such lapses can trigger aggressive collection tactics, including lawsuits or even wage garnishment. Beyond the courtroom, the damage to their credit score can be catastrophic. It’s like throwing a grenade into their financial stability, making it difficult for them to bounce back quickly.
This obligation also lingers on their credit report like a shadow. Even if you are incredibly disciplined with your payments, the sheer scale of the loan matters. It affects their debt-to-income ratio in ways that many people overlook until it is too late.
When they eventually go to apply for a mortgage or a new vehicle, lenders will look closely. That massive debt appears as a looming liability that might hinder their ability to manage their own finances. You are essentially asking them to carry your weight on their shoulders.
Setting the Stage for Co-signer Approval
Securing a loan requires more than just sheer luck; it demands a strategic approach to ensure a “yes” from the bank. You shouldn’t just walk into a branch with a handful of identification papers and hope for the best. Instead, you need a bulletproof strategy regarding your repayment timeline.
Think of this stage as the foundation of a building. If the groundwork is shaky, the whole structure might collapse under financial pressure. Before you even touch a digital application, we recommend checking these vital items off your to-do list to avoid unnecessary headaches later on.
It is easy to feel overwhelmed, but preparation is the antidote to anxiety. By organizing your financial life ahead of time, you transform a stressful hurdle into a smooth, professional transaction. Let’s dive into the specific prerequisites that will make or break your chances.
- Design a Repayment Roadmap: Determine the precise dates and methods for every installment. It is wise to build a financial cushion into your monthly budget to handle unexpected emergencies or lean months.
- Evaluate Your Partner’s Credit History: Most financial institutions look for a credit score sitting between 670 and 700 for the co-signer. If their rating is underwhelming, you might be chasing a ghost.
- Compile Your Documentation: Gather everything from W-2 forms to recent pay stubs and residential proof. Keeping these essentials in one tidy digital or physical file can shave days off your approval wait time.
- Review the Fine Print Collectively: Never treat the legal documents as mere formalities. Sit down with your co-signer to thoroughly discuss the specific consequences of a single missed payment.
Managing the Co-signer Relationship
Before you approach a friend or relative, sit them down for a heart-to-heart. They must fully grasp that this isn’t just a signature on a piece of paper; it is a heavy legal obligation. If things go south—perhaps you face an unexpected layoff—they are on the hook for every cent.
It is a bitter pill to swallow, but financial mishaps can tear a family apart. Their creditworthiness is directly tied to your actions. If you miss a single payment, their credit score will plummet right alongside yours, potentially causing long-term damage to their financial health.
Think of this arrangement as a serious partnership rather than a mere administrative formality. Banks view these individuals as primary guarantors, not just secondary observers. They are essentially putting their own financial reputation on the line to back your loan application.
If the person you choose has a credit history that isn’t significantly stronger than your own, you might hit a brick wall. The lender might still reject the application or decide to slap a much higher interest rate on the loan. In such scenarios, the co-signer fails to provide the financial cushion you were hoping for.
Avoid the temptation to pad your loan amount simply because you have extra borrowing power. It is easy to get carried away, but interest compounds like a snowball rolling down a hill. What starts as a small sum can balloon into a mountain of debt that feels impossible to climb.
Your goal should be to secure more favorable terms, not to increase your debt burden. Use the co-signer to drive down your interest rates and make the loan more affordable. Don’t let the extra capacity lead you into a trap of overspending that you cannot escape.