Fastest Bad Credit Loans New York: Compare Top Rated Lenders Today
Last updated: 2026-10-17
Navigating your finances in the Big Apple can feel like dodging taxis in a torrential downpour. When your credit rating isn’t looking its best, searching for a bank that won’t slam the door in your face feels like chasing ghosts. Life moves fast here, and the grind is constant.
Between the skyrocketing price of an apartment in the five boroughs and a sudden medical emergency, cash often disappears when you need it most. Most residents find themselves scrambling for quick funds to keep their heads above water during those tight monthly cycles.
We created this resource for local residents facing sudden financial hurdles who need dependable alternatives to the shady lenders lurking on street corners. Nobody should be forced to pick between a roof over their head and getting stuck in a cycle of endless debt.
Finding the sweet spot between how fast you get paid and how much it costs you is the real key to survival. In a city that never sleeps, you need financial tools that actually work when the stakes are highest.
Choosing a provider involves looking much deeper than just the advertised percentage rate. You must balance the velocity of your funds against the total price of the borrowing. If your landlord demands cash tomorrow, a low rate means nothing if the bank takes a week to approve you.
On the flip side, a loan that hits your account instantly might carry interest rates so steep they feel like a trap. We dissect how these companies approach your credit history and how quickly they wire funds to your personal accounts.
Our team also digs into whether their fine print is crystal clear or stuffed with sneaky clauses. We measure these services by how helpful they are to people living in a fast-paced metropolis. We want you to see the reality behind the shiny advertisements.
- SkyOne
- United Finance
- JetzLoan
- Experian
- GreendayOnline
Our Selection Criteria for New York Borrowers
Our team prioritized finding solutions for people navigating the tricky waters of low credit scores. We specifically investigated whether companies initiate a hard inquiry during the first stage of the application. A sudden dip in your rating can be a real kick in the teeth when you are already struggling.
In a fast-paced environment like New York, your credit utilization can shift in the blink of an eye. Therefore, we favored providers that utilize “soft pulls” for initial price quotes. This approach serves as a vital safety net for your financial standing.
When life throws a curveball, like an unexpected car breakdown, you need cash yesterday. We focused heavily on how quickly a lender can actually deposit funds into your bank account. Waiting weeks for help is simply not an option for someone facing a utility shut-off notice.
We sought out lenders that offer lightning-fast speed without hiding their rules behind a veil of mystery. Transparency is our North Star. If a company won’t tell you exactly how they operate, they don’t belong in our curated list.
The scale of the financing was another major pillar of our vetting process. Some folks just need $500 to fix a leaky faucet or a broken appliance. Others might need $25,000 to wipe out high-interest credit card debt and finally breathe again.
We made sure our selections covered a broad spectrum of financial needs. It’s about finding the right tool for the specific job at hand. We also demanded total clarity regarding how you pay the money back.
We went hunting for any signs of predatory behavior, like those sneaky origination fees. If a lender tries to bury the total cost of borrowing in tiny, illegible fine print, they are out. We refuse to promote anything that feels like a debt trap.
Every provider was checked for transparency regarding the total cost of credit over the duration of the loan. We want to ensure you know exactly what you are signing up for. No hidden surprises were tolerated in our final review.
| Provider | Available Capital | Processing Speed | Eligibility Details |
|---|---|---|---|
| SkyOne | $500 – $50,000 | visit website | Personal Loans available |
| United Finance | visit website | visit website | Installment loans available |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No hard credit pull |
| Experian | $2,000 – $50,000 | Same-day funding available | visit website |
| GreendayOnline | $100 – $5,000 | As soon as the same day | Bad credit welcome |
Top Rated Lending Providers
1. SkyOne
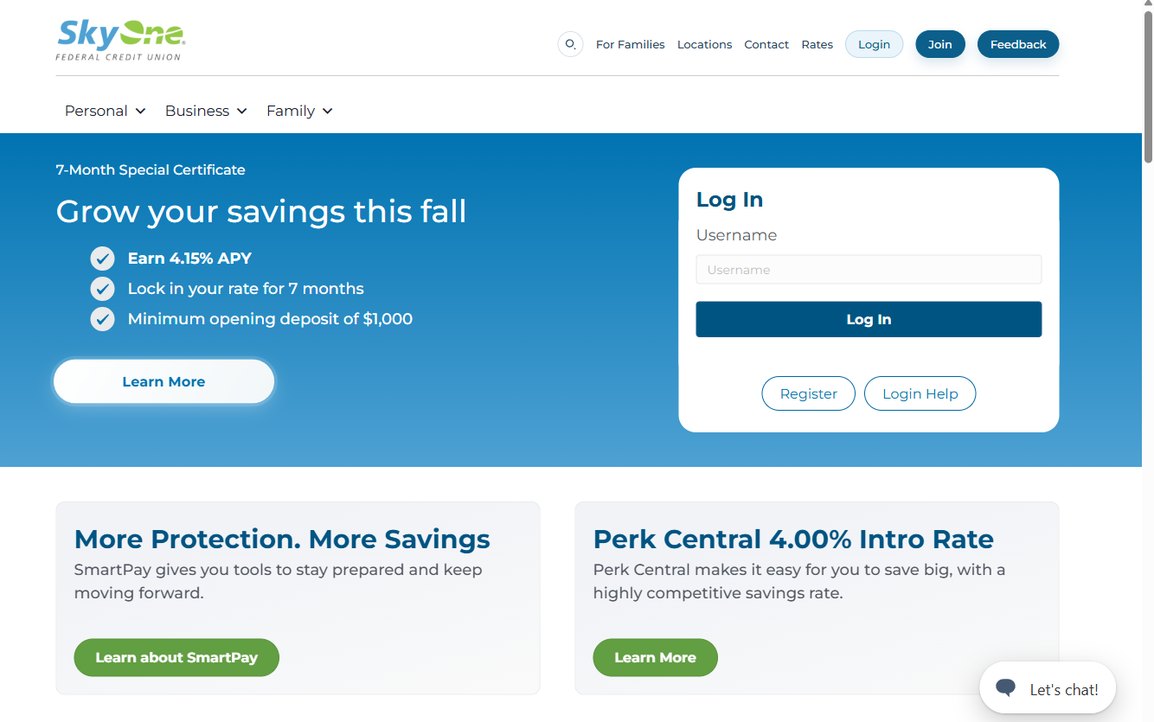
As a federal credit union, SkyOne approaches your personal finances with a distinctly human touch. They don’t rely on the cold, rigid math that causes most commercial banks to shut their doors on you instantly. Instead, because the members actually own the institution, the lending process feels much more personal and inclusive.
You can secure personal loans with interest rates beginning at a competitive 13.99% APR. This is a breath of fresh air for anyone tired of the sky-high rates found on standard credit cards. Whether you are tackling a pile of debt or planning a major renovation for your home, their limits go as high as $50,000.
Choosing this route means opting for a community-centric partner rather than a giant, faceless corporation. The relationship feels more like a collaboration than a transaction. It is a fantastic way to build a foundation for lasting stability rather than just patching a hole in your pocket.
Pros:
- Personal loan rates starting at a low 13.99% APR.
- Large borrowing capacity reaching up to $50,000.
- Variety of options including lines of credit.
Cons:
- You may need to meet specific membership criteria.
2. United Finance
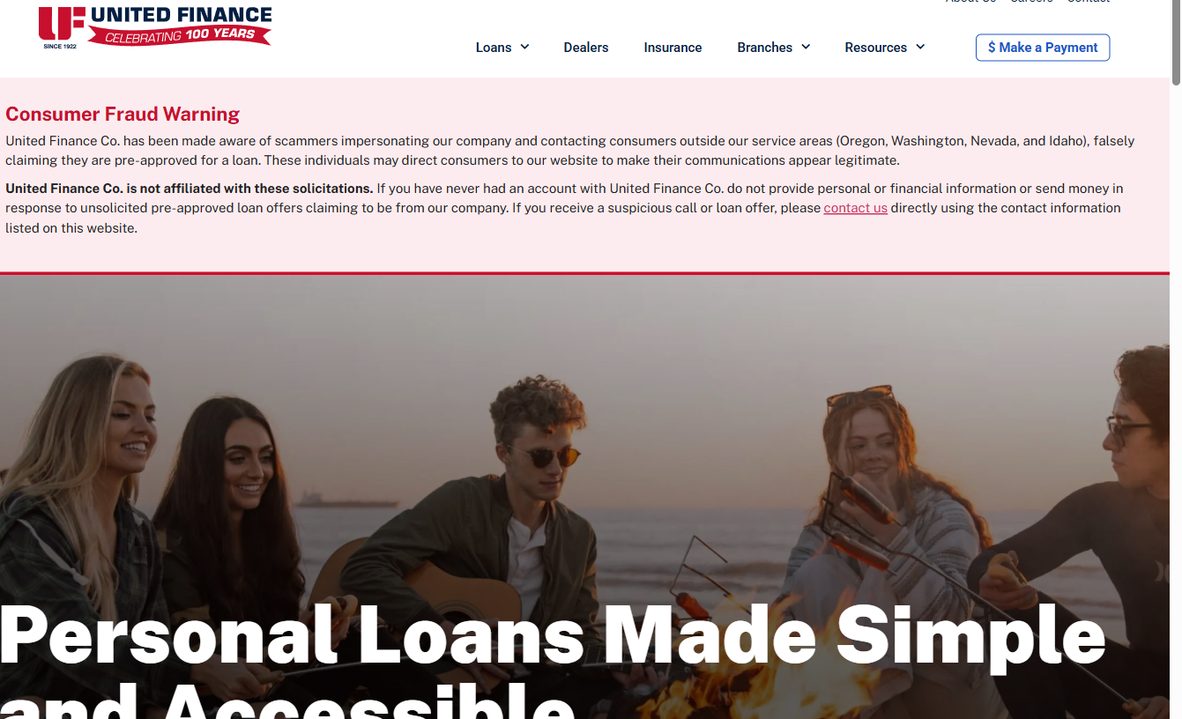
Since 1922, United Finance has been a cornerstone of the lending world, proving they can survive any storm. They specialize in installment loans, which offer a much more stable way to manage your money than predatory payday options. You simply pay back fixed amounts of principal and interest over a set schedule.
This method is a total game-changer for your monthly budgeting. It stands in stark contrast to the nightmare of revolving debt, where interest piles up so fast that you barely scratch the surface of what you owe. They are also highly vigilant about security, frequently warning people about scammers trying to steal their identity.
With over a century of history behind them, this firm offers a level of institutional strength that new fintech apps simply can’t match. If you want a tried-and-true way to handle your money with clear, predictable monthly costs, they are a rock-solid choice.
Pros:
- A long-standing reputation built since 1922.
- Provides structured installment loans instead of high-risk cycles.
- Prioritizes protecting customers from fraudulent activity.
Cons:
- Operations are restricted to certain states like Nevada and Oregon.
3. JetzLoan
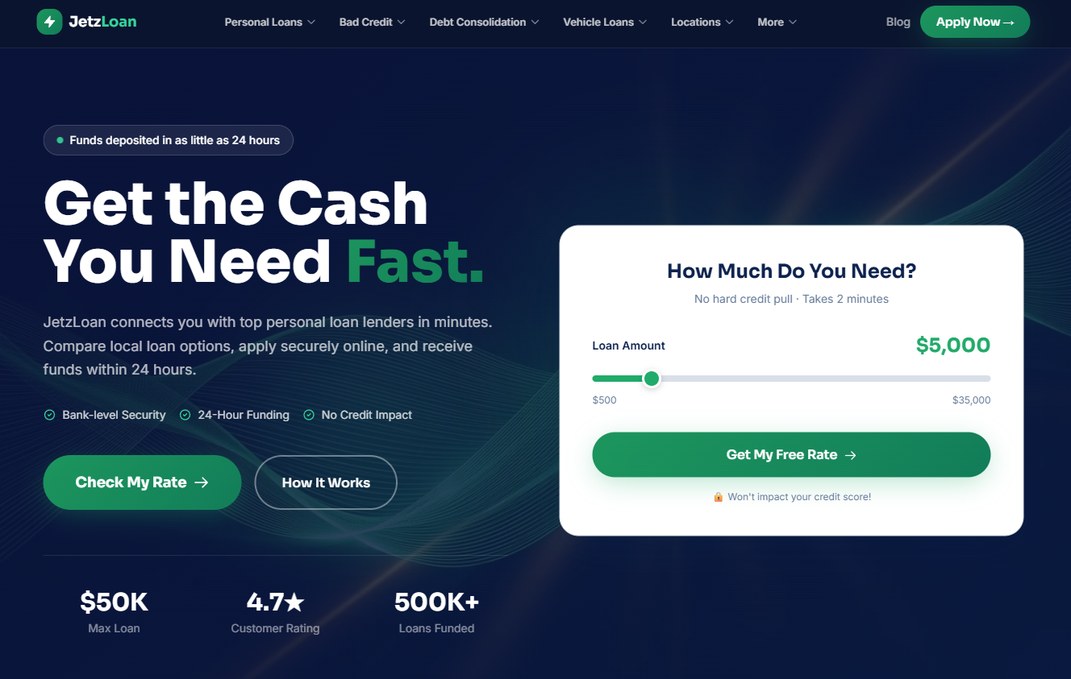
When you find yourself in a real bind and need cash right this second, JetzLoan is the speed demon of the industry. They specialize in matching you with top-tier lenders in the blink of an eye. Best of all, you can see your potential rate without any hard credit pull hitting your file.
This ability to pre-qualify is a total lifesaver. Many people worry that searching for a loan will instantly tank their credit score, but that isn’t the case here. You can shop around to find the best deal without any immediate penalty to your rating. The entire setup takes about two minutes of your time.
Forget the mountain of paperwork you usually see at a local bank branch. This digital platform is built for the modern, busy life—perfect for someone checking options on a subway ride. With cash often landing in your bank account within 24 hours, it is ideal for urgent needs.
Pros:
- Perform initial rate checks without a hard credit pull.
- Lightning-fast funding, sometimes in just a day.
- An incredibly simple, two-minute application.
Cons:
- The maximum amount you can borrow is $35,000.
4. Experian
Everyone knows Experian as the giant of credit monitoring, and their lending expertise is no different. They truly understand the DNA of credit scoring better than almost anyone else on the planet. They provide personal loans from $2,000 all the way up to $50,000, with repayment periods between 24 and 72 months.
Choosing a longer timeframe can make your monthly bills much easier to handle. However, keep in mind that a longer term means you will end up paying more in interest over time. They are a great resource for those looking to actively improve their financial health using credit-boosting tools.
This creates a brilliant cycle of improvement. You use a loan to clear a hurdle, then use Experian’s tools to ensure your score is higher when you eventually want to buy a car or a house. It turns a moment of struggle into a long-term victory for your wallet.
Pros:
- Some loan types qualify for same-day funding.
- Flexible repayment windows up to 72 months.
- Includes tools designed to improve your credit score.
Cons:
- Higher scores or loan approvals are never a certainty.
5. GreendayOnline
GreendayOnline is the go-to for those needing a quick boost to cover a sudden expense. They focus on smaller installment loans ranging from $100 up to $5,000. Think of this as a micro-loan solution for those little life emergencies that pop up when you least expect them.
While this isn’t the tool for wiping out massive debts, it works wonders for bridging the gap until your next paycheck arrives. The entire process happens online, making it incredibly simple for busy people on the move. They are very welcoming to those with poor credit history.
If you have been burned by the banking system before, this is a fantastic safety net. It is a straightforward, no-nonsense way to get a little extra help to make sure you make it through the month without stress.
Pros:
- Very accessible with minimum loans starting at $100.
- Rapid approval with the potential for same-day cash.
- Built with a focus on applicants with poor credit.
Cons:
- Loan ceilings are quite low compared to other players.
Navigating Your Loan Options: A Practical Strategy
Having several different proposals sitting in front of you can feel like staring into a whirlwind of dates and interest percentages. It is easy to lose the forest for the trees when math starts to get complicated. To ensure you pick the best deal for your specific situation, try following this structured method.
Don’t let the numbers dance around your head. Instead of just glancing at the interest rate, you must scrutinize the Annual Percentage Rate, or APR. While interest covers the cost of the principal, the APR pulls in those sneaky hidden extras like processing charges or origination costs. It is your most honest tool for comparing true costs.
Think of the APR as the real price tag of your debt. If you only look at the base rate, you might end up paying much more than you expected when those administrative fees start piling up on top of the interest.
Before you even dive into the fine print, sit down with your bank statements and figure out your “Maximum Monthly Outflow.” It is like setting a speed limit for your finances. If your budget only allows for an extra $150 in monthly spending, do not sign up for a $200 obligation.
Even if a lender promises a dirt-cheap interest rate, a high monthly payment can still sink your ship. It is better to walk away from a deal than to find yourself drowning in payments that you simply cannot sustain every month.
You should also hunt down any mention of prepayment penalties hidden in the contract. Some banks will actually punish you for being responsible and trying to settle your debt ahead of schedule. They want that interest, after all.
If you are expecting a sudden windfall, such as a yearly work bonus or a tax refund, you will want the freedom to wipe out that debt instantly. Make sure your chosen lender won’t slap you with extra fees just for paying them back early.
Finally, get a clear answer regarding the funding timeline. If you are facing a sudden crisis, you need to know exactly when that cash will be sitting in your bank account. Do not settle for a vague “approval” status.
There is a massive gap between being “approved” and actually having the money available to spend. Ask the lender directly, “When exactly will these funds be cleared and ready for my use?” This distinction could be the difference between a lifesaver and a headache.
Navigating the Treacherous Waters of New York Credit Offers
Walking through the concrete jungle of Manhattan’s financial district, you might feel like you’re being chased by a shark. The sheer volume of credit options available in NYC can make your head spin, creating a perfect storm for predatory sharks to strike. You must stay vigilant against high-pressure salesmanship.
If a representative starts barking about “last chances” or claims you will face “immediate rejection” if you don’t sign right this second, run for the hills. These frantic, aggressive tactics are major red flags. Genuine financial institutions operate with a calm, professional demeanor.
Reliable companies understand that a loan is a massive commitment for any household. They will never bully you into a signature. They will graciously permit you the necessary breathing room to scrutinize every single clause in the fine print before you commit your hard-earned cash.
A dangerous habit many New Yorkers fall into is something experts call “loan stacking.” It is a slippery slope that feels like a temporary lifeline but acts like an anchor. It happens when you grab a fresh, expensive loan just to settle an old, high-interest debt.
You might feel like you’re just shifting the furniture around in a house that is on fire. In reality, you are simply moving the weight of your debt from one corner to another. Meanwhile, those mounting interest rates are silently devouring your future income.
If you find yourself in a cycle where a second loan is required to cover the first, stop in your tracks. It is a sign that you are drowning in a sea of interest. At that point, seeking professional debt counseling is much wiser than grabbing more credit.
Don’t let a flashy website fool you into thinking a lender is the real deal. In our modern, digital-first world, a slick user interface is merely the bare minimum requirement for any business. A pretty layout does not equal financial stability or honesty.
Always perform your due diligence by verifying that the company is legally authorized to operate within New York State. A legitimate entity will provide a verifiable physical office location and a history of transparent terms. Don’t just take their word for it.
Check for actual, verifiable customer feedback from real people in your community. A company’s true character is revealed through its long-term reputation and how it treats people when things go wrong. Never skip this step before clicking that final “accept” button.
Making Smart Choices with Your Borrowing Options
Before you pick up a pen to sign any contracts, stop and catch your breath. It is incredibly tempting to dive headfirst into a fast approval when you are in a pinch. However, you really need to scrutinize the actual price of the capital you are acquiring.
Make sure to inquire about any hidden origination costs or penalties for paying the debt off early. These sneaky additions can make a loan much pricier than the initial offer implies. For instance, if you borrow $1,000 but lose $100 immediately to service fees, that rate is much higher than it looks at first glance.
Don’t let yourself get caught in the trap of stacking several tiny loans from various lenders just to pay off a single large bill. It is a slippery slope that often leads to a financial rabbit hole that is incredibly hard to climb out of once you fall.
Instead, aim to bundle your various financial obligations into a single, steady monthly installment whenever it makes sense for you. This strategy helps keep your monthly budget predictable and keeps your anxiety at bay. Trying to track five different interest rates and multiple deadlines every month is a nightmare for anyone’s mental clarity.
Leave a Reply