Top Rated Plastic Surgery Loans for Bad Credit: Get Funded Now
Last updated: 2026-10-16
Stepping into a consultation room ought to be a milestone toward self-confidence, rather than a plunge into a sea of monetary panic. Too often, patients gaze at a desired aesthetic procedure while their credit scores linger at rock bottom. This disconnect makes achieving personal goals feel like chasing a mirage in a desert.
It is a crushing weight to bear when your body’s aspirations clash so violently with your bank account’s limitations. The mental strain of accumulating debt frequently eclipses the joy of a physical makeover. This creates a feedback loop of stress that keeps many people from obtaining necessary medical attention.
“Can I actually afford this?” is a question that rings loudly in many minds. It is remarkably difficult to concentrate on post-operative recovery when your brain is stuck on the logistics of paying the surgeon. You shouldn’t have to choose between your peace of mind and your physical transformation.
Securing funding for cosmetic enhancements involves looking far beyond the glossy pamphlets in a waiting room. You must find a financier that respects the sensitivity of medical billing, particularly when your fiscal history is a bit messy. Large national banks typically maintain strict rules that reject anyone with high debt or a single missed payment on their record.
The following selection showcases the premier choices for 2026 for individuals navigating the choppy waters of medical debt and reconstruction.
- JetzLoan
- Cherry
- CareCredit
- United Credit
- Acorn Finance
- MedLoan Finance
Our Methodology for Comparing Medical Lending
Searching for a way to pay for surgery becomes a real headache when your credit score isn’t exactly shining. Finding a lender is a breeze if you have a pristine history, but for most people, the real struggle is finding a company that won’t instantly turn you away. We set out to hunt down lenders that actually say yes.
Our team prioritized finding institutions that maintain high approval percentages. We also looked for clarity in every contract to ensure no one gets blindsided by sneaky costs. It’s crucial to avoid those “gotcha” moments that can derail your aesthetic goals before you even step into the clinic.
A nasty surprise in the world of medical loans usually means an unannounced origination fee or a massive jump in interest rates once a teaser period vanishes. You definitely don’t want to discover a financing gap after you’ve already committed to a procedure and handed over a deposit that you can’t get back.
We also placed a huge emphasis on how quickly you can access your cash. Speed is everything when you are eager to begin your transformation. We looked for services that provide rapid answers so the journey from your first consultation to the actual recovery room stays incredibly seamless.
Checking your eligibility shouldn’t feel like a risk to your financial standing. Because of this, we scrutinized the “soft pull” capabilities of every option. We wanted to ensure our readers could browse different rates without hurting their credit scores in the process.
| Lending Company | Borrowing Limits | Processing Time | Credit Score Effect |
|---|---|---|---|
| JetzLoan | $500 – $35,000 | Within 24 hours | No hard inquiry |
| Cherry | See site | Right after approval | Soft check only |
| CareCredit | See site | Immediate results | Prequalify without impact |
| United Credit | See site | See site | See site |
| Acorn Finance | See site | See site | No impact on score |
| MedLoan Finance | $500 – $100,000 | See site | See site |
Decoding Your Loan Terms: Interest Rates and Repayment Structures
Before you sign on the dotted line with any lender, you must grasp the financial math behind your options. It is easy to get lost in the weeds when comparing different funding models. Most medical financing solutions split into two main camps: installment-based agreements and revolving credit lines.
Think of revolving credit, such as CareCredit, as a flexible safety net. It behaves much like a standard credit card where you have a set ceiling of funds. As you chip away at your debt, that available room opens back up for future use.
This flexibility is a godsend if you are undergoing continuous care, like a series of dermatological visits or orthodontic adjustments. However, you cannot treat it like a blank check. Without ironclad discipline, those interest rates will bite hard, causing your total debt to snowball out of control.
On the other hand, installment loans from companies like MedLoan Finance or JetzLoan work differently. They hand you a single, large sum of cash immediately. You then chip away at that total through set, monthly payments over a predetermined period.
For a major, one-and-done procedure—perhaps a tummy tuck or a rhinoplasty—this structure is often your best friend. It offers a predictable rhythm for your budget. You know exactly when the debt will vanish, which provides much-needed peace of mind during recovery.
When you are shopping around, do not let a small monthly payment fool your eyes. You must scrutinize the Annual Percentage Rate (APR) above all else. A tiny monthly bill might look like a bargain, but if it stretches across 60 months, you might end up paying twice the actual cost of your surgery just in interest.
Premier Lending Options for Your Procedure
1. JetzLoan
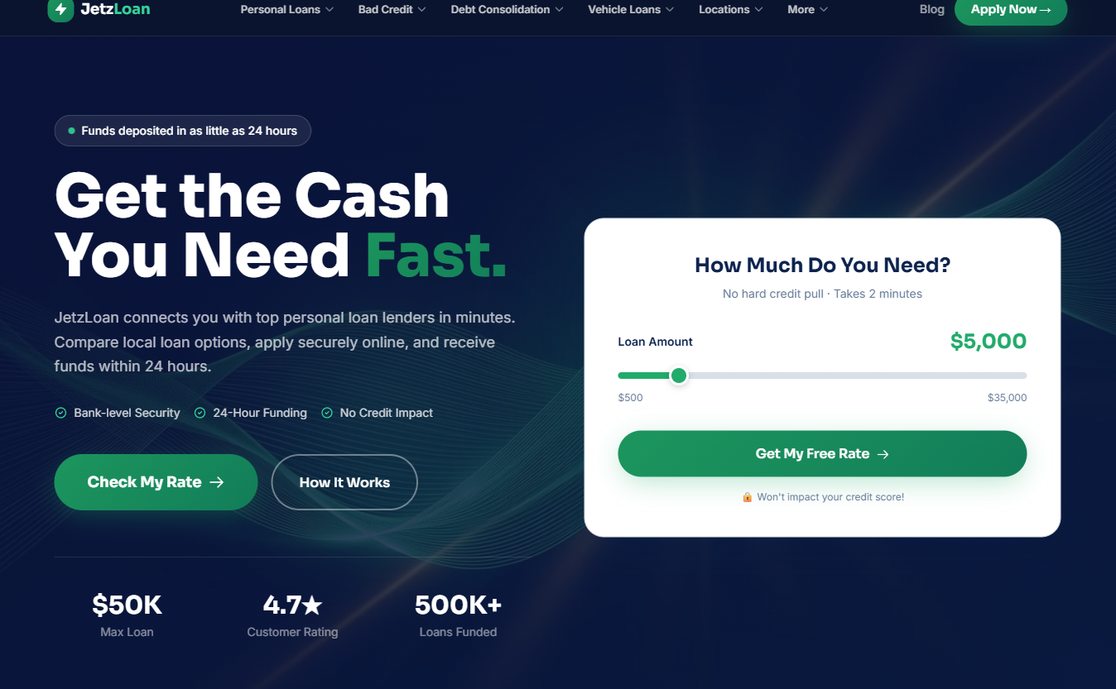
Think of JetzLoan as a rapid financial bridge for urgent healthcare needs. If you find yourself facing sudden dental emergencies or must undergo an immediate corrective procedure, this service aims to deposit funds into your bank account within a mere 24 hours. It is built for speed when timing is absolutely everything.
Navigating their platform is as easy as pie. You can investigate potential interest rates and repayment terms in just two minutes without worrying about your credit score. Because they utilize a “soft pull” mechanism, you can shop around freely without the fear of a hard inquiry dragging down your rating.
When you need to secure a significant sum—up to $35,000—without the red tape typically found at traditional banks, this is a powerhouse choice. It effectively cuts through the usual bureaucratic delays to get the job done efficiently.
- Pros: Lightning-fast fund disbursement, checking rates won’t hurt your credit, loans up to $35,000.
- Cons: The ceiling for borrowing might be lower than some niche medical-specific lenders.
2. Cherry
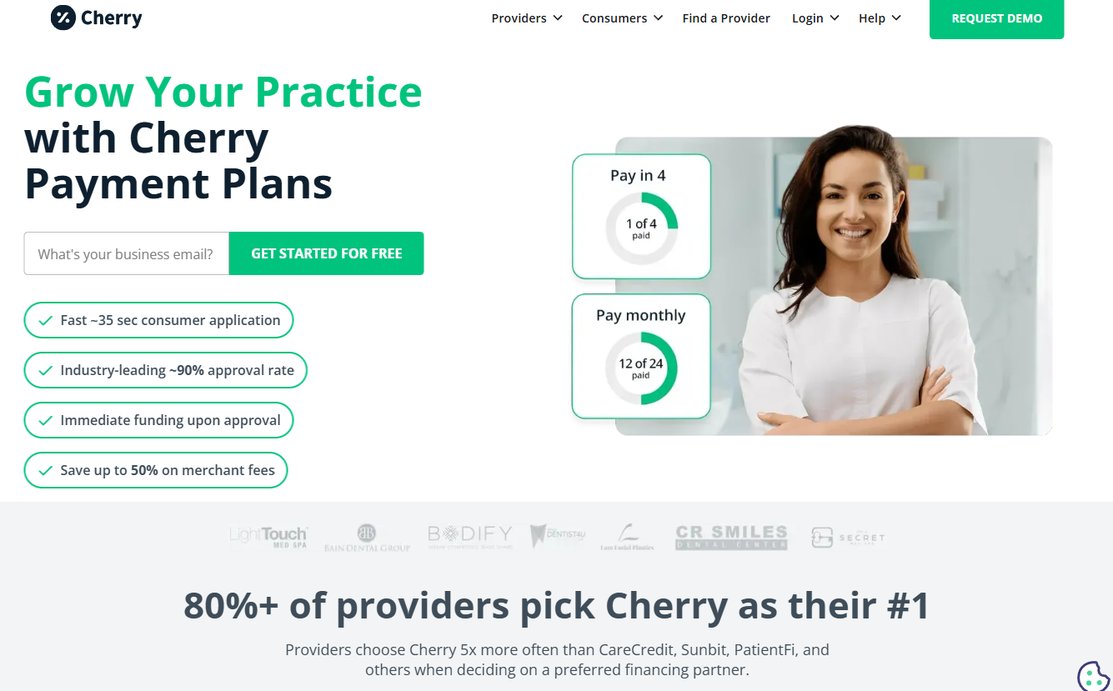
Cherry has carved out a massive presence in the healthcare industry, earning the trust of tens of thousands of different medical providers. It has become a top choice for patients who crave a “no fuss” transaction. The application is a breeze, often wrapping up in roughly 35 seconds.
This speed is a godsend for busy individuals who might be bouncing between multiple specialists in a single afternoon. Because they focus on high approval rates, many patients find that using Cherry significantly lessens the heavy weight of medical debt stress.
Essentially, it works like a specialized digital payment tool designed just for the medical world. It removes the awkwardness of discussing large sums of money in a clinical setting. By streamlining the checkout at the doctor’s office, it allows you to prioritize your health over your wallet.
- Pros: Extremely high approval success, instant decisions, incredibly quick application.
3. CareCredit
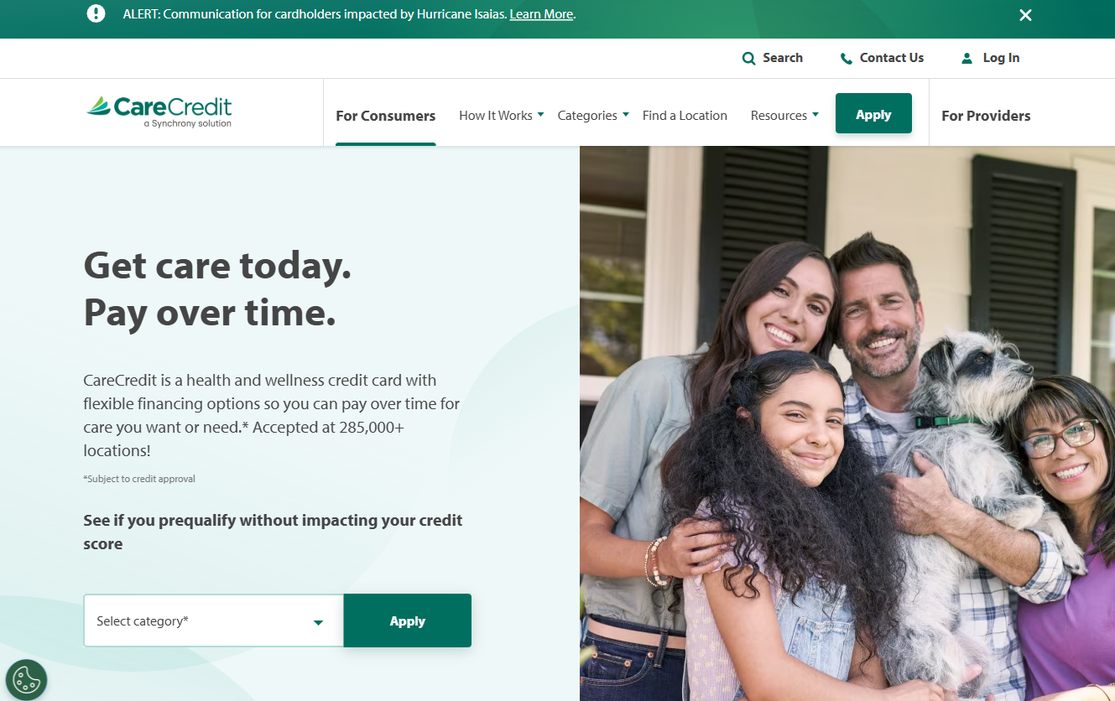
CareCredit is a household name that you will likely encounter at hundreds of thousands of various locations. Rather than a standard loan, it functions as a dedicated credit card for health and wellness. This versatility means you can use it for vision care, vet services, or even certain physical therapy sessions.
The real magic lies in the flexibility it offers. You can spread out your payments over time, which helps keep your monthly cash flow steady during your recovery period. Many people take advantage of “deferred interest” promotions, which offer interest-free windows of 6, 12, or 24 months.
However, tread carefully, as this can be a double-edged sword. If you miss the deadline to pay the full balance, interest is often backdated to the day you bought the service. This can lead to a massive, unexpected bill that catches you off guard completely.
4. United Credit
United Credit chooses to prioritize long-term relationships over simply closing a deal. By collaborating with a diverse array of lenders, they ensure that you have plenty of options on the table. This variety acts as a lifeline for people with different credit profiles, ranging from perfect to bad credit.
They don’t believe in a “one size fits all” philosophy; instead, they serve as a gateway to a vast market of specialized lenders. Their strategy focuses on your overall well-being, attempting to find a path forward even when a major bank might offer a flat “no.”
This approach is a lifesaver for the self-employed or those with non-traditional income streams who often struggle with standard bank requirements. If you want a lending experience that feels personal and looks at the whole person rather than just a number, this is a solid route.
5. Acorn Finance
Acorn Finance takes a slightly different angle by facilitating financing often used for large-scale medical or home improvement projects. They specialize in matching borrowers with personalized rates without the traditional sting of a credit score impact. It is an incredibly transparent way to shop for rates.
Think of them as an aggregator that pulls various specialized lenders onto a single, easy-to-use dashboard. Users frequently praise the platform for its speed, particularly the ability to apply via SMS or email. Even if your credit isn’t spotless, they strive to find a provider who fits your needs.
This makes them a fantastic resource for complex, multi-stage medical transformations. If you are looking at full facial reconstructions or extensive orthopedic surgeries involving several different specialists, they keep all your options in one convenient place.
6. MedLoan Finance
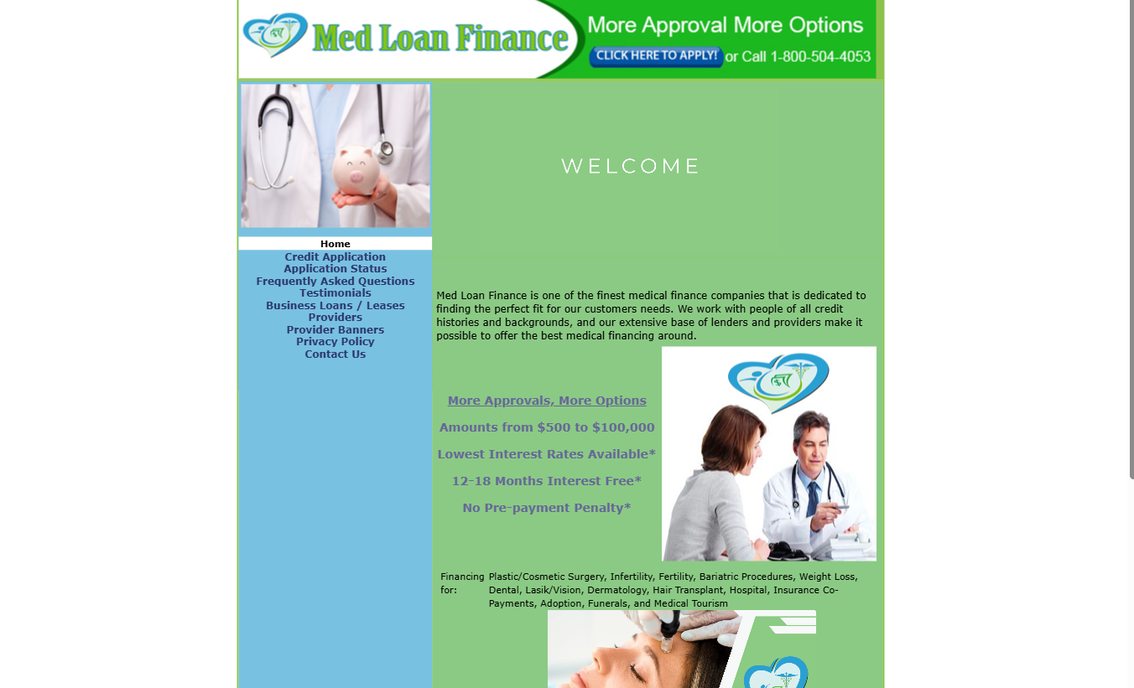
MedLoan Finance is a specialist in the medical field, focusing heavily on procedures like cosmetic, dental, or bariatric surgery. They are specifically built to accommodate people with all types of credit histories. They aim to provide the “best medical financing around” through unique medical underwriting.
With loan limits reaching up to $100,000, they are a serious contender for anyone embarking on a major aesthetic or reconstructive journey. Unlike general personal loans, they grasp the specific timelines associated with surgical recovery. They even offer specialized terms, including potential interest-free windows of 12 to 18 months.
This can be a massive cushion if you are unable to work for a short time while healing. Having that financial safety net is a huge relief when you need it most during your recovery phase.
Mapping Out Your Medical Financing
Selecting a lender involves much more than just hunting for the smallest interest rate. You are essentially looking for a financial ally that aligns with your unique medical requirements. Think of it like finding the right fit for a custom garment; it has to match your specific dimensions to work effectively.
If your goal is a minor enhancement that requires rapid turnaround, a swift provider like JetzLoan could be your lifesaver. On the other hand, significant reconstructive procedures often demand a much heavier lifting. In those instances, the substantial credit lines offered by MedLoan Finance may be essential for covering anesthesia, facility charges, and recovery care.
Don’t go ahead and pepper your credit report with multiple hard inquiries in a tight timeframe. This behavior can signal financial instability to potential lenders, causing your credit score to tumble. Every time a company conducts a “hard pull” to finalize your application, it leaves a visible mark on your record.
It is wise to prioritize “no impact” or “pre-qualification” features during your search. These tools act as a low-stakes rehearsal, allowing you to weigh your actual choices without any penalty to your score. You should construct a clear financial blueprint of your upcoming debt before you ever sign a contract.
As the old saying goes, it is better to weigh the cost of the capital before you actually spend it. This cautious approach prevents many common pitfalls that lead to long-term debt cycles.
Be extremely wary of the fine print tucked inside “interest-free” promotional offers. While many medical lenders promise a grace period, there is a catch waiting in the wings. If a single payment is missed or the balance remains after the period ends, retroactive interest can be applied.
This isn’t merely a minor slap on the wrist; depending on your total principal, it could amount to thousands of dollars. You should treat your medical debt with the same gravity one would afford a home mortgage. Staying organized and using autopay is your best defense against accidental late fees.
Leave a Reply