Best Places to Secure Bad Credit Loans Arkansas Online Today
Last updated: 2026-10-16
Navigating your finances in the Natural State can feel like trekking through dense brush if your credit rating isn’t hitting the mark. Many residents find themselves blindsided by unexpected medical expenses or mechanical failures without a financial cushion. When unpaid invoices begin to stack up, securing a trustworthy source of funding becomes an urgent necessity.
If you are residing in Little Rock, a malfunctioning air conditioner during a sweltering summer is more than a nuisance; it is a total catastrophe. The same applies to Northwest Arkansas, where a busted work truck can halt your livelihood instantly. The desperate scramble for immediate cash flow often feels like drowning when you are simply attempting to stay afloat.
As you hunt for a way out, prioritize clarity and rapid processing. It is vital to grasp the full expense of your debt before you sign anything. This curated selection identifies which companies provide the most effective routes for those striving to mend their damaged credit histories. One sneaky surcharge or an unclear interest percentage can transform a helpful loan into a heavy anchor.
- FastLendGo
- Balance Credit
- NetCredit
- Rent-A-Center
- Roadrunner Financial
- Best Egg
Our Selection Process for Arkansas Borrowers
Finding the right lender in Arkansas isn’t a walk in the park. We didn’t just glance at brochures; instead, we scrutinized every provider using benchmarks tailored to the local landscape. Our primary mission was determining whether an application would ding a borrower’s credit score or leave their bank account untouched during the initial check.
Time truly is of the essence when you are facing an emergency. When a utility company sends a disconnection warning, you can’t afford to wait a week for a bank transfer. A lender that drags their feet for five days might as well be useless. We looked for speed, specifically prioritizing those who offer same-day cash infusions.
We also scrutinized the volume of cash available and how strictly the terms were enforced. Small loans are great for a quick fix, but they won’t cover a $3,000 repair for a broken transmission. We sought out versatility to ensure our list caters to everyone from those needing a $500 cushion to anyone seeking $50,000 for debt management.
The core objective was to identify services that actually perform when life throws a curveball. We had no interest in companies that look shiny on a marketing landing page but vanish when you actually need the capital. Every single firm we included underwent rigorous vetting to confirm they deliver on their promises in the trenches of real-life financial struggle.
| Provider | Maximum Borrowing Limit | Transfer Velocity | Credit Standing Needs |
|---|---|---|---|
| FastLendGo | See site | See site | Bad/Fair/Good |
| Balance Credit | $4,000 | Next business day | Inclusive consideration |
| NetCredit | $10,000 | Same-day available | See site |
| Rent-A-Center | See site | See site | No credit needed |
| Roadrunner Financial | See site | Real-time decision | All credit welcome |
| Best Egg | $50,000 | See site | See site |
Top-Rated Lending Options for Arkansas Borrowers
1. FastLendGo
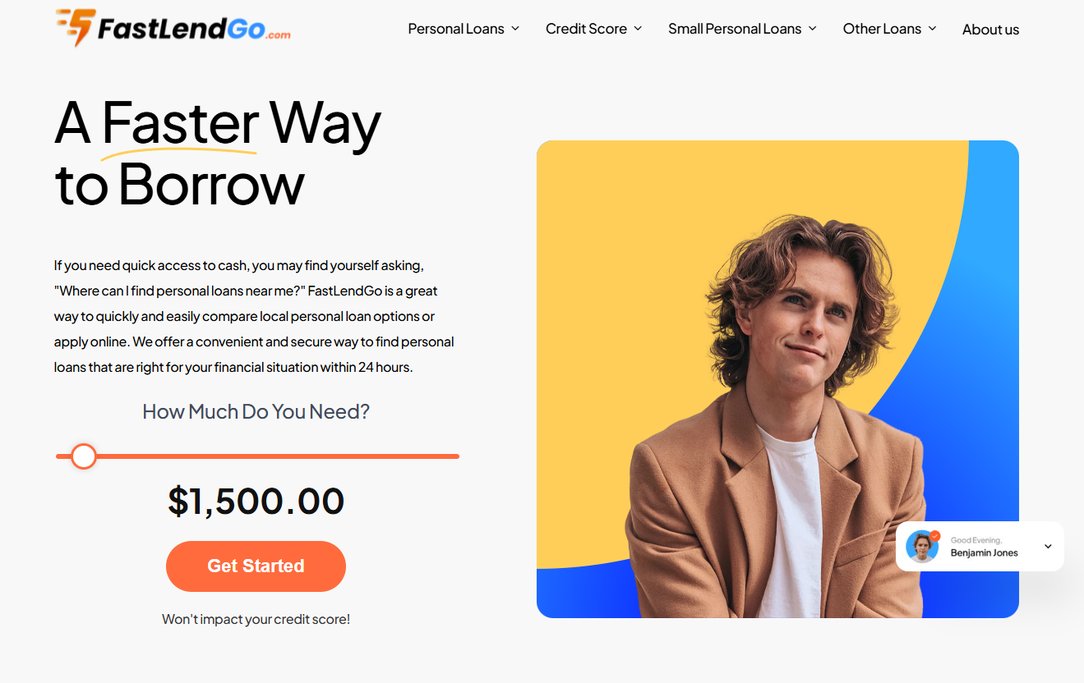
Life often throws curveballs that demand immediate cash. You might find yourself staring at an unexpected dental bill or a car that suddenly refuses to start. FastLendGo is designed for these exact moments, prioritizing rapid turnaround times to help you weather the storm. It serves as a handy bridge for those wanting to weigh different local options without getting bogged down in red tape. fastlendgo.com
Traditional banks can be quite finicky if your credit history is a bit thin or incomplete. This provider fills that gap by offering various financing tiers. You can secure a modest $500 loan for small necessities or opt for larger amounts to handle major life transitions. It sits in that useful middle ground between predatory payday loans and the rigid requirements of major banks.
Timing is everything when an emergency strikes your wallet. Waiting weeks for a decision isn’t an option when the pressure is on. Their digital application is streamlined to ensure you receive an answer when it matters most, keeping you moving forward rather than stuck in limbo.
Pros:
- Swift access to multiple funding levels
- Tailored for specific needs like roofing or dental costs
- Straightforward online comparison tool
Cons:
- Navigating the website can sometimes feel a bit tricky
2. Balance Credit
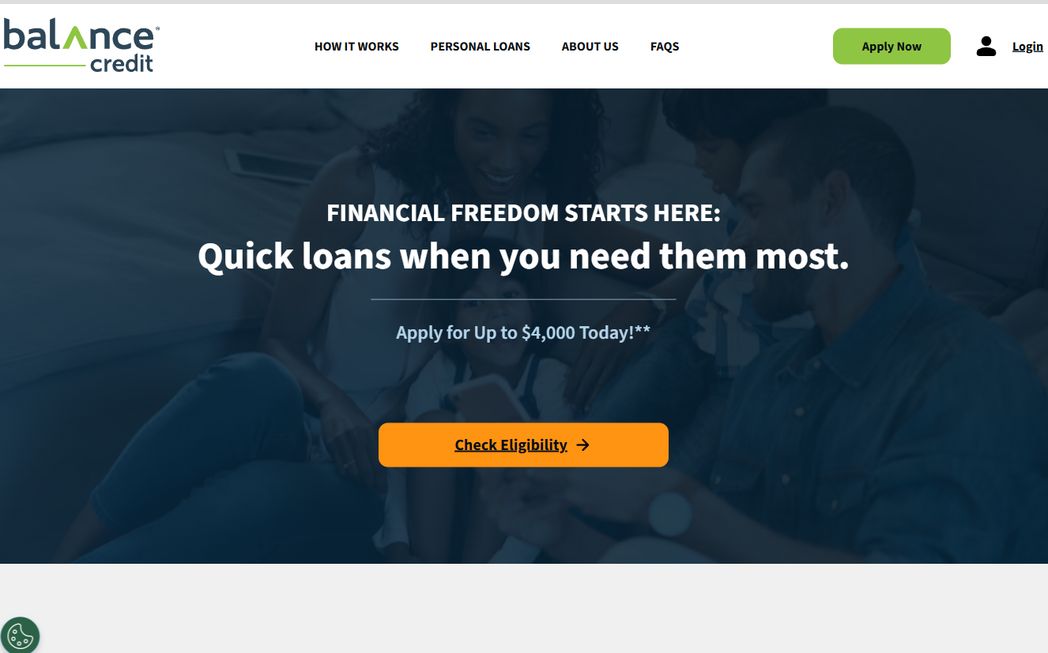
Think of Balance Credit as a financial ally when things get tight. Maybe you need to cover a sudden utility spike or pay a security deposit on a new apartment to keep your living situation stable. They aim to make the process as painless as possible, avoiding the heavy paperwork and confusing legal jargon that often causes such high levels of stress.
One of their most attractive features is the absolute lack of penalties for early repayment. This is a massive advantage for anyone looking to minimize interest costs. If a sudden tax refund or a work bonus lands in your lap, you can pour that cash directly onto your principal. You won’t be penalized for being fiscally responsible and paying off your debt ahead of schedule.
By removing these prepayment hurdles, they hand the steering wheel back to you. You won’t feel trapped in a financial corner just because you decided to be smart with your extra money. It is a refreshing approach to consumer debt.
Pros:
- No extra fees for paying off debt early
- Funds can arrive by the next business day
- Checking eligibility won’t hurt your credit score
Cons:
- Borrowing is capped at a maximum of $4,000
3. NetCredit
NetCredit operates under the philosophy that you are much more than a single number on a credit report. Instead of relying on outdated methods, they utilize advanced algorithms to view your entire financial landscape. This is a real lifesaver for people who might have a single late payment from a year ago but are otherwise reliable earners.
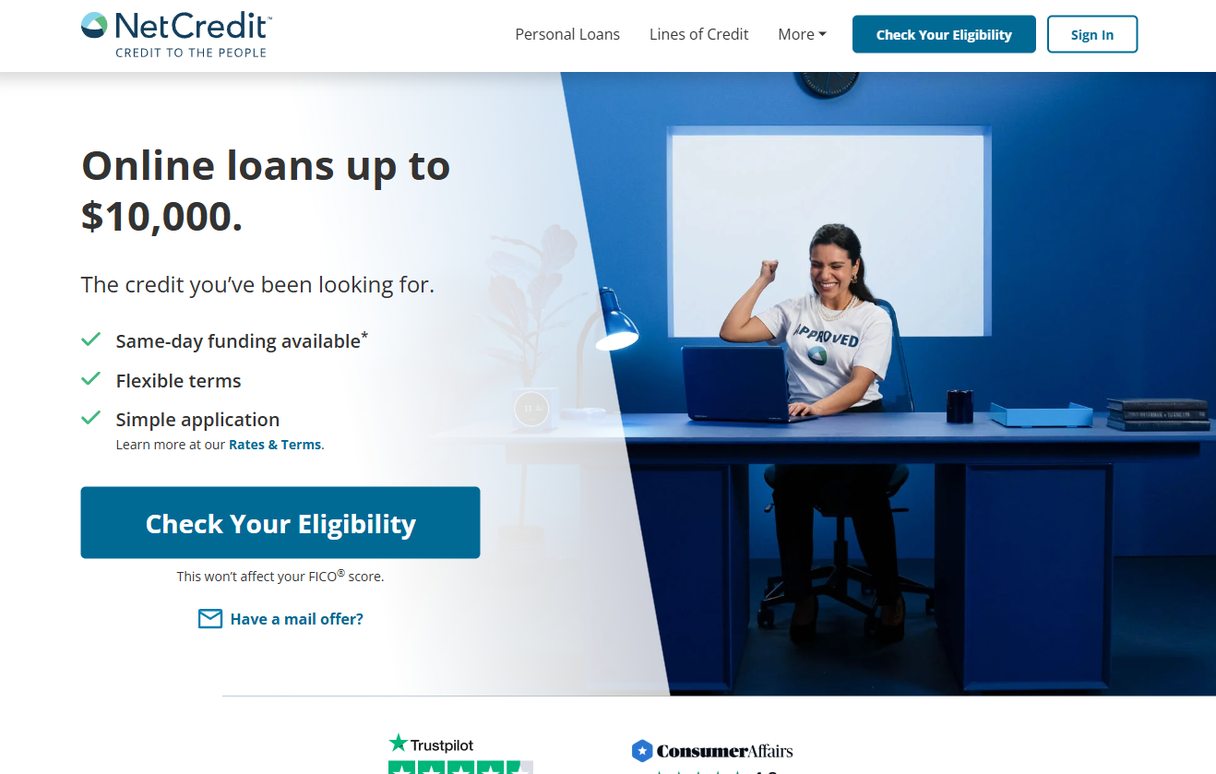
With loan limits reaching as high as $10,000, they provide a much sturdier safety net than your average quick-cash lender. This amount is often the perfect tool for consolidation. You can roll those annoying, high-interest credit card balances into one single, manageable monthly payment, simplifying your life without a mountain of tedious paperwork.
You can explore your potential options through a soft check that doesn’t touch your FICO score. This makes it a low-risk way to see where you stand before you make a formal commitment. It takes the guesswork out of the equation, allowing you to plan your next move with total confidence.
Pros:
- Generous loan limits up to $10,000
- Possibility of same-day funding
- Uses a holistic approach to reviewing applicants
Cons:
- Final terms depend heavily on individual underwriting
4. Rent-A-Center
Rent-A-Center takes a completely different path by specializing in rent-to-own arrangements. Rather than taking out a traditional cash loan, you are essentially leasing the items you need. This works wonders for furniture, large appliances, or electronics when you need to furnish a new home immediately but don’t have the cash on hand.
This “no credit needed” pathway is a total game-changer. It is perfect for those who have been pushed out of traditional banking circles or anyone who simply wants to avoid a hard credit inquiry. You can get essential items, like a new sofa or a refrigerator, with very little money required upfront.
This model is incredibly effective at bridging short-term cash flow gaps. If your washing machine dies on a Tuesday, you can get a replacement running without waiting for a bank’s approval. It is a practical, immediate solution for everyday household necessities.
Pros:
- Many items require no credit check at all
- Minimal initial costs to get items home
- Huge selection of various household goods
Cons:
- The total cost can climb due to the rental structure
5. Roadrunner Financial
Roadrunner Financial is a specialized player built specifically for the powersports community. If your heart is set on a new motorcycle, an ATV, or even a golf cart, this is the lane for you. They skip the long, drawn-out dealership haggling and the slow-moving financing departments that big-box retailers use.
Their pre-qualification process is incredibly fast, providing you with a real-time decision. This is vital if you have spotted a great deal at a dealership in Fort Smith or Fayetteville and need to move quickly. Walking into a showroom knowing exactly what your budget looks like gives you a massive advantage in negotiations.
They truly understand the seasonal nature of the powersports market. It is a niche service that avoids the generalities of standard lenders and goes straight to the specific needs of riders and enthusiasts.
Pros:
- Specifically tailored for powersports enthusiasts
- Instant decisions with no impact on credit
- Rates remain valid for a 30-day period
Cons:
- Very niche focus; not intended for general spending
6. Best Egg
Best Egg is a powerhouse in the personal loan world, particularly when it comes to large-scale debt consolidation. If you are looking to sweep several high-interest payments into one single, manageable chunk, this is a premier option. They leverage smart technology to ensure the user experience remains fluid rather than complicated.
The company provides fixed interest rates and flexible terms, offering far more stability than the unpredictable nature of variable-rate loans. For those with collateral, such as home fixtures, they can often provide even lower rates, which helps save you a significant amount of money over the life of your loan.
This makes them a top-tier choice for people ready to stop living in “survival mode.” It is a strategic move for those looking to transition from simply managing debt to long-term, stable financial planning and recovery.
Pros:
- Substantial loan amounts reaching $50,000
- Predictable payments through fixed interest rates
- Strong reputation with BBB and customer reviews
Cons:
- The best rates are usually reserved for better credit
Mastering the Art of Comparing Loan Conditions
Before you ink a deal on any borrowing agreement, you must distinguish between the “Interest Rate” and the “APR.” Think of the interest rate as just a single piece of the puzzle, as it only measures the cost applied to your principal. However, the APR is the whole picture, incorporating extra expenses such as processing or origination fees.
If you find yourself weighing two different lenders, ignore the simple interest rate for a moment. Instead, focus your eyes on the APR to grasp the actual price of the capital you are receiving. This ensures you aren’t blindsided by hidden costs lurking beneath the surface of a seemingly low rate.
Consider these three vital evaluation steps to protect your wallet:
- Determine the Full Repayment Amount: Simply multiply your monthly installment by the total number of months in your term. Once you have that sum, subtract your initial loan amount from it. This reveals the precise amount of interest and miscellaneous fees you are actually handing over.
- Scrutinize Prepayment Penalties: Much like the experiences discussed with Balance Credit, certain lenders will slap a fee on your head if you try to settle the debt ahead of schedule. Always hunt for lenders that permit you to pay off the balance early without any added penalties.
- Assess Your Monthly Cash Flow: Take a long, hard look at your current household budget. You need to decide if the new monthly obligation fits snugly into your lifestyle or if it leaves you walking a tightrope with no safety net for unexpected emergencies.
Staying Sharp While Borrowing in Arkansas
Navigating the world of credit requires a watchful eye and a bit of grit. It is tempting to just pick the first lender that flashes a low rate, but that is a recipe for disaster. You have to dig into the nitty-gritty details to ensure you aren’t stepping into a financial minefield.
Watch out for those sneaky extra costs that tend to hide in the shadows. Things like origination charges or penalties for missing a deadline can cause your total debt to snowball unexpectedly. Always keep an eye on the fine print before you sign anything.
Picture this: you secure a $1,000 loan, but the lender takes a $100 origination fee right off the top. You only see $900 in your bank account, yet you are paying interest on that full $1,000 amount. It is a bitter pill to swallow.
Don’t let a momentary emergency cloud your judgment regarding what you can actually afford. It is incredibly easy to lose track of your monthly budget when you are scrambling to keep your head above water. Make sure the payments are realistic.
Smart Financial Strategies
A loan should act as a bridge to stability, not a weight that pulls you deeper into the mud. If your goal is to consolidate existing debt, math is your best friend. The new interest rate must be much lower than your current ones.
Otherwise, you are just playing a high-stakes game of musical chairs with your money. Shuffling debt from one pile to another doesn’t actually shrink what you owe. You need a real solution, not just a temporary change in scenery.
Always do the math on the total cost of credit before you commit. A lender might dangle a tiny monthly payment in front of you to lure you in. However, if the repayment period stretches out over three years, the total cost could skyrocket.
You might end up paying back twice the amount you originally borrowed. It is a trap that many fall into when they are in a rush. Take a moment to breathe, read the fine print thoroughly, and select the path that truly aligns with your long-term needs.