Secure the Best Tractor Financing Rates from Top Lenders Today
Last updated: 2026-10-16
Gathering the necessary funds to sustain agricultural production frequently proves more grueling than the physical labor of the season. If you are looking to acquire a massive fleet of combines to bolster a major operation, or perhaps just a lone utility tractor for a backyard plot, your current signatures will shape your liquidity for a long time. It is a precarious dance involving complex arithmetic and perfect timing.
A single slip on interest percentages or a sudden, large lump sum payment can wreck your seasonal financial planning. You definitely do not want twelve months of relentless toil to morph into an endless loop of unpaid loans. Finding a source of funding should feel less like a simple business deal and more like selecting a teammate who supports your growth instead of blocking it.
As you evaluate various paths, keep a close eye on the agility of the repayment structures and the speed of funding. You must also weigh how a provider views your unique credit profile. While the rapid turnaround of online-only approvals is incredibly alluring, do not overlook the lasting security and more competitive rates frequently offered by traditional, physical banks.
- Mahindra
- FastLendGo
- AgDirect
- Yanmar
- Manhattan Bank
- VivaLoan
- Roadrunner Financial
Our Selection Methodology
Selecting the right lenders wasn’t a walk in the park. We cast a wide net across the agricultural landscape to ensure our recommendations were top-tier. Our final group features a diverse blend of local community banks and specialized machine manufacturers.
We didn’t want to just skim the surface of glossy advertisements. Instead, we dug deep into how these financial institutions actually support a farm’s seasonal rhythm. Every provider was vetted for their ability to scale alongside your growing operation.
Speed and the complexity of collateral were our main yardsticks. Some companies lean heavily into lightning-fast digital tools that use “soft” credit checks. These won’t leave a dent in your credit score while you’re just shopping around.
Other options offer the steady, rock-solid foundation provided by traditional secured lending. We weighed whether a provider is built for massive, high-ticket machinery or those sudden, urgent repairs that crop up mid-season. It’s about finding a tool that fits your specific task.
This diverse lineup ensures no farmer is left out in the cold. Whether you are hunting for a massive $200,000 harvester or just a $5,000 utility trailer, there is a path forward. Your business shouldn’t have to bend itself to fit a rigid lender’s mold.
| Lender Name | Loan Capacity | Approval Velocity | Credit Standards | Niche/Terms |
|---|---|---|---|---|
| Mahindra | check website | check website | 550 FICO floor | includes 6-year warranty choices |
| FastLendGo | $500 – $5,000+ | Rapid delivery | Every credit profile | Specializes in personal funding |
| AgDirect | check website | Instant for most | check website | Covers used and new gear |
| Yanmar | check website | check website | check website | Worldwide reach |
| Manhattan Bank | check website | check website | check website | Offers personal and commercial |
| VivaLoan | $100 – $15,000 | Can arrive by tomorrow | All credit levels accepted | Micro personal lending |
| Roadrunner Financial | check website | Immediate results | Any credit rating | Powersports specialty |
Prominent Financing Options for Agricultural Needs
1. Mahindra
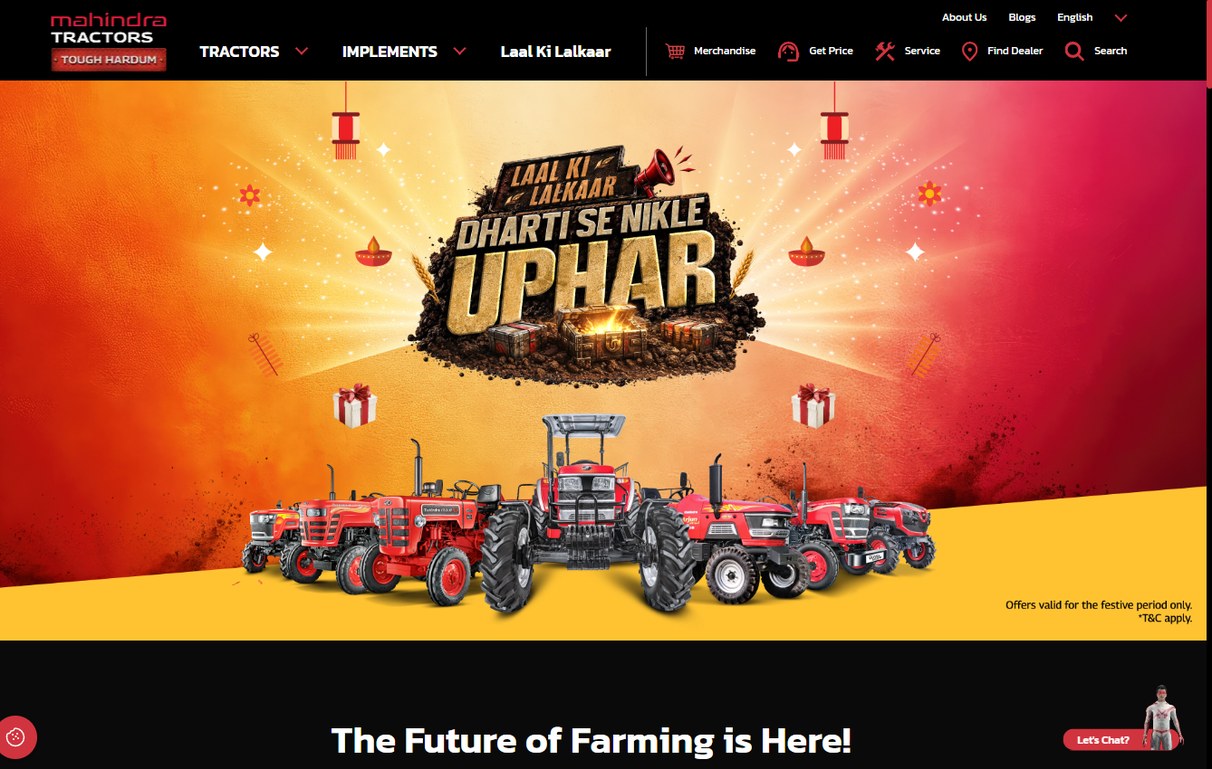
Mahindra has established a formidable presence within the farming world. They provide tailored funding solutions designed to meet diverse requirements, acting as a lifeline if traditional banking hurdles seem too high. It is a dependable choice for those seeking manufacturer-backed security and a brand deeply embedded in rural life.
Applicants can secure options even with a minimum 550 FICO score. This accessibility is vital for growers with thin credit histories or those weathering seasonal financial dips. Their extensive dealership network streamlines the entire journey, frequently allowing for face-to-face consultations and direct applications right on the showroom floor.
Pros:
- Accessible 550 FICO minimum entry
- Support for limited credit histories
- Established brand trust and visibility
Cons:
- Approval is contingent upon specific criteria
2. FastLendGo
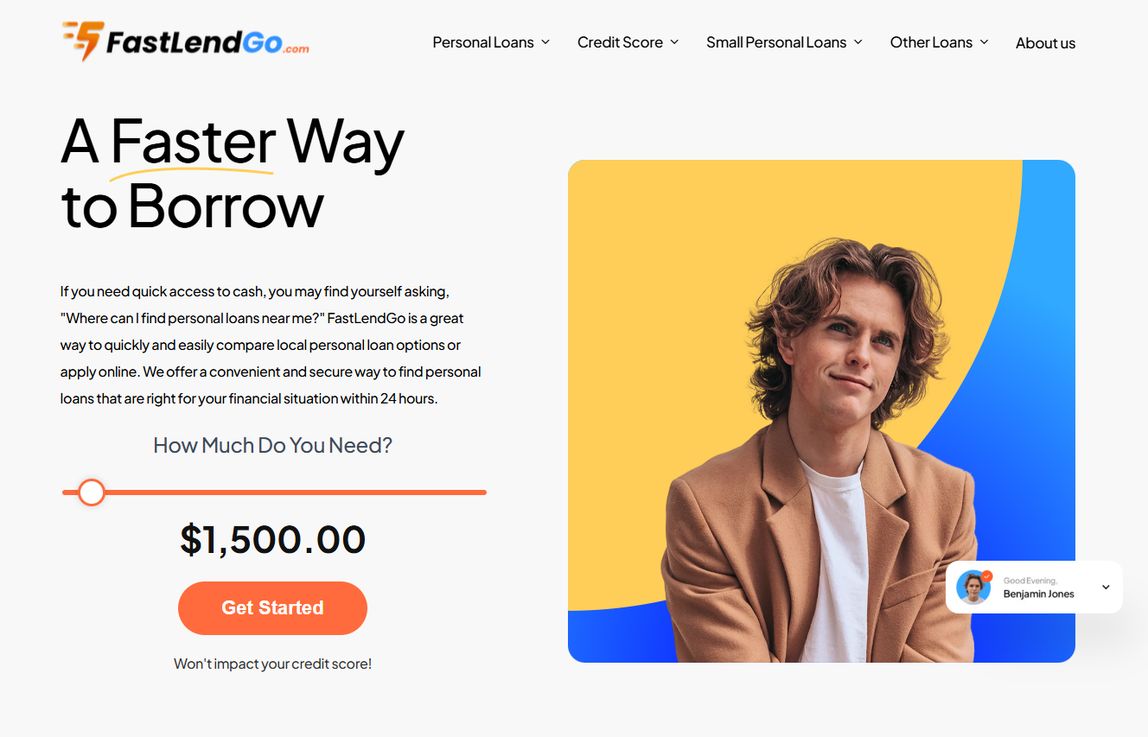
FastLendGo serves as a versatile safety net for those requiring rapid liquidity. While their menu includes a wide array of personal loans, their lightning-fast turnaround makes them an ideal resource for urgent operational hiccups. This includes purchasing fuel in bulk or managing sudden repair bills that fall outside standard costs. (fastlendgo.com)
If an unexpected mechanical failure leaves you in a lurch, this lender moves at a sprint. They cater to a diverse crowd, from individuals with poor credit to high earners seeking unique loan structures. Utilizing high-speed digital workflows, they are perfectly suited for the modern grower who cannot wait weeks for a committee to deliberate.
Pros:
- Rapidly deployable cash access
- Service available across various US states
- Adaptable for poor credit profiles
Cons:
- Focus is primarily on personal loans, not specialized farm gear
3. AgDirect
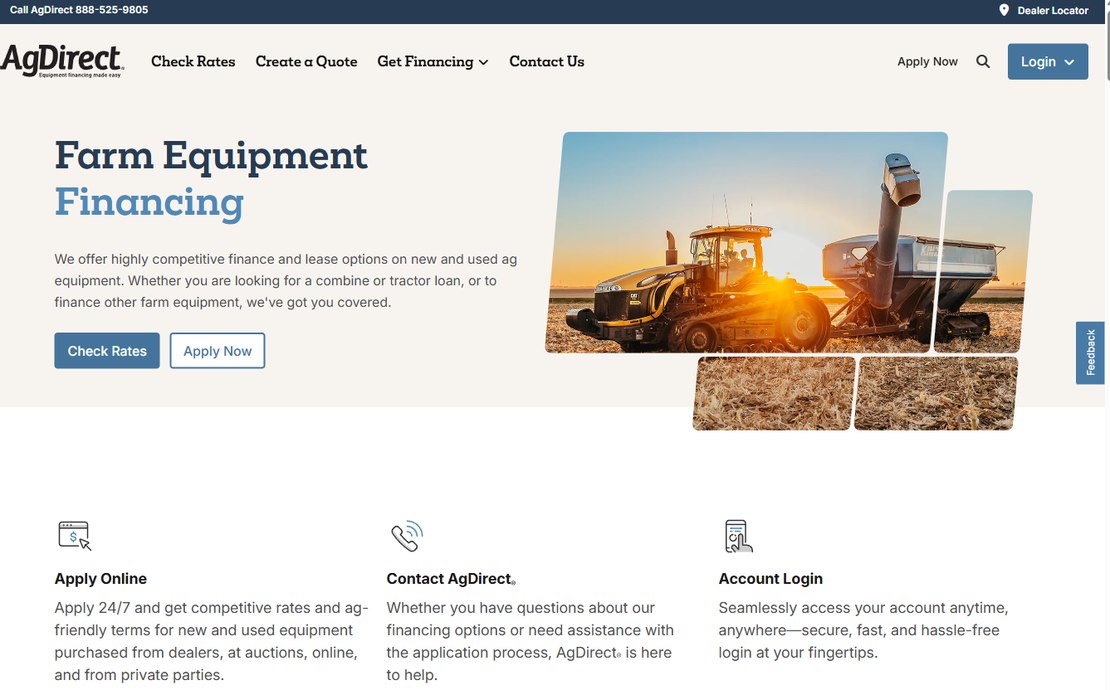
AgDirect acts as a heavyweight contender in the specialized machinery financing arena. They facilitate acquisitions for both brand-new and pre-owned equipment, whether you are buying from a dealer, a private owner, or an auction. Such versatility is a game-changer if you spot a bargain at a local auction and need financing that moves as swiftly as the auctioneer’s gavel.
Their digital infrastructure is remarkably efficient. Most users receive a credit decision in mere seconds, allowing you to secure equipment before a rival can swoop in. This speed is critical in a high-demand market where a tractor might disappear in a single afternoon. It is a streamlined, modern approach that eliminates tedious paperwork.
Pros:
- Instantaneous credit decisions for most applicants
- Funding for new, used, and private sales
- Intuitive online application journey
Cons:
- Centrally focused on equipment rather than general liquidity
4. Yanmar
Yanmar is a household name that brings a wealth of international expertise to the sector. With a footprint spanning the United States, Europe, and Asia, they are a reliable partner for those desiring a manufacturer with a global reach and standardized service protocols.
Partnering with a manufacturer-aligned lender means interacting with experts who grasp the intrinsic value of your machinery. They understand that utility often follows the harvest cycle, allowing them to suggest repayment schedules that a standard bank might miss. This specialized knowledge often results in better terms for niche agricultural implements.
Pros:
- Substantial global presence and stability
- Expertise linked directly to the manufacturer
- Wide-ranging regional availability
Cons:
- Availability can vary significantly by region for certain products
5. Manhattan Bank
Manhattan Bank provides a much more traditional and steady financial foundation. They offer a blend of business and personal loans, making them an essential partner for established operations seeking long-term banking stability. For a legacy farm, a dependable partner often outweighs the allure of a quick, superficial loan.
If you value human connection, you can consult directly with a dedicated loan officer. This personal touch is invaluable when tackling complex business matters, such as land acquisitions or massive facility expansions. Walking into a physical branch to discuss your specific seasonal cycle offers a level of comfort that digital-only lenders simply cannot replicate.
Pros:
- Direct access to professional loan officers
- Security provided by FDIC insurance
- Range of both business and personal products
Cons:
- Documentation requirements may be more rigorous than fintech alternatives
6. VivaLoan
VivaLoan is designed for the individual needing cash fast without drowning in endless paperwork. They specialize in smaller personal loans, ranging from $100 up to $15,000. This provides an agile way to bridge a tiny financial gap, such as a sudden part failure that requires an immediate purchase from your supplier.
Rapid funding is their hallmark, with money often hitting your account as soon as the next business day. For a farmer facing a sudden vet bill or a minor equipment repair, this efficiency is a godsend. It serves as a perfect middle ground between using a high-interest credit card and applying for a large commercial loan.
Pros:
- Rapid funding, frequently by the next business day
- Minimal loan minimums
- Open to all credit profiles
Cons:
- Loan limits are too small for significant machinery
7. Roadrunner Financial
Roadrunner Financial is a niche provider focused on the powersports and small utility vehicle sector. They are a top-tier choice if your farming tasks rely on ATVs, side-by-sides, or golf carts. Many modern agricultural operations find these mobile, smaller vehicles essential for daily field movement.
Their pre-qualification process is streamlined and will not dent your credit score. This allows you to explore various financing tiers without the fear of a hard inquiry impacting your rating just before a larger application. It lets you test the waters of different rates with zero financial risk to your standing.
Pros:
- No impact on credit score for checking rates
- Niche focus on utility and powersports vehicles
- Real-time decision-making capabilities
Cons:
- Limited specifically to vehicles like side-by-sides and ATVs
Navigating the Actual Expenses of Loans
It is easy to get swept up in the siren song of a small monthly installment. Many producers find themselves staring at those manageable figures, thinking they have scored a bargain. However, focusing solely on your immediate cash flow can lead you into a financial thicket.
To truly grasp the weight of your debt, you must evaluate the Total Cost of Ownership (TCO). This isn’t just about what leaves your pocket today, but what vanishes over the long haul. You need to tally every cent of interest paid throughout the duration of the agreement.
Consider a scenario where you opt for a 7-year term because the monthly rate seems painless. Even if that interest rate is lower than other options, it could be a trap. You might find yourself shelling out $5,000 more in total interest compared to a 5-year loan with a marginally higher percentage.
Before you pick up the pen and sign those binding papers, keep these three critical elements on your radar:
- Amortization Schedule: During the initial stages of your repayment journey, how much of your hard-earned money is actually chipping away at the principal versus merely covering interest?
- Prepayment Penalties: Should a bumper crop allow you to settle your debt ahead of schedule, check if the bank will slap you with an extra fee for being early.
- Variable vs. Fixed Rates: When inflation starts climbing, a variable rate can feel like a heavy anchor if interest rates suddenly skyrocket. A fixed rate offers the steady ground required for predictable, long-term farm budgeting.
Building a Strong Loan Package
The path to securing funding, whether through a neighborhood lender or a digital fintech firm, hinges entirely on the caliber of your paperwork. You need to present yourself as a steady hand on the tiller to get the best terms. Banks aren’t just handing out cash; they are looking for a low-risk partner with a roadmap for growth.
Think of your application as a first impression at a high-stakes meeting. If your documentation is messy, the approval process will likely grind to a halt before you can even say “amen.” To ensure you aren’t left out in the cold, you must approach this with meticulous attention to detail and professional polish.
Securing favorable interest rates is often about the preparation you do before you ever sit down with a loan officer. A well-organized file acts like a grease for the wheels of bureaucracy, speeding up the entire decision-making process. To maximize your odds of success, follow this checklist to ensure nothing slips through the cracks.
- Compile Your Fiscal Records: Gather your profit and loss (P&L) statements, current balance sheets, and your tax returns from the previous two years. Keeping these documents in a digital folder ready for instant upload can prevent unnecessary waiting periods.
- Identify the Machinery’s Worth: You need the exact year, serial number, model, and make of the equipment you intend to buy. If you are looking at pre-owned machinery, ensure you possess a realistic understanding of its current market price.
- Audit Your Credit Profile: Never let a lender be the one to discover a mistake on your report. If a low score is staring you in the face, prepare a narrative to explain it, perhaps noting a temporary seasonal debt cycle to provide necessary context.
- Outline Your Debt Strategy: You must be able to demonstrate exactly how this new asset will fuel the income required for repayment. A strong example might be stating, “This new harvester will reduce labor costs by 15%.”
Choosing Your Financing Route
Before you pick up a pen to sign those binding papers, you must scrutinize the true price of debt. It is easy to get caught up in a tiny monthly bill, but that is often a siren’s song. You need to calculate the cumulative interest accrued over the entire lifespan of the loan.
Sometimes, a smaller monthly installment is just a mask for a much extended repayment period. Taking the long road to pay off equipment can drain your pockets far more than you might initially expect. It is a classic trap that turns a modest upgrade into a heavy financial anchor.
Don’t let the excitement of seeing a shiny new machine in the lot cloud your judgment. Rushing into a deal simply because the inventory is sitting there is a recipe for regret. You should always play the field and compare different options before committing your hard-earned capital.
You might find that a local community bank offers much more favorable rates for the long haul. On the flip side, manufacturer-based lenders are often the kings of convenience. They frequently provide specialized coverage that banks simply cannot match, making the decision a bit of a balancing act.
Your personal credit score acts as the compass for this entire journey. If your score is currently a bit lackluster, do not lose sleep just yet. There are lenders out there specifically designed to work with various financial backgrounds.
Companies like Mahindra or VivaLoan are known for being much more accommodating to diverse credit profiles. They understand that a farmer’s wealth isn’t always reflected in a simple credit number. Taking a moment to assess your own financial standing before you hit the pavement will save you immense headaches.
Knowing exactly where you stand prevents wasted afternoons at the dealership. When you walk in with a clear head and a firm grasp of your credit, you are in a much stronger position. This preparation ensures you acquire the vital machinery required to expand your operations effectively.
Leave a Reply