Top-Rated Lenders for a Personal Loan After Bankruptcy in 2026
Last updated: 2026-10-16
Navigating the aftermath of a bankruptcy can feel like wandering through a heavy mist without a compass. You might find yourself scrambling to fix a vehicle just to make it to your shift. Perhaps a sudden medical invoice arrived right after your discharge, leaving your bank account feeling quite light.
Sometimes, these loans serve as a vital bridge when a job change leaves a sudden hole in your monthly budget. You are searching for a partner who recognizes your future potential. You need a lender who looks past your previous financial mishaps to see the person you are becoming today.
The landscape of borrowing has undergone a massive transformation lately. It used to be that a bankruptcy filing was a digital “keep out” sign. Now, modern fintech firms and local community institutions look at your current patterns instead. They prioritize your financial momentum over the old scars on your credit history.
It is less about your old mistakes and more about your current trajectory. Finding a lender requires more than just a quick glance at the APR. You must weigh the speed of funding against the minimum requirements and the level of flexibility provided. It is a delicate dance between immediate relief and lasting stability.
Some lenders specialize in rapid cash for those urgent, unexpected emergencies. Others prefer to offer structured installment plans designed to help you repair your credit score. Ultimately, you are balancing the need for speed against the necessity of a long-term financial foundation.
Accessibility is a double-edged sword that means different things to different people. An extremely easy approval process might come with a heavy price tag for that convenience. Conversely, a lender with more rigid criteria might provide the lower interest rates required for managing debt long-term.
You must decide if you are looking for a temporary bandage or a permanent structural solution. The choice depends on your specific goals for the coming years. Weighing these options carefully is the first step toward reclaiming your peace of mind.
- FastLendGo
- SoFi
- Prosper
- Avant
- Allegiance Credit Union
- VivaLoan
- World Finance
Selecting a Lender After Filing for Bankruptcy
Our current list puts a massive spotlight on two main things: how quickly you get cash and how simple the approval process feels. Financial crises rarely wait for your credit score to bounce back from the depths. Sometimes, you just need to plug a hole in a leaking roof or pay a mounting utility bill.
If a sudden delay of seventy-two hours would leave your lights turned off, you can’t afford a sluggish lender. We focused our research on companies that offer straightforward avenues for individuals with various credit backgrounds. It is about survival and moving forward, not waiting for perfection.
We also took a close look at the range of funding options offered by each company. A lender that only deals in tiny microloans is about as useful as a paper umbrella if you are trying to consolidate a pile of old debts. You need actual capital to make real progress.
On the flip side, standard brick-and-mortar banks often throw up massive roadblocks. They frequently demand collateral or a stellar score that someone fresh out of bankruptcy simply won’t have yet. We hunted for providers using “soft” inquiries so you can hunt for deals without bruising your score.
| Provider | Funding Range | Speed of Cash | Credit Standards |
|---|---|---|---|
| FastLendGo | $500 – $5,000+ | Rapidly available | Bad/Fair/Good/Great |
| SoFi | see site | see site | see site |
| Prosper | $2,000 – $50,000 | Swiftly sent | see site |
| Avant | see site | see site | see site |
| Allegiance Credit Union | see site | see site | see site |
| VivaLoan | $100 – $15,000 | As early as tomorrow | All credit types welcome |
| World Finance | see site | see site | see site |
Premier Lending Options to Boost Your Credit Score
1. FastLendGo
When you find yourself in a financial pinch, FastLendGo can act as a vital safety net. They provide a diverse array of funding choices, spanning from modest $500 loans to more substantial $5,000 packages. This versatility is a lifesaver when you are juggling various expenses, such as an urgent car fix alongside a hefty tax bill.
The entire digital experience is engineered for rapid deployment, making it an ideal choice for those needing instant cash. Whether it’s an unexpected dentist visit, an auto repair, or a home maintenance emergency, comparing local rates is a breeze. Unlike traditional banks that drown you in paperwork and endless errands, FastLendGo utilizes a digital-first method to streamline the process.
It stands out as a dependable solution for quick fixes when waiting for a sluggish approval process simply isn’t an option.
Pros:- Versatile loan amounts ranging from $500 up to $5,000 and more.
- Targeted financing for specific needs like roofing, dental, or auto expenses.
- Open to various credit profiles, from poor to excellent.
- Interest rates might not be the most competitive for those with top-tier credit.
2. SoFi
SoFi functions much like a comprehensive financial hub. While many users first encounter them through banking or investment services, they also provide sophisticated tools designed to help you master your money. Their high-yield savings accounts are particularly useful for building an emergency fund, offering a secure place to grow cash while your credit score inches upward.
By setting up automated savings through their intuitive platform, you can construct a financial cushion that prevents you from relying on high-interest debt later on. This lender is a dream for the individual who desires to manage their entire financial life—from checking to mortgages—under one single roof.
They tend to be more selective than micro-lenders, but their product suite is tailor-made for those who have weathered their toughest economic storms. If you are eyeing long-term prosperity and wealth accumulation, this is a highly polished choice.
Pros:- A seamless mix of insurance, investing, and banking services.
- Competitive APY for your savings accounts.
- Highly intuitive and digital-centric platform.
- Often necessitates a better credit score to access the best loan terms.
3. Prosper
Prosper offers a unique window into the world of peer-to-peer (P2P) lending. They can provide significant capital, with amounts stretching from $2,000 all the way up to $50,000. This makes them a powerhouse for anyone looking to wipe out massive debt or cover large costs like home renovations or college tuition.
Because their capital comes from individual investors rather than a traditional bank’s vault, their approval criteria often differ from what you might find at a local branch. The platform itself is both secure and incredibly fast. You can view your potential rates in roughly one minute via a soft credit pull.
This “soft pull” feature is a total game-changer if you want to shop for deals without worrying about dinging your credit score. For those wanting to step outside the traditional banking mold, Prosper provides a streamlined experience and serves as a strong alternative when a standard bank says “no.”
Pros:- Massive borrowing limits reaching up to $50,000.
- Quick rate assessments that won’t damage your credit.
- A rapid and highly secure online application journey.
- Since it’s a peer-to-peer model, approval rates can fluctuate based on investor interest.
4. Avant
Avant is focused on helping you turn a corner in your financial journey. By offering installment loans and credit cards, they provide a way for you to prove your reliability through a history of on-time, consistent payments. Their philosophy feels less like a transaction and more like a partnership, offering tools specifically designed for goals like debt consolidation.
Whether you are looking to merge several high-interest payments into one manageable monthly installment, or you just need a quick loan for a sudden crisis, Avant has you covered. They strive to deliver clear, straightforward answers to even the most complicated financial questions.
Their business model is specifically tuned to cater to the “middle-ground” borrower. These are individuals who might not boast elite credit scores but can demonstrate a steady income and a responsible approach to their finances.
Pros:- Specializes in emergency loans and debt consolidation.
- Offers adaptable solutions for various life stages.
- Supportive tools and a user-centric approach.
- Navigating their specific eligibility requirements can sometimes be tricky.
5. Allegiance Credit Union
Operating since 1963, Allegiance Credit Union is a deeply community-oriented institution. They live by the philosophy that every person’s story is significant, including those currently working to rebuild after a financial setback. This stands in stark contrast to the cold, impersonal nature of massive national banks where you are just another data point.
Inside a credit union, your local connection and your direct relationship with a loan officer actually matter. They offer a variety of products intended to assist you in saving, borrowing, and constructing a more stable future. If you find yourself craving a mission-driven banking experience, switching to a credit union can be quite refreshing.
You will often find more personalized guidance during the application process here. This level of empathy is incredibly helpful when you need to explain why your past bankruptcy is a closed chapter and why your current financial status is on an upward trajectory.
Pros:- Deep community roots combined with a long-standing reputation.
- A mission-driven focus on the well-being of their members.
- A wide range of borrowing and saving products.
- Membership may be restricted by your geographic location.
6. VivaLoan
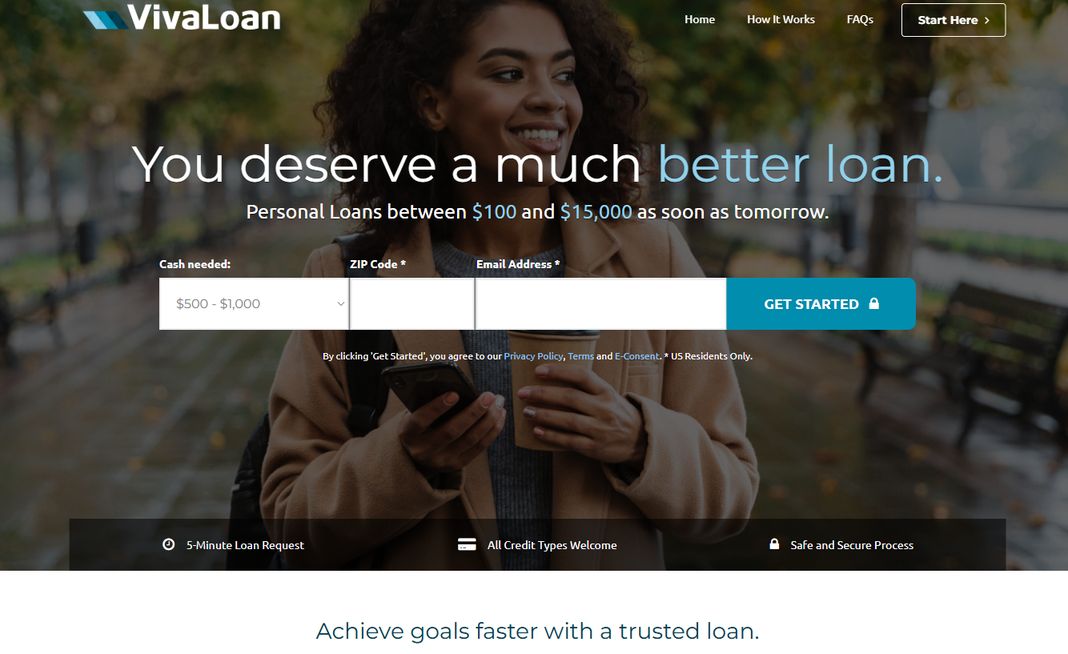
VivaLoan is built for one thing: speed. Their loan amounts are highly flexible, starting as low as $100 and going up to $15,000. This range allows you to find exactly what fits your situation, whether it is a tiny amount for a new set of tires or a larger sum for a significant life event. This flexibility is vital if you are still in the stabilization phase of your financial recovery.
One of their standout advantages is the sheer velocity of funding. It is not uncommon to see the cash in your account as early as the next business day. With an application that takes only five minutes and an open policy for all credit types, they act as a genuine lifeline during emergencies.
While the ease of use is incredibly attractive, it is important to use these funds with a strategic mindset. You want to avoid falling into a trap of high-interest borrowing that might keep you stuck in a cycle of debt.
Pros:- Lightning-fast funding, often arriving by the next business day.
- Extremely low entry point with $100 minimum loans.
- Welcomes borrowers with all types of credit histories.
- The speed and accessibility of the loans can result in higher costs.
7. World Finance
World Finance is a specialized entity within the lending market. They provide a broad spectrum of services, ranging from private to retail banking. Their focus often targets more structured financial environments and niche segments, offering options for individuals who might not fit neatly into the standard consumer lending box.
This might include people managing unconventional income streams or those in need of highly specific loan structures. They provide their clients with a deep, nuanced view of both local and global economic trends to help guide them.
For those seeking a more intricate financial partner, they provide services that go far beyond a simple personal loan. Their expertise is particularly valuable for borrowers who are navigating a complex recovery that involves multiple different asset types.
Pros:- A massive variety of financial services and deep market insights.
- High-level expertise across various banking sectors.
- Professional attention to shifting market trends.
- The services may be more complex than what a standard consumer lender offers.
Strategies for Maximizing Your Approval Odds
Securing a loan after a bankruptcy discharge requires a strategic approach. Lenders want to see “stability indicators.” Even if your score is still recovering, you can improve your odds by providing organized documentation of your income. This means having recent pay stubs, bank statements, and tax returns ready to go. A lender is much more likely to say yes if they see a clear, unbroken line of income.
Another smart move is to consider a “secured” loan if “unsecured” options are proving too difficult. A secured loan is backed by an asset, like a car title or a savings account. Because the lender has collateral, their risk is much lower, which often leads to higher approval rates and better interest rates. Once you pay that loan back, your credit score usually gets a significant boost.
This path paves the way for the larger, unsecured loans you might need later on. It is a way to prove your reliability to the banks while you are still getting back on your feet.
Stumbling Blocks to Watch For While Shopping
The most frequent blunder occurs when borrowers jump at the very first deal that lands in their lap. It feels like a lifesaver, but you must look beyond that enticing monthly installment. A small monthly bill is often a wolf in sheep’s clothing, masking a predatory interest rate or an extended timeline.
If you aren’t careful, you might find yourself shelling out twice the original amount by the time the loan is cleared. Never settle for a surface-level glance at the numbers. Always demand the Annual Percentage Rate (APR) to reveal the actual expense of your debt.
Don’t let a shiny offer blind you to the math. It is vital to scrutinize the total cost of borrowing rather than just the immediate impact on your wallet. Think of it as checking the weather before embarking on a long trip; you need the full picture.
Another major pitfall involves ignoring your credit report until the application is already in motion. Even once your bankruptcy has been officially discharged, ghosts from the past can still haunt your credit history. Discrepancies are more common than you might think during this delicate stage of recovery.
You might find a debt that was legally wiped out still appearing as “unpaid” on your official documentation. Such errors act like anchors, dragging down your chances of approval. Take the time to scrub your records clean before you start knocking on doors.
Correcting these inaccuracies early on is your best defense. A pristine report acts as your calling card in the lending world. By tidying up these loose ends, you position yourself to secure much better terms from potential lenders.
Lastly, you must hunt for any hidden prepayment penalties buried deep within the contract. Some institutions make their money by charging you a fee if you attempt to settle the balance ahead of schedule. This is the last thing a person trying to escape debt should encounter.
Paying off your obligations early is the goal, so don’t let a penalty trip you up at the finish line. It is like running a race only to find there is a wall at the end. Always verify these terms before signing your name on the dotted line.
Approach this entire process with a sense of calm and steady resolve. Building a stable financial foundation is a marathon, not a sprint. If you rush the process, you might find yourself running in circles rather than moving forward.