Compare the Top Rates for Online Personal Loans in Laredo TX
Last updated: 2026-10-16
Facing an unexpected medical crisis or a mountain of auto repair costs can feel like being lost in a thick fog. For those living in Laredo, finding a lifeline requires more than just a fast payout. You need to grasp the fine print and confirm the funds are truly accessible when things get messy.
A broken transmission in a dusty parking lot or a sudden, painful toothache can trigger immense anxiety. Often, the mental weight of financial instability feels much more draining than the actual cost of the service itself. It is a heavy burden to carry alone.
The landscape of digital lending has shifted the playing field entirely. It is vital to look beneath the surface of glossy web advertisements to see if the borrowing limits and processing speeds align with your specific needs. Don’t let the bright colors fool you.
Too many folks get hooked by promises of “instant approval” only to realize the cash arrives late. Some find themselves stuck with interest rates that make a standard bank loan seem like a bargain. Distinguishing between a local credit union and a rapid digital platform is your best defense for your wallet.
- Parra Loan Company
- JetzLoan
- Bridge Credit Union
- GoCredit
Evaluating Your Options Between Area and Web-Based Lenders
Our evaluation methodology prioritized the sheer velocity of fund disbursement. If you are hunting for financing within Laredo, time is often of the essence. Because this border hub thrives on rapid trade, a slow bank transfer is more than a minor nuisance.
A delayed payout could lead to lost wages if your car breaks down. In a city where movement is everything, being stuck without transport is a recipe for disaster. We made sure to prioritize speed as a key metric for our users.
We also weighed the total borrowing capacity against the impact on your credit profile. A “soft pull” is truly a lifesaver for anyone feeling uncertain about their current rating. It is like a trial run for your financial health.
When a company uses a soft pull to display your potential rates, they avoid reporting to the bureaus. This allows you to scan five different quotes without a single point vanishing from your FICO score. Use this period to hunt down the lowest APR available.
Take a look at this comparison to see how various lending models operate in the current economic climate:
| Lender Category | Main Advantage | Ideal Use Case | Time to Receive Cash |
|---|---|---|---|
| Online Marketplaces | Substantial limits & selection | Big purchases (Real Estate/Major Auto) | 24–48 Hours |
| Rapid-Action Lenders | Instant liquidity | Minor emergencies (Bills/Repairs) | Minutes to Hours |
| Credit Unions | Competitive rates & local focus | Sustainable loans & low APR | 3–7 Business Days |
| Credit Boosters | Rating enhancement | Fixing your credit history | Depends on savings strategy |
Top-Rated Laredo Financing Options
1. Parra Loan Company
Sometimes life throws a curveball that requires immediate cash, and Parra Loan Company specializes in those high-speed scenarios. They aren’t designed for restructuring massive debts over several years. Instead, they act like a financial band-aid for sudden emergencies that need a quick fix.
Imagine you are facing a $400 car repair bill that threatens your ability to commute to work. A long-term, five-year loan would be overkill in such a situation. These lenders are tailored specifically for those urgent, short-term financial hiccups that demand a rapid response.
This lender serves as a perfect bridge for those navigating the gap between paychecks. You can start your application via smartphone while sitting in a waiting room or visit a physical branch for a personal touch. They offer more versatility than many digital-only firms by allowing online, phone, or in-person applications.
Pros:
- Borrowing limits range from $100 to $1,840.
- Signature loans do not require any collateral.
- Decisions are made quickly, often within minutes.
Cons:
- The ceiling for loan amounts is somewhat low.
2. JetzLoan
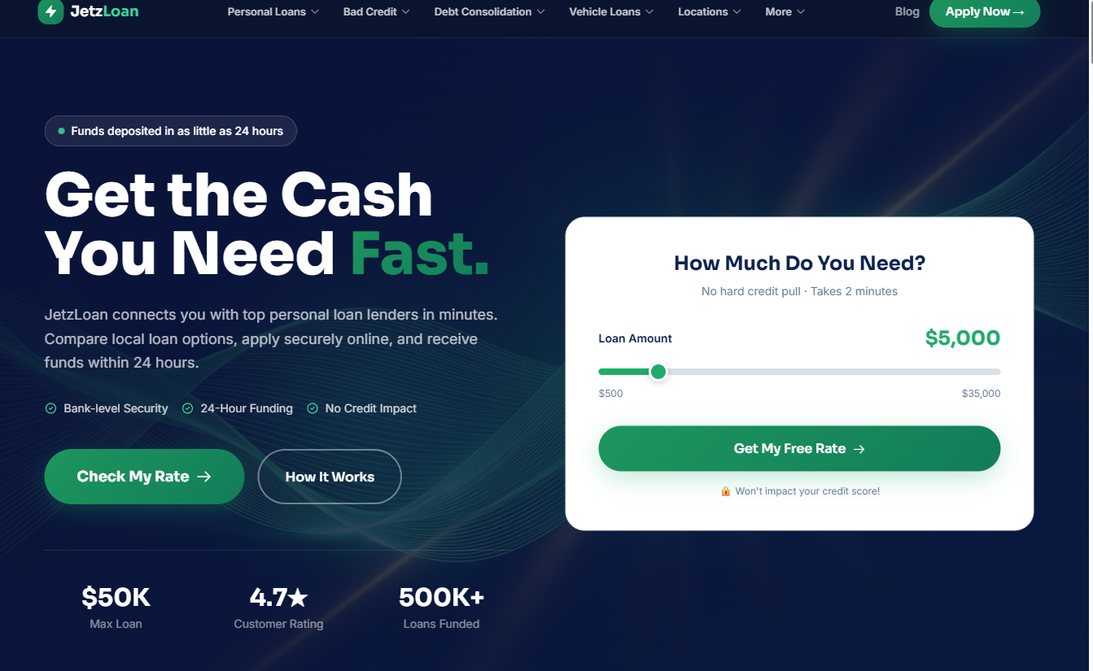
Think of JetzLoan as a massive marketplace connector within the lending landscape. Rather than being a single bank with a limited vault, they function as a bridge to a wide array of different lenders. This allows them to offer much larger sums, reaching up to $50,000.
While a traditional bank is limited to its own capital, JetzLoan scans a vast network to find a provider that fits your specific credit profile. This makes them an excellent resource if you need to find a lender that accommodates your unique financial situation.
If your credit score isn’t exactly perfect, this is a fantastic route to take. They utilize a “no hard credit pull” approach for rate shopping, meaning you can explore your options without any damage to your score. Whether you need $15,000 for a home renovation or a medical procedure, you can view terms without any immediate commitment.
Pros:
- Maximum borrowing amounts reach up to $50,000.
- Funds can arrive in your account in 24 hours or less.
- Checking your rates will not impact your credit score.
Cons:
- The marketplace model means you work with various lenders.
3. Bridge Credit Union
For those who prefer a traditional banking feel, Bridge Credit Union offers a community-centric approach. Because credit unions are owned by their members, their primary mission is serving the local population rather than maximizing shareholder profits. This often results in more empathetic, flexible rules for reliable members.
They offer specialized products like “skip-a-pay” options and holiday loans, which can be a total lifesaver when money is tight during the festive season. These tools help you navigate seasonal financial shifts without the stress of traditional banking rigidity.
If stability is your top priority, a credit union is a rock-solid choice. Their services span both commercial and personal needs, making them a one-stop shop for your household and business. For a Laredo entrepreneur, having one institution that understands both personal bills and business cash flow can simplify your daily life immensely.
Pros:
- Features specialized holiday deals and skip-a-pay options.
- Provides services for both businesses and individuals.
- Operates with a strong member-focused philosophy.
Cons:
- The process might require more paperwork than instant lenders.
4. GoCredit
GoCredit takes a unique path by prioritizing the building of your credit history. This isn’t just a way to get cash for today’s needs; it is a strategic move to ensure easier borrowing in the future. It is essentially a dual-purpose financial instrument.
They employ a “loan-to-savings” structure where a portion of every payment is diverted into a savings account you eventually own. This turns a standard debt into a foundation for future stability. It is a brilliant way to transform a monthly obligation into a growing financial cushion.
This model is particularly useful for younger borrowers or anyone looking to repair their credit standing. Instead of just paying off a debt and returning to a zero balance, you end the cycle with a new savings reserve. This helps prevent the cycle of debt from starting all over again.
Pros:
- Borrow up to $4,000 with this model.
- Builds both credit history and personal savings simultaneously.
- The application is quick and highly secure.
Cons:
- The credit-building focus may not suit those needing large sums.
Uncovering the Real Price of Your Loan
Before you put pen to paper, scrutinize the Annual Percentage Rate (APR). Looking solely at your monthly installments is like watching a movie trailer and thinking you’ve seen the whole film. It only gives you a glimpse of the reality.
The APR serves as the most honest indicator of your total expense. It doesn’t just track interest; it also incorporates administrative charges and origination fees into the calculation. It’s the heavy hitter that tells you the truth about the debt.
Consider this math: a loan boasting a 10% interest rate paired with a $500 fee could end up being more expensive than a 12% loan that carries no upfront costs. Don’t let a low interest rate blindside you.
The duration of your repayment schedule is another critical piece of the puzzle. Choosing a shorter timeframe helps you escape the interest trap by lowering the total amount paid over time. However, this comes with a catch.
While you save money on interest, your monthly bills will climb significantly. Imagine borrowing $2,000 at a 15% interest rate. If you pay it off in 12 months, your total interest is much lower than if you stretched that same $2,000 loan over 24 months.
You must dance a delicate tango between maintaining a comfortable monthly budget and your personal drive to stay out of debt. It is all about finding that sweet spot where your cash flow remains steady.
Keep these three distinct scenarios in mind when you are picking a structure:
The Emergency Fix: Perhaps you need $300 to $1,000 right away to fix a sudden leak or a broken appliance. In these moments, lightning speed is the name of the game. A short-term loan with higher interest might be a lifesaver if it prevents a crisis from escalating.
The Financial Pivot: Are you looking for $2,000 to $7,000 to consolidate various debts? Your primary objective here is to migrate high-interest credit card balances into a single, lower-interest loan. This strategy aims to lighten your monthly financial load significantly.
The Major Life Event: When you need $10,000 or more for a medical emergency or home improvement, you need to think long-term. This situation demands a focus on securing the lowest possible APR alongside stable, predictable repayment terms to ensure your future stays secure.
Steering Clear of Debt Traps
When your bank account is looking a bit thin, you might feel the urge to jump at the first digital offer that pops up. It feels like a lifeline, but slow down a second. Before you click that final button, you need to verify if the company intends to perform a hard credit pull.
Think of a hard pull as leaving a trail of breadcrumbs behind you. Every time a lender checks your score this way, it signals to the rest of the banking world that you are desperately hunting for cash. This can make you appear somewhat unstable, potentially driving up the interest rates on your future applications.
Don’t let the speed of modern fintech blind you to the actual price tag. A quick injection of cash can feel like a miracle when you are in a pinch, but those sky-high APRs are a double-edged sword. What starts as a minor fix can quickly morph into a heavy, long-term financial disaster if you aren’t careful.
Always demand a “Truth in Lending” disclosure before signing any paperwork. This specific document is your best friend because it forces the lender to be brutally honest. It lays out exactly how much every single cent will cost you by the time you finally finish making those monthly payments.
You really ought to comb through the fine print regarding your repayment timeline. Life happens, and some companies offer a “skip-a-pay” option to help during a rough patch. Conversely, other lenders are as rigid as a board and won’t show you any mercy if you miss a date.
Make sure you pinpoint exactly what the late fees look like and whether there is a penalty for paying the balance early. Some lenders actually punish you for being responsible and settling the debt ahead of schedule. Knowing these little details is your shield against turning a quick fix into a permanent weight around your neck.
Leave a Reply