Best Rates for Online Personal Loans in Fort Worth TX: Compare Today
Last updated: 2026-10-16
Navigating the financial landscape of Tarrant County can often feel like wandering through a dense fog without a flashlight. One day, you are dealing with a sudden mechanical failure on I-35, and the next, a hospital invoice arrives out of the blue. Sometimes, the goal is simply to bundle several high-interest debts into one manageable monthly payment. For many locals, the sheer volume of internet-based lending options can make your head spin. The landscape has shifted dramatically over recent years. We have moved away from solely visiting local bank branches toward a vast digital universe filled with fintech innovators, peer-to-peer networks, and massive national banks. Because there are so many paths to take, you must do your due diligence. It is vital to pin down your exact requirements before you start filling out various online forms.
The ideal lender depends entirely on your unique economic profile. No two borrowers are exactly alike, as everyone enters this marketplace with a different set of goals and limitations. Some individuals prioritize speed above all else, needing funds deposited immediately to stay ahead of the upcoming work week. They need cash that arrives as fast as a Texas thunderstorm. Other borrowers might require a lender that is more forgiving regarding a rocky credit history or an inconsistent paycheck. This is a major concern for those working in the gig economy. Freelancers, for instance, often lack the traditional W-2 documentation that standard banks demand. They need a partner that understands the nuances of modern, non-traditional employment structures.
Identifying your specific place in this market is your starting point. You shouldn’t be looking for a loan that adds stress to your life; rather, you want one that provides a sense of relief. The right financial tool should act as a bridge to your goals, not a weight around your ankles. You deserve a solution that eases your burden instead of creating a brand new one.
- Fort Worth City CU
- JetzLoan
- Friendly Finance of Fort Worth
- OneMain Financial
- CashUSA
Measuring Local Financing Choices
When we curated this list, we kept a laser focus on two core pillars: how easy it is to get started and how honest the terms remain. Life in a bustling metropolis like Fort Worth moves at a breakneck pace. You can’t afford to wait around when things go sideways.
Imagine your air conditioning dies in the middle of a blistering Texas summer. Or perhaps your car decides to quit on the highway right when you’re running late. These sudden mishaps can quickly spiral into a mountain of debt if you aren’t prepared for the impact.
Consequently, we prioritized finding lenders that offer a direct route to the cash you need. You shouldn’t feel like you are walking through a maze of paperwork just to get some help. We wanted to ensure our readers find clarity instead of confusion.
We purposefully steered clear of any providers that use labyrinthine application steps or demand endless email chains. It is frustrating to be left hanging. Nobody wants to waste forty-eight hours waiting on a phone call from a loan agent who simply never picks up.
Our evaluation team scrutinized how much people can borrow and what their credit needs entail. Since no two neighbors have the exact same bank account, this list highlights diverse options. You might need a huge sum for a renovation project.
On the flip side, you might only require a tiny bit of extra cash to tide you over until payday arrives. We also examined the difference between soft and hard credit inquiries. Understanding this can save your score while you hunt for the best possible interest rates.
| Provider | Borrowing Limits | Time to Funds | Credit Standards |
|---|---|---|---|
| Fort Worth City CU | Up to $25,000.00 | See site | See site |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No hard credit pull |
| Friendly Finance of Fort Worth | See site | See site | See site |
| OneMain Financial | $1,500 – $30,000 | As soon as 1 hour | See site |
| CashUSA | Up to $10,000 | Next business day | See site |
Top-Rated Lenders in the Fort Worth Area
Fort Worth City CU
If you crave a banking experience that feels like a handshake rather than a data point, this credit union is your best bet. While massive national corporations often hide behind cold, robotic algorithms, this institution prioritizes its community. Because they are member-owned, you aren’t just a number in a database.
This structure fosters a much more personal touch when life gets complicated. They provide a wide array of financial tools, ranging from mortgages and vehicle loans to specific funding for tuition. If you are eyeing a degree but dread the weight of massive student debt, they have tailored solutions waiting for you.
With borrowing limits hitting the $25,000.00 mark, they are a heavy hitter for significant life shifts. Whether you are tackling a sudden kitchen renovation or merging several high-interest debts into one single, easier payment, they have your back. Their website is incredibly user-friendly for the modern professional on the move.
Just remember that you cannot simply walk in off the street; you will likely need to qualify for membership. This usually requires living within Tarrant County or holding a job in the area. It is a small price to pay for that local connection.
Pros:- Diverse selection of specialized loan products
- Loan ceilings reaching $25,000.00
- Streamlined digital application experience
- Membership requirements or specific eligibility rules apply
JetzLoan
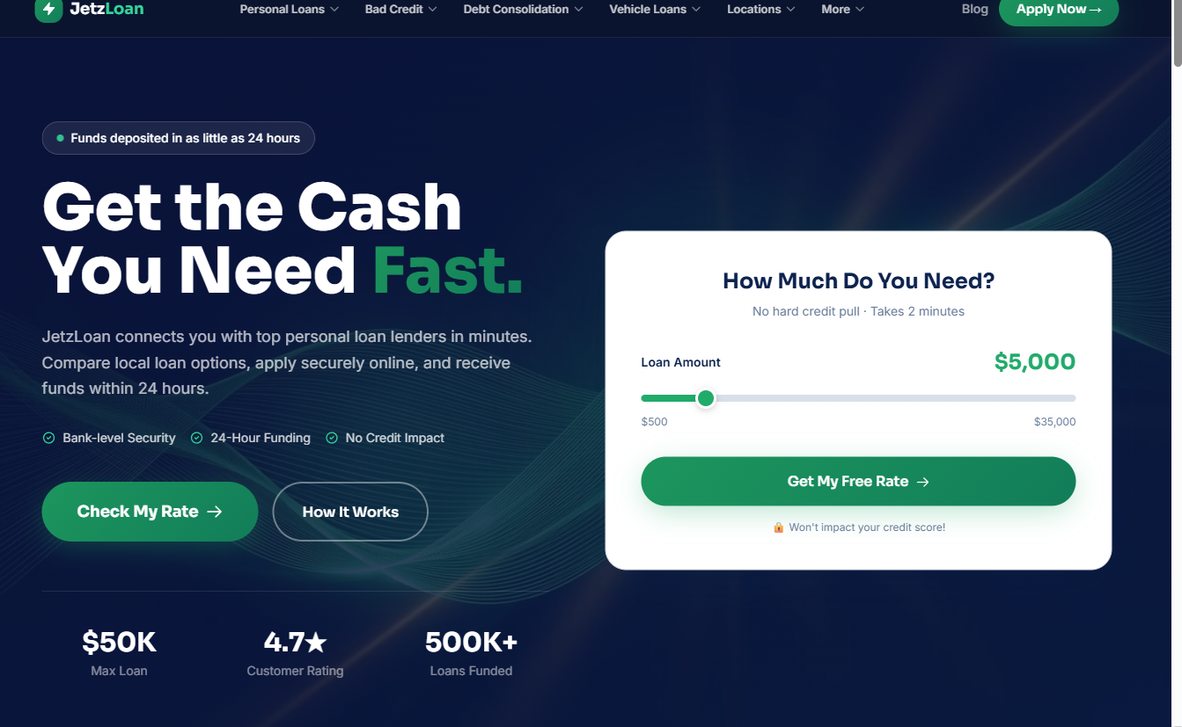
Some financial needs don’t wait for a convenient time; they demand cash right this second. JetzLoan is built specifically for those high-speed moments. They have perfected the art of digital connection, promising to pair you with a lender in just a few short minutes.
This is a playground for the smartphone-savvy consumer who wants to manage their entire world through a screen. The platform shines when you are feeling a bit nervous about your credit score. They utilize a “no hard credit pull” method to show you rates, which is a total game changer.
This means you can shop around for the best APR without worrying about bruising your credit report. It removes the heavy fog of uncertainty that often surrounds the initial search for money. You get to see the actual numbers before making any formal commitments.
Pros:- Check rates without a hard credit inquiry
- Funding can arrive within a 24-hour window
- Maximum loan amounts of up to $35,000
- Functions as a marketplace rather than a direct lender
Friendly Finance of Fort Worth
There is something to be said for the old-school way of doing business. Friendly Finance brings a sense of neighborly stability to the lending world. They have deep roots in the local area, providing a level of reliability that purely digital companies often lack.
For the customer who wants to look their loan officer straight in the eye, this is a sanctuary. They handle all the essentials, including personal loans, debt consolidation, and vehicle financing. Their philosophy is built on being upfront and incredibly transparent.
In a world where hidden fees can act like a financial leak, they are a breath of fresh air. They do not charge you for applications or for checking your credit. It is a refreshing approach that puts the borrower first rather than the bottom line.
If you are looking to refinance a car loan to free up some monthly breathing room, these folks are experts. It is simply a matter of local neighbors helping local neighbors get through the month. It feels personal because it actually is.
Pros:- Zero fees for credit checks or applications
- Strongly established with a local presence
- Adaptable options for car financing
- Regional focus may restrict access for those far away
OneMain Financial
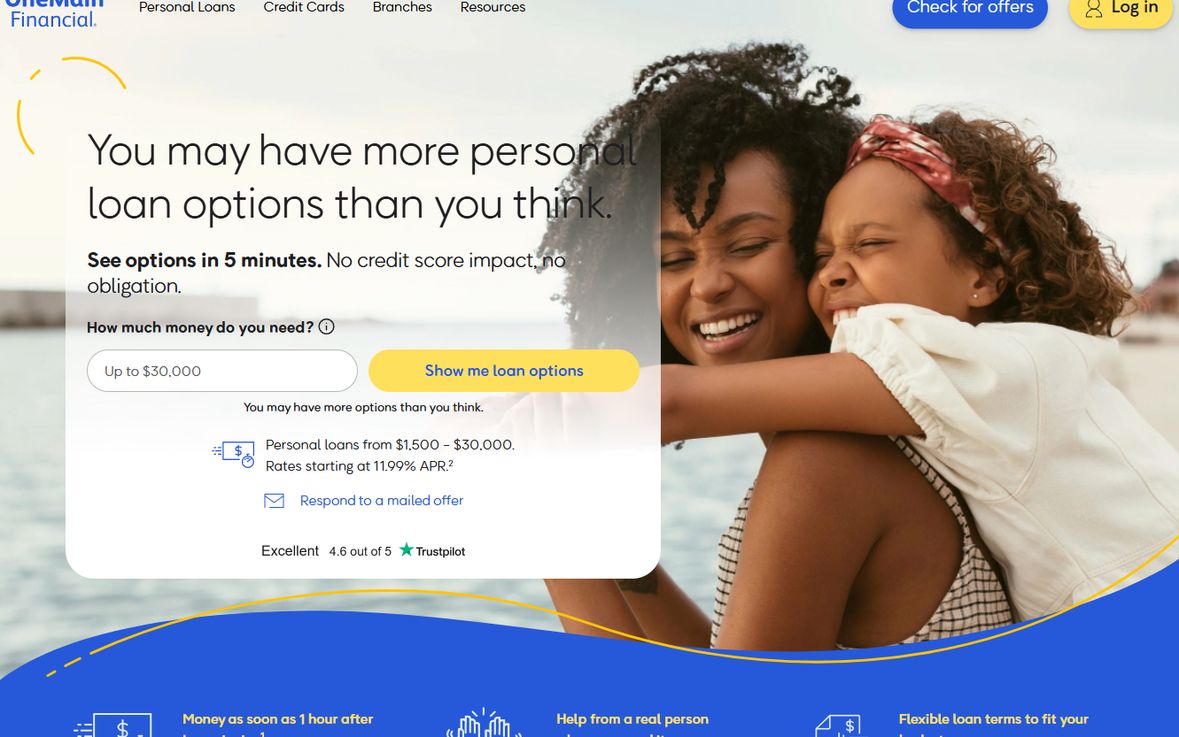
OneMain Financial is a heavyweight in the industry, striking a balance between high-tech convenience and traditional support. With a massive network of over 1,300 branches nationwide, they offer a safety net that purely online lenders can’t touch. You aren’t just stuck talking to an automated chatbot if things get messy.
This hybrid setup is a dream for people who want an easy app but also want the security of a physical office nearby. It provides a massive sense of peace of mind. If a weird complication pops up, a real human being is always available to help you navigate the storm.
Time is of the essence with their services, and they don’t play games. Some borrowers see their funds hit their accounts a mere hour after the paperwork is signed. It is built for speed and efficiency in those urgent moments.
Furthermore, their fixed monthly payments are a godsend for budgeting. Unlike variable-rate loans that can jump around like a startled deer when the market shifts, OneMain’s predictable terms help you plan your future with total confidence.
Pros:- Potential for incredibly rapid funding
- Predictable terms with fixed monthly installments
- Physical branch access for face-to-face help
- Interest rates can fluctuate widely based on credit profiles
CashUSA
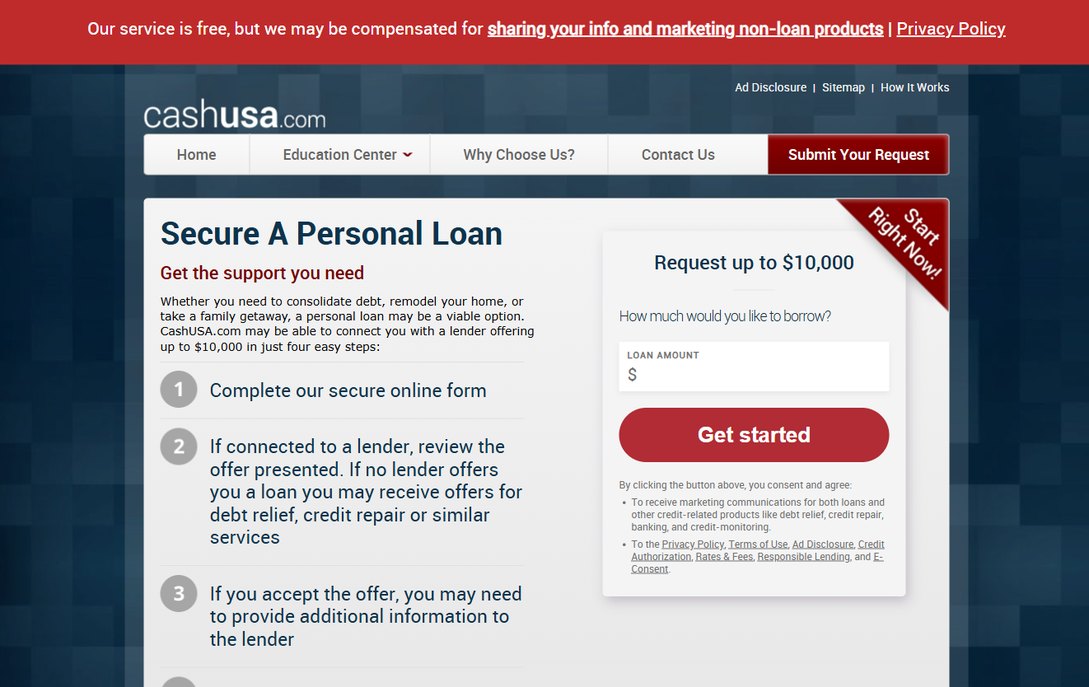
Think of CashUSA as a high-speed digital bridge. They specialize in connecting you with lenders for very specific needs, such as home remodeling or cleaning up old debt. They have stripped away the fluff to make the process as simple as possible.
It is a straightforward four-step dance: provide your details, look over the offers, pick a provider, and get your money. This streamlined workflow prevents the dreaded “analysis paralysis” that often hits when people are staring at a mountain of complex paperwork.
While they primarily focus on loans capped at $10,000, their real superpower is sheer velocity. If you find a match, the money could land in your bank account as early as the next business day. This is a lifesaver for sudden medical bills or emergency repairs.
Just keep one thing in mind: they are a marketplace, not the bank itself. While they do the heavy lifting of finding the options, the specific interest rates and rules are dictated by the individual lender that matches with you.
Pros:- Extremely simple four-step application
- Capability for next-day fund arrival
- Intuitive and modern digital interface
- Sometimes focuses on debt relief rather than direct lending
The Crucial Distinction Between APR and Interest Rates
Navigating the financial landscape in Fort Worth requires a sharp eye for detail, particularly when distinguishing between your interest rate and the Annual Percentage Rate (APR). It is a common pitfall for many residents to fixate solely on the interest rate, believing it represents the total price of their loan. In reality, that figure only covers the cost of the principal amount borrowed.
The APR, however, tells the real story of your debt. This comprehensive percentage incorporates the base interest rate along with various additional expenses, such as processing or origination fees. Think of it as the “all-in” price of your credit, ensuring you aren’t blindsided by hidden costs that sneak up on you during the application process.
Consider a scenario where a bank promises a 10% interest rate, but they tack on a 5% fee for origination at the start. Suddenly, that low percentage is a bit of a mirage; your true cost of borrowing—the APR—is much steeper. If you are weighing a local institution like Fort Worth City CU against a digital platform like CashUSA, the APR is your most honest guide for finding the most economical choice.
Don’t let a small monthly installment lure you into a trap. A lower monthly bill often stems from a stretched-out repayment schedule, which can force you to shell out much more in total interest over time. It is vital to gaze at the entire financial horizon rather than simply glancing at the single number displayed on your computer screen.
How to Land the Most Advantageous Loan Rates
Landing a loan isn’t merely about hunting down a simple “yes” from a banker. It is more about pinpointing the specific institution that offers conditions tailored to your unique financial profile. You want to strike gold with terms that work for your budget, not against it.
Think of it like shopping for a used car in Fort Worth. You wouldn’t just grab the first deal you see without looking under the hood. Taking a few proactive steps can drastically improve your odds of getting approved while keeping your interest expenses as low as possible.
If you walk into a room blindfolded, you’re bound to stumble. By following a strategic roadmap, you can navigate the complex lending landscape without getting burned by hidden fees or unnecessarily high rates that eat away at your monthly income.
- Audit Your Credit Standing: Before you start hitting that “apply” button, grab a free report to see where you stand. If you know your exact score, you can hunt for lenders that cater specifically to your credit bracket. This savvy move prevents your credit from taking a hit due to too many hard inquiries.
- Pinpoint Your Precise Funding Amount: Resist the temptation to over-borrow just because a lender makes the monthly installments look tiny. If a $2,000 mechanic bill is the problem, don’t grab a $5,000 loan. That extra cushion is essentially expensive fuel for interest, driving up your total debt significantly.
- Prepare Your Paperwork Early: To make sure the “fast funding” promises from providers such as OneMain Financial or JetzLoan actually manifest, stay ahead of the curve. Have your current pay stubs, identification, and bank statements sitting in a folder, ready to upload the moment they ask.
- Evaluate the Complete Cost: Never settle for just the APR; instead, demand a full breakdown of what you will pay back by the time the loan is fully satisfied. That final sum is the real story behind the contract, revealing the true price of the money you are borrowing.
Making Informed Borrowing Choices
Don’t let the shiny allure of a low monthly installment blind you to the real cost of borrowing. It is essential to peer closely at the total amount you will eventually pay back to the lender. Many companies hide sneaky origination fees or prepayment penalties within the dense legal jargon of your contract.
Watch out for those prepayment penalties specifically, as they act like a trap for proactive borrowers. These fees essentially punish you for being financially savvy and attempting to settle your debt before the term ends. You shouldn’t have to pay a premium simply for trying to get out from under your debt sooner than expected.
It is easy to fall into the trap of jumping at the first offer that lands in your inbox. Speed is often the bait used by lenders who charge much steeper interest rates than a local credit union might. Take a beat to sit down and compare the APR from at least two separate lenders before making a move.
A seemingly small gap of 2% or 3% in your APR might not feel like much on day one. However, over the lifespan of a multi-year loan, that tiny discrepancy can bleed thousands of dollars in extra interest from your pocket. It is better to spend an afternoon researching than to spend years paying for a cheap mistake.
One of the most frequent blunders involves losing sight of your actual monthly cash flow. Even if a bank is willing to hand you a massive pile of cash, you ought to borrow only what fits into your actual lifestyle. Taking on more than you can handle is a recipe for a financial headache that never quite goes away.
A solid guideline to follow involves looking at your gross monthly income and your total debt load. Your combined payments—this includes your new loan, student loans, and your vehicle payment—should ideally stay between 36% and 43% of your total income. Crossing that threshold can pull you into a slippery cycle of debt that is incredibly hard to climb out of.