Where to Secure Quick Bad Credit Loans New Jersey Residents Can Trust
Last updated: 2026-10-16
Unexpected expenses, like an urgent doctor’s visit or an auto repair, can feel like a sudden punch to the gut. For many people living in New Jersey, these financial hiccups arrive without warning, leaving a trail of mounting bills in their wake.
In these moments, you need a financial partner that prioritizes your actual income over a mere number on a credit report. It is about finding someone who evaluates your capacity to repay rather than just looking at your past mistakes.
From a sudden transmission failure in Newark to a startling dental bill in Jersey City, life moves fast. When a crisis strikes, the frantic urge to grab any available cash can cloud your judgment.
While solving the immediate fire is tempting, rushing into a bad agreement is like pouring gasoline on a small flame. It often results in much larger financial disasters later on.
Navigating the crowded market of lenders requires a steady hand and a clear head. You must balance the lightning-fast speed of some lenders, which often comes with a hefty price tag, against the slow but steady pace of conventional banking institutions.
Our selection aims to find that sweet spot for New Jerseyans with bruised credit. We want to help you find stability while navigating through these tricky waters.
It is vital to recognize that a structured medical payment arrangement is a world away from a high-interest installment loan. Confounding the two can trap you in a never-ending loop of interest and debt.
Please use the information below to scrutinize every detail before you ever pick up a pen. Making an informed decision today prevents a much heavier burden tomorrow.
- Max Cash
- FastLendGo
- XCEL Federal Credit Union
- Fulton Bank
- Loanz
- Cherry
- CareCredit
Comparing Lending Alternatives in the Garden State
Sifting through the various financial paths available can feel like navigating a dense fog. To find the right match for your current predicament, you must weigh several specific variables. Speed is often the primary concern for those facing an immediate crisis.
If you rely on a vehicle to commute across New Jersey, waiting several days for a fund transfer is simply not an option. In a state where movement is everything, time is your most precious commodity when a sudden bill arrives.
However, the long-term impact of what you borrow is what truly dictates your financial health. You cannot ignore the cumulative weight of interest rates or those pesky, hidden administrative costs. A lightning-fast loan becomes a heavy anchor if the monthly interest payments devour your entire salary.
We also scrutinized the level of adaptability these lenders show when your credit history is less than stellar. While some businesses lean into title loans for those lacking collateral, others focus purely on the healthcare sector. This spectrum spans from a modest $250 cash advance to a substantial $60,000 signature loan.
Our research looked into whether lenders prioritize your total income or your specific credit score. Generally speaking, your actual earning power and steady employment history are far more reliable indicators of stability than a single, static number on a report.
| Provider | Available Funding | Speed of Funds | Credit Standards |
|---|---|---|---|
| Max Cash | $250 – $10,000+ | Minutes | Bad Credit Options |
| FastLendGo | Small Loans Available | Quick Access | Bad Credit/No Credit |
| XCEL Federal Credit Union | $500 – $60,000 | See Site | Secured/Unsecured |
| Fulton Bank | See Site | See Site | See Site |
| Loanz | $100 – $10,000 | Quick/Convenient | See Site |
| Cherry | See Site | Instant Approval | High Approval Rate |
| CareCredit | See Site | Instant Decisions | Subject to Credit |
1. Max Cash
Think of Max Cash as a versatile toolkit for various financial emergencies. Their product list is wide, covering everything from $250 micro-advances to large-scale loans exceeding $10,000. This makes them an excellent safety net for those facing sudden, unexpected expenses.
A $500 injection might fix a washing machine, while larger amounts can cover essential home or vehicle repairs. Their system is engineered for maximum velocity. They cater to borrowers needing installment or title loans within a matter of minutes.
Because they are willing to work with individuals facing bad credit, they offer a lifeline that traditional big-box banks often deny. Just remember that when speed is the priority, you might see higher interest rates as a trade-off.
Pros:
- Rapidly processes applications for urgent needs.
- A diverse array of loan products, including title options.
- High accessibility for people with poor credit scores.
Cons:
- Using title loans requires collateral, putting your car at risk.
2. FastLendGo
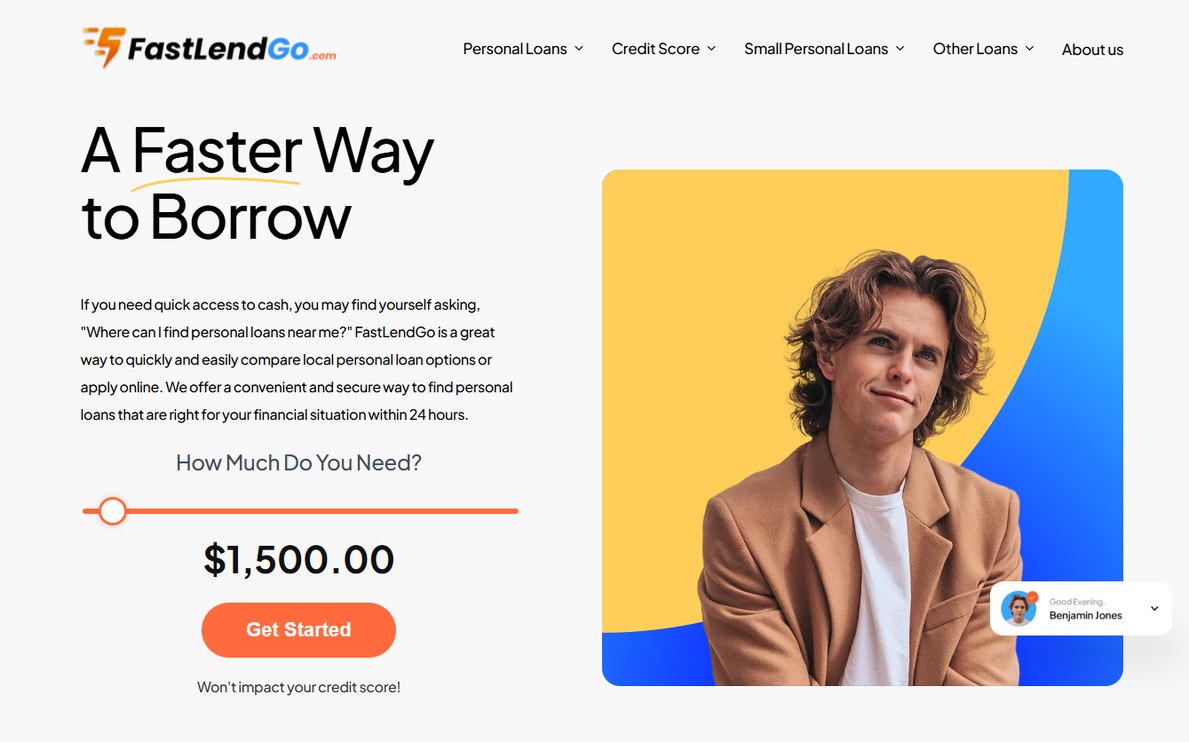
If you are looking for flexibility, FastLendGo provides a versatile way to manage personal financing. They don’t care if your credit is good, fair, or bad; they work across the entire spectrum. It is a much simpler alternative to driving between physical bank branches. (fastlendgo.com)
This lender is ideal for specific life hurdles, such as a sudden dental bill or a car repair. Instead of searching aimlessly for local loans, their digital platform streamlines the whole hunt. They pool various profiles to connect your specific score with a provider eager to see your application.
Pros:
- Provides funding for roof repairs or dental work.
- Accommodates users with no established credit history.
- Offers a streamlined online comparison tool.
Cons:
- Primarily operates as a comparison engine rather than a direct bank.
3. XCEL Federal Credit Union
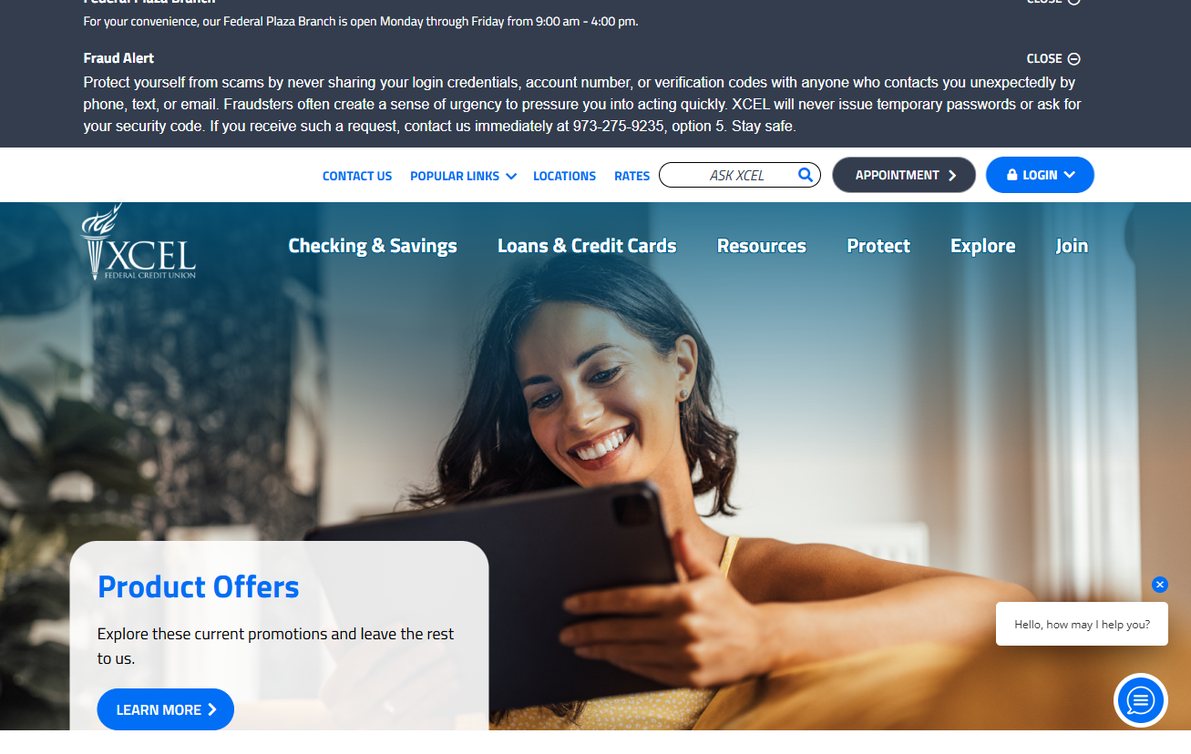
For those seeking traditional stability, XCEL Federal Credit Union offers both secured and signature loan options. Their funding ceiling reaches $60,000, providing a massive financial cushion for significant life transitions. These funds are perfect for debt consolidation, home renovations, or medical emergencies.
Because they are a credit union, the atmosphere feels more community-oriented than many predatory lenders. Since members own the institution rather than shareholders, the service often feels much more personal. You can choose between unsecured or secured paths to suit your needs.
Sometimes, using your savings account as collateral can help you unlock much more favorable interest rates. It is a smart way to balance risk and reward.
Pros:
- Extensive borrowing limits reaching up to $60,000.
- Secured loan availability helps lower your interest.
- A service model centered on the individual member.
Cons:
- Eligibility often depends on membership status.
4. Fulton Bank
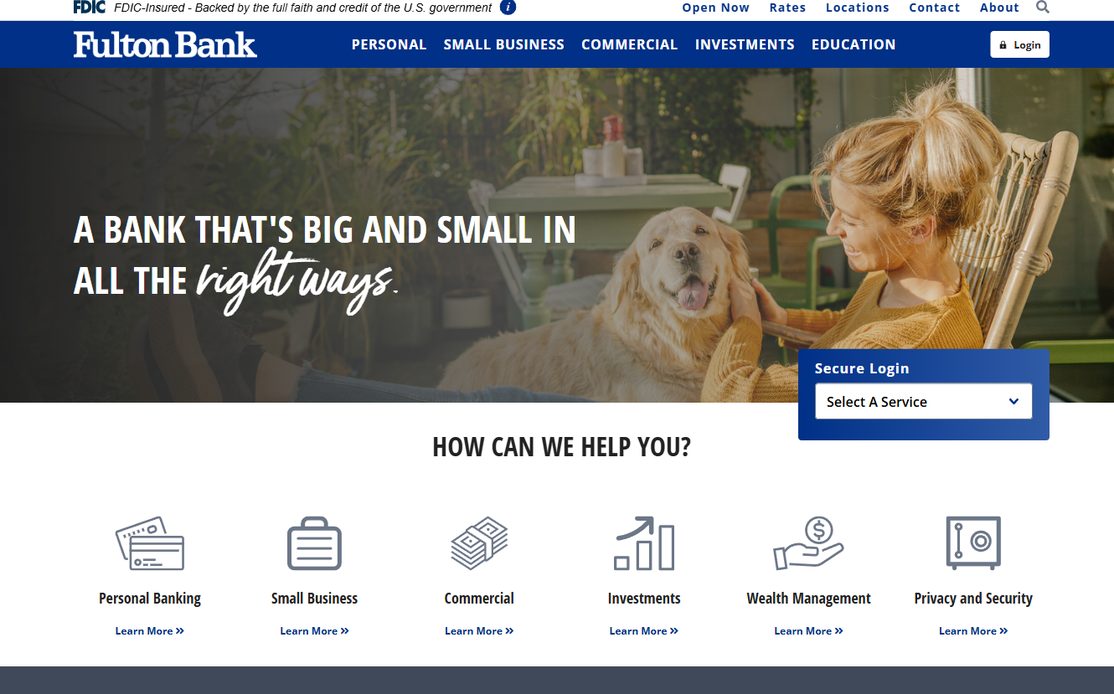
Fulton Bank stands as a heavy hitter for those living in New Jersey. They possess the massive resources of a large institution while maintaining a distinctly local presence. This makes them a reliable partner for long-term wealth management and complex financial goals spanning many years.
Their offerings range from standard personal banking to comprehensive commercial services. While they might not be the go-to for a quick $200 fix, they are exceptional for managing substantial investments or major wealth. Their enduring stability is a huge advantage if you want a lender that will be here for decades.
Pros:
- Features high-level security and FDIC insurance.
- Provides a wide range of personal and business services.
- Maintains a powerful footprint within the New Jersey area.
Cons:
- Criteria may be more stringent than niche bad credit lenders.
5. Loanz
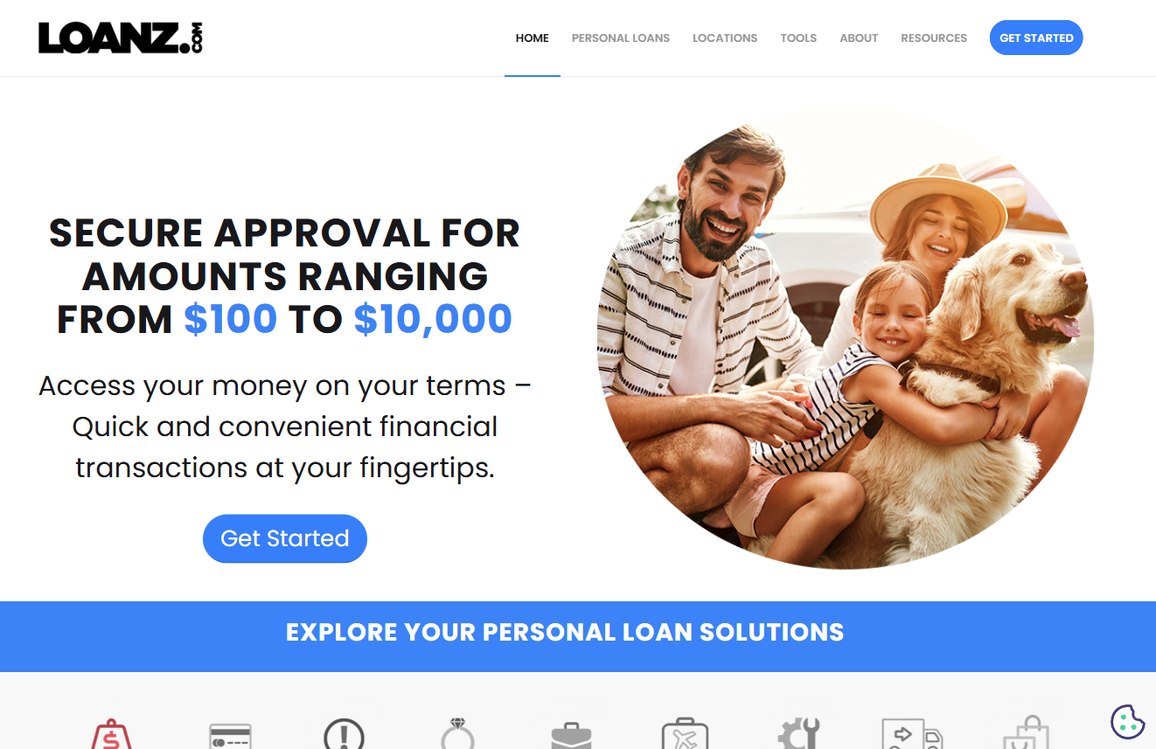
Loanz aims to help you reshape your future through tailored loan solutions. With amounts ranging from $100 to $10,000, they are a great fit for small debt consolidation tasks or upcoming expenses like weddings or moving. This approach helps you tackle small problems before they snowball into massive debt.
Their core mission is helping you reclaim control over your finances. Their consolidation products allow you to manage multiple various bills through a single window. Instead of juggling five different due dates, you can merge them into one monthly payment to ease your budget stress.
Pros:
- Very low entry threshold for small loans starting at $100.
- Dedicated products designed for debt consolidation.
- Offers convenient, digital-first transactions.
Cons:
- Loan ceilings are somewhat limited at $10,000.
6. Cherry
Cherry operates as a specialist in the realms of retail and healthcare finance. They boast a remarkable 90% approval rate and are a trusted partner for thousands of providers. Their primary goal is to ensure you can access essential services immediately without facing an upfront cost barrier.
The application itself is incredibly efficient, frequently completing in a mere 35 seconds. This makes it a top-tier choice for anyone needing urgent dental work or home improvements while wanting to spread out the expense. They integrate directly with your service provider to ensure a seamless experience.
Pros:
- An exceptionally fast application workflow.
- Maintains a very high consumer approval rate.
- Connects directly with a wide array of healthcare providers.
Cons:
- Availability is restricted to certain merchants and providers.
7. CareCredit
CareCredit is a specialized credit card designed specifically for the wellness and health industry. It is accepted at over 285,000 different locations, making it an incredibly versatile tool for medical costs. From vision care and dentistry to veterinary expenses, they have you covered.
One major benefit is the ability to check your prequalification without impacting your current credit score. This is essential for those who want to shop for medical care while protecting their standing. Many plans offer “no interest if paid in full” incentives, but proceed with caution—late payments can trigger retroactive interest.
Pros:
- Prequalification checks do not damage your credit score.
- An expansive network of participating locations.
- Highly flexible financing for all health-related needs.
Cons:
- Terms and approvals are subject to credit review.
Distinguishing Between Asset-Backed and Asset-Free Financing
Before diving into an application, you must grasp the fundamental distinction between secured and unsecured lending options. This specific classification alters your total risk profile significantly. When you opt for a secured loan, you are essentially putting something on the line, such as a vehicle, your residence, or perhaps a savings balance.
Because a lender holds a claim to that specific collateral if you fall behind on payments, they tend to be much more flexible with borrowers possessing lower credit scores. It is like providing a guarantee that makes them feel much safer about parting with their cash.
Secured loans frequently offer more favorable interest rates, but the personal stakes are considerably higher for you. For instance, if you neglect the payment schedule on a title loan, your car could be seized. You are essentially making a deal to trade your property’s safety for a cheaper monthly rate.
Unsecured loans, by contrast, operate without any physical collateral backing them up. This group encompasses the majority of credit cards and standard personal loans available today. Since there is no car for them to grab immediately if you default, these lenders demand higher interest rates and much better credit history.
The consequences of failing to pay an unsecured debt are different but still quite serious. While a lender cannot simply walk away with your house overnight, they do have the power to file lawsuits or pursue wage garnishment to get their money back.
Setting the Stage for Your Loan Approval
Walking into a loan application without a strategy is like sailing into a storm without a compass. You want to walk in with your head held high, knowing your finances are in shipshape condition. By taking a few proactive steps, you can boost your odds of securing a favorable interest rate.
It is also vital to protect your credit score from avoidable damage. Every time a lender takes a hard look at your history, your score might take a tiny dip. Being organized helps you navigate the process without any unexpected bumps in the road or sudden surprises.
Think of this phase as your pre-flight checklist. If you skip a step, the whole journey could go off the rails. Let’s break down exactly what you should do to prepare your finances before you hit that submit button.
- Validate Your Paperwork: Do not let a missing document stall your progress. Before you dive in, assemble your most recent bank statements, identification, and your latest pay stubs. If you intend to pledge an asset as collateral, ensure you have the legal paperwork proving you are the rightful owner.
- Assess Your Debt-to-Income (DTI) Ratio: Lenders act like detectives, scrutinizing how much of your monthly paycheck is already spoken for by existing debts. A heavy DTI can be a dealbreaker. Consider chipping away at those small balances to lighten your load before you officially apply.
- Scan Your Credit Report for Mistakes: A single clerical error regarding a late payment can act like a weight around your neck, dragging your score down. Use a free service to hunt for inaccuracies. It is much better to fix those errors now than to fight them later.
- Evaluate Total APRs Instead of Just Interest: Do not get blinded by a low interest rate alone. The Annual Percentage Rate (APR) tells the real story because it factors in mandatory fees. For example, a 12% interest rate with zero fees is often cheaper than a 10% rate that carries a $500 fee.
- Leverage Prequalification Options: Look for lenders that utilize “soft pulls” to check your eligibility. This clever method allows you to scout estimated rates without leaving a permanent scar on your credit report. It is a low-risk way to shop around effectively.
Steering Clear of Costly Money Traps
When you are hunting for quick cash, don’t just grab the nearest hand reaching out to help. It is vital to scrutinize the legal jargon tucked away in those contracts. I’ve seen many folks fall into a hole by rushing into high-interest agreements just to save time.
This impulsive decision often leads to a punishing cycle of debt. Before you know it, the extra interest you’ve accrued ends up dwarfing the initial sum you actually needed. It feels like you are running on a treadmill that only moves faster as you get more tired.
You really need to keep a sharp eye on the overall price tag of your borrowing. A low monthly installment can be a wolf in sheep’s clothing. It might look manageable, but it often masks an incredibly extended repayment timeline.
For example, consider a $5,000 loan where the monthly bill is only $100. That sounds like a walk in the park until you realize you’ll be stuck paying that off for seven years. That extra time adds up to a mountain of wasted cash.
Another blunder to sidestep is bombarding lenders with applications all at once. Each time a bank pulls your credit, they trigger a “hard inquiry.” This specific action can drag your credit score through the mud quite quickly.
If you suddenly apply for five different loans in a single week, banks will start smelling desperation. They might view you as a high-risk borrower who is drowning in debt. It’s much wiser to test the waters with prequalification tools first.
Using these preliminary tools lets you filter your options without damaging your standing. Narrow down your list of potential lenders before you make any formal, official moves. This approach keeps your credit profile looking healthy and stable.
Comments
One response to “Where to Secure Quick Bad Credit Loans New Jersey Residents Can Trust”
[…] Bad Credit Loans New Jersey […]