Top-Rated Bad Credit Loans Illinois: Compare Today’s Best Offers
Last updated: 2026-10-16
Navigating a sudden money shortage while battling a low credit score can feel like hitting a concrete wall at full speed. For residents living in Illinois, these fiscal crises frequently arrive without warning. It doesn’t matter if you reside in bustling Chicago or the sleepy outskirts of Cook County; the clock is always ticking.
Life has a funny way of throwing curveballs, like a massive hospital invoice or a mechanic’s daunting estimate. These emergencies are indifferent to your past credit mishaps. Whether you are located in the suburbs or downstate, the pressure to find quick cash remains a common struggle.
Big banks often play it safe, closing their doors when your financial history looks a bit bruised. If you have accumulated significant debt or skipped past payments, you might find them quite aloof. This creates a massive void for many people who lack a traditional safety net.
You eventually realize that solving your crisis requires finding a lender who sees the person behind the digits. Relying on a single number can leave you stranded when you are truly in a pinch. You need a partner that evaluates your whole situation, not just a score.
Don’t get blinded by a quick “yes” when browsing your options. It is vital to investigate how fast the funds actually arrive in your pocket. You must also scrutinize the true price of the capital you are borrowing.
A tiny monthly installment might seem like a dream, but extended repayment periods can be a trap. You could end up paying twice your original loan amount if you aren’t careful. Our curated list identifies the most trustworthy sources for Illinois citizens seeking a financial lifeline.
- IllinoisLoansToday
- Tower Loan
- OppLoans
- SAIL Loans
- AmeriCash Loans
- Reprise
- OneMain Financial
Comparing Local Borrowing Alternatives
Our team prioritized two main pillars: ease of access and clarity of terms. We investigated whether every provider permits a soft inquiry during the initial phase. A hard pull can certainly bruise your rating, which is the absolute last thing a person needs while digging themselves out of a financial pit.
Securing options that leave your score untouched is essential. Protecting your fiscal well-being means being picky about where you cast your net. It is a game of inches, and every single point counts when you are trying to rebuild your standing.
Even one rejected application can act like a weight on your future. Applying for a loan you never intend to sign could potentially sabotage your chances of securing a mortgage or vehicle financing later. It is a minor oversight that triggers major headaches down the line.
We also scrutinized the velocity of fund distribution and the variety of available sums. Some companies specialize in tiny, rapid cash infusions meant for temporary emergencies. Others are geared toward heavier lifting, such as renovating your house or wiping out expensive credit card debt.
Our mission was to track down services that provide versatility for residents across the Land of Lincoln. We wanted to identify which providers truly cater to those facing genuine, everyday hardships. This side-by-side look removes the guesswork from your decision-making process.
Whether your wallet needs $500 for the weekly grocery run or $15,000 to fix a leaking roof, a path usually exists. There is almost always a way forward if you know where to look. We simply wanted to see who provides the most avenues for those in need.
| Provider | Funding Range | Credit Standards | Payout Speed |
|---|---|---|---|
| IllinoisLoansToday | $500 – $50,000 | No credit score impact | Minutes |
| Tower Loan | See site | Established credit required | See site |
| OppLoans | $500 – $5,000 | Does not affect FICO score | Same-day funding |
| SAIL Loans | Up to $4,000 | Builds credit history | Quick approval |
| AmeriCash Loans | See site | No credit check | Same day |
| Reprise | See site | See site | See site |
| OneMain Financial | $1,500 – $30,000 | See site | As soon as 1 hour |
Leading Lending Solutions for Illinois Borrowers
1. IllinoisLoansToday
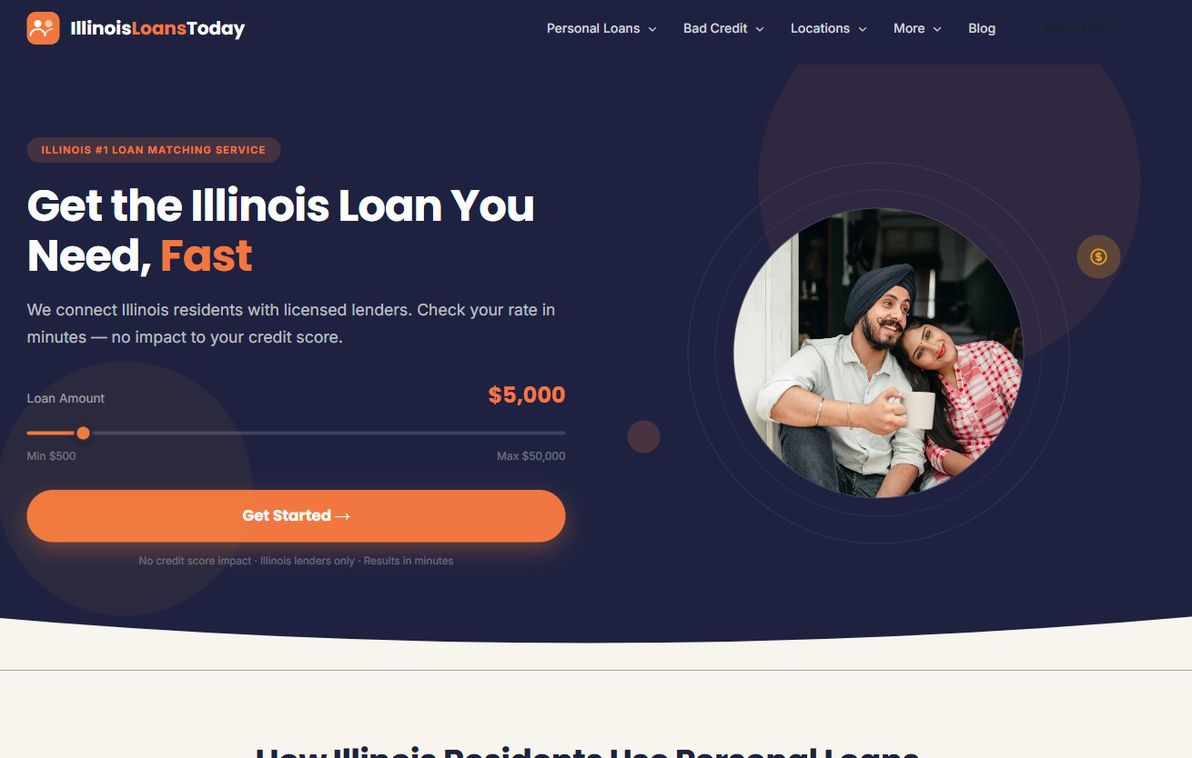
Operating much like a digital matchmaker, this platform scans the horizon for you across the state. Rather than wasting precious energy knocking on dozens of doors, you are introduced to licensed specialists who cater to various credit profiles. It is a massive time-saver when your clock is ticking loudly. Think of it like an urgent mechanic visit to get your car running for Monday’s commute.
This resource proves vital when unexpected bills, such as a broken HVAC unit or medical emergencies, demand immediate attention. Because the system connects you with a broad spectrum of providers, you aren’t tethered to the rigid terms of a single institution. You get a clear view of your available options. Since the preliminary lookup won’t touch your credit score, you can browse without any anxiety.
Pros:
- Funding ranges from $500 to $50,000
- Rate inquiries won’t impact your credit score
- Addresses various needs like moving costs or debt consolidation
Cons:
- Availability depends on third-party lender stock
2. Tower Loan
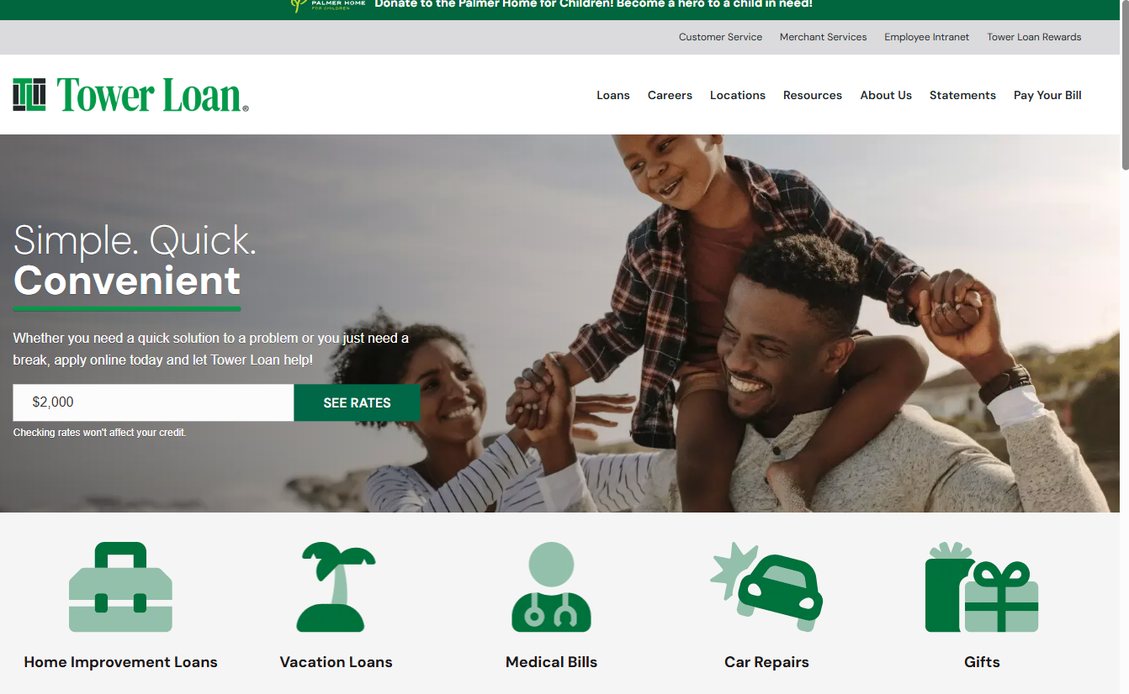
A household name in the industry, Tower Loan provides a variety of personal and installment loan structures. Whether you are planning a vacation, fixing up your home, or seeking auto-secured loans, they have a seat at the table. Choosing an auto-secured loan can often unlock more favorable interest rates. This occurs because your vehicle serves as collateral, providing the lender with extra security.
Keep in mind that a documented credit history is a prerequisite for their approval. This makes them a great fit for someone whose score has hit a rough patch but who still maintains a track record of managing debt. If a single late payment caused a temporary dip, but your paycheck remains steady, Tower Loan might be your best bet.
Pros:
- Diverse loan types including auto-secured options
- Multiple physical locations throughout Illinois
- A long-standing and reputable brand
Cons:
- Must have an established credit history to qualify
3. OppLoans
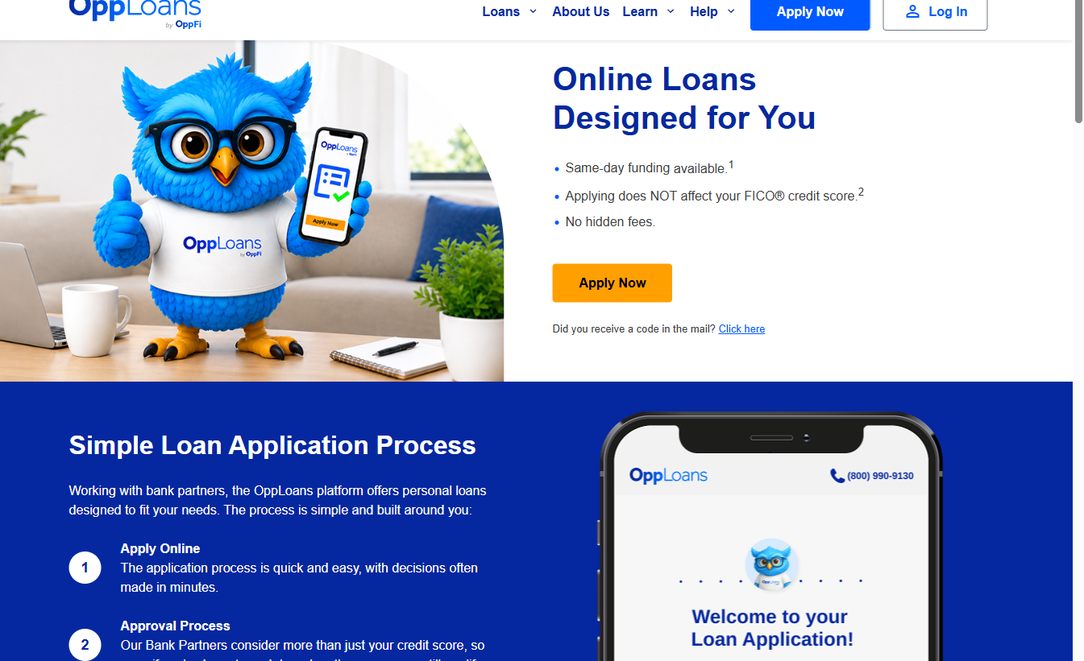
OppLoans utilizes a unique methodology that looks far beyond the mere numbers on a standard credit report. By collaborating with bank partners, they create a gateway for individuals who might be turned down elsewhere. Their proprietary algorithm prioritizes your income stability and repayment capacity over a simple FICO score.
The application workflow is remarkably streamlined and incredibly fast. You can often receive a decision in a matter of minutes. When life throws a curveball, receiving funds within the same business day can be a total game-changer. This is particularly useful for covering rent or utility bills to avoid mounting late fees and extra stress.
Pros:
- Same-day funding for approved applicants
- Applying has no impact on your FICO score
- A transparent process with no hidden fees
Cons:
- Borrowing amounts are restricted to a $5,000 maximum
4. SAIL Loans
SAIL Loans takes a refreshing angle by prioritizing your long-term credit health. Their installment loan products are built to provide immediate liquidity while simultaneously polishing your financial reputation for the future. It is essentially a two-fold solution for those living paycheck to paycheck. It acts as a bridge between high-interest debt cycles and true financial stability.
They provide rapid approval for those seeking up to $4,000. By utilizing these specific tools, borrowers can address an urgent cash need while actively working on their overall financial wellness. This is perfect if you need a small financial cushion for this month while preparing to finance much larger purchases down the road.
Pros:
- Promotes credit history growth and savings
- Quick and secure online application process
- Installment loans available up to $4,000
Cons:
- The credit-building focus may not suit those seeking massive lump sums
5. AmeriCash Loans
AmeriCash Loans serves as a rapid-response mechanism for your short-term cash requirements. They operate under the motto “money today, momentum tomorrow.” Their marketplace structure allows you to broadcast your information to various lenders to see who is ready to help. This approach maximizes your chances of finding a partner that aligns with your unique credit profile.
Everything about their system is designed for high speed, often resulting in instant approval decisions. Since many of their installment loans do not demand a strict credit check, they are a common refuge for people in high-pressure financial moments. You won’t find yourself waiting days for a bank’s verdict when you need cash immediately.
Pros:
- Rapid application with instant approval decisions
- Many options do not require a credit check
- Cash can be available on the same day
Cons:
- The marketplace model sends you to different lenders
6. Reprise
Reprise functions as a niche platform that specializes in high-level demo generation and artificial intelligence tools. While it might seem like an outlier in this list, it stands out due to its sheer technical precision. It represents the cutting edge of SaaS evolution, helping modern businesses communicate incredibly complex technical ideas.
Their toolkit allows users to build high-fidelity product tours that utilize injected data. This is a completely different animal than personal lending. Instead of helping individuals manage debt, it caters to the professional enterprise sector. For a tech-savvy pro, this is a productivity powerhouse rather than a financial lifeline for personal expenses.
Pros:
- Sophisticated AI tools for creating demos
- Excellent at managing complex data payloads
- Seamlessly shares interactive product tours
Cons:
- Not intended as a personal loan provider
7. OneMain Financial
OneMain Financial is a massive player in the personal lending arena. They provide substantial capital for those who need significant support. With loan amounts spanning from $1,500 all the way up to $30,000, they are a prime choice for large-scale needs. This includes things like debt consolidation, medical bills, or major car repairs requiring a large upfront sum.
Their business model blends digital ease with the comfort of human interaction. With a presence of over 1,300 branches nationwide, they offer something many online lenders cannot. If you want to sit down with a real person to talk through a repayment plan or your budget, their physical branches are a major asset.
Pros:
- High borrowing limits up to $30,000
- Predictable monthly payments for budgeting
- Physical branch access for face-to-face help
Cons:
- Approval criteria are more stringent than payday lenders
Calculating Your Actual Debt Burden
When life throws a curveball and your bank account runs dry, it is easy to let desperation drive the car. In those frantic moments, distinguishing between a basic interest rate and the Annual Percentage Rate (APR) becomes vital. Think of the APR as the real truth-teller in a room full of exaggerations.
While a simple interest rate only tells part of the story, the APR provides the full, unvarnished picture. This figure incorporates the interest itself alongside any compulsory costs, such as processing or origination fees. Relying solely on the interest rate is like checking the price of a car without looking at the registration fees.
Consider this scenario: you might find a loan boasting a 15% interest rate, but once those pesky administrative charges are baked in, the APR could jump to 19%. Always keep your eyes glued to that APR figure. It serves as the only honest price tag for the capital you are acquiring from a financier.
The duration of your repayment schedule also plays a massive role in your final bill. If you borrow $1,000 for a quick three-month sprint, your total interest expense will be significantly lighter than if you stretched that same $1,000 over a full year. Time is essentially a multiplier for your debt.
Even if a twelve-month plan keeps your monthly outlays feeling light and easy, the cumulative cost is much heavier. It is a classic trap that many fall into when trying to keep their head above water. You must weigh the convenience of small payments against the growing mountain of interest.
Take a moment to pause and ask: can your wallet survive if your paycheck takes a hit next month? If the thought makes you sweat, you might be biting off more than you can chew. It might be wiser to seek a smaller amount or a more adaptable repayment plan.
Preparing for a rainy day is the only way to prevent a total financial washout later. By choosing a structure that allows for flexibility, you protect yourself from the crushing weight of unexpected circumstances. Planning for the absolute worst-case scenario is your best defense against future catastrophe.
Effective Methods for Handling Urgent Borrowing
When you find yourself relying on an emergency loan, treat it as a lifeline to steady your ship rather than an anchor dragging you down. It is vital to use these funds to restore stability to your daily life. Managing such financial burdens requires a strategic mindset to keep the situation from spiraling out of control.
Think of your debt as a wildfire that needs containment. If you decide to consolidate existing obligations, the new interest rate must be substantially less than what you are currently paying. If you are clearing a credit card balance with a loan, resist the urge to swipe that card again. Falling into that trap essentially means you have doubled your financial problems.
Another smart move is to let technology handle your schedule by setting up automatic transfers. Missing a deadline can trigger late fees that bite hard when your budget is already stretched thin. Interestingly, some lenders actually reward you with minor discounts for opting into automatic payment systems, which helps your bottom line in the long run.
If your sudden expenses involve medical bills, do not panic immediately. Start by reaching out to the billing office at your hospital. In Illinois, various healthcare facilities provide interest-free payment schemes or significant price reductions for patients undergoing genuine financial struggles. A quick phone call could save you a mountain of stress.
Once the immediate storm has passed, focus on constructing a small safety net. Even a modest habit, such as setting aside $25 every month, can eventually grow large enough to handle a minor car repair. This small buffer acts as a shield, ensuring you won’t need to hunt for high-interest loans when life throws a curveball.
Approaching the borrowing process is a tightrope walk between needing speed and needing caution. It is incredibly tempting to rush into a deal when an instant approval is on the table. However, you must scrutinize the fine print before signing your name. The real cost of that cash is revealed in the APR and the total amount you must eventually repay.
Falling into the trap of borrowing simply because the application is easy is a dangerous game. Using a new loan to pay off an old one only makes sense if the interest rate is actually lower. Borrowing more money just to satisfy a previous debt is a downward spiral that is hard to escape. Use credit as a sturdy foundation, not a temporary bandage on a deep wound.
Many people make the mistake of not shopping around for the best terms. A rejection from one lender is far from the end of the road; another provider might be ready to say yes. Take advantage of “no impact” credit checks offered by many modern lenders to compare options without hurting your score. This little extra effort can save you thousands of dollars over time.
Leave a Reply