Best Rates for Personal Loans for Low Income Individuals Now
Last updated: 2026-10-16
When your monthly earnings barely scrape the surface of your essential needs, finding any sort of financial breathing room can feel like a losing battle. You might find yourself staring down a massive pile of invoices, desperately searching for a lifeline that doesn’t demand a flawless credit history. It is an incredibly heavy weight to carry.
Life has a nasty habit of throwing curveballs that can wreck even the most disciplined budget in a heartbeat. Perhaps your car’s transmission decides to quit, or a sudden medical bill arrives out of nowhere. Even a simple seasonal jump in your electric bill can knock you completely off course when funds are scarce.
In those moments of scarcity, you require financial solutions that actually align with your unique circumstances. When you are hunting for a way to stay afloat, ignore the glossy advertisements. You must prioritize understanding exactly how quickly cash hits your bank account and what the full cost of borrowing truly entails.
Will a simple rate inquiry cause your credit score to plummet? The line between a useful resource and a crushing debt trap usually hides within the repayment schedules and the Annual Percentage Rate (APR). Knowing these details is vital before you sign anything.
Our compilation highlights specific lenders that provide accessible avenues for people whom major banks often ignore. We have gathered a diverse array of choices, from rapid-response emergency cash to more structured tools designed for consolidating existing debt.
- JetzLoan
- Best Egg
- Avant
- OneMain Financial
- OppLoans
Our Vetting Methodology
When we began hunting for the best options, we kept a sharp eye on how these firms treat people facing financial hurdles. We didn’t want to just list names; we wanted to find true lifelines. Our team prioritized companies that offer lightning-fast decisions to get you back on your feet.
It is a real headache when you can’t even see your options without hurting your score. Because of this, we hunted for lenders that avoid the dreaded hard credit pull during the initial phase. You deserve a conversation with a real human, not just a cold, automated rejection letter.
We dug deep into their customer support quality and whether their fee schedules are written in plain English. A hidden cost is like a leak in a bucket; it drains your resources when you are most vulnerable. We vetted how they accommodate diverse credit histories to ensure they serve everyone fairly.
Transparency isn’t some optional extra; it’s the bedrock of any decent financial relationship. We searched for clarity because when your budget is tight, every single cent counts. We want you to know exactly where you stand from the very first click.
Time is often the most precious commodity for anyone living paycheck to paycheck. Waiting two weeks for a bank transfer is simply out of the question when an emergency strikes. We focused heavily on providers that move mountains to deliver funds quickly.
Whether it takes a full day or just a few hours, speed was a non-negotiable factor for us. We looked for that “same business day” magic to ensure help actually arrives when the pressure is on. Waiting ten days is a luxury that low-income earners simply do not have.
Finally, we prioritized the “soft inquiry” approach to protect your financial future. This mechanism lets you window-shop for the lowest rates without denting your credit score. It is a vital tool for anyone trying to safeguard their credit health while hunting for better terms.
| Company | Borrowing Limits | Payout Velocity | Credit Score Effect |
|---|---|---|---|
| JetzLoan | $500 – $35,000 | Within 24 hours | No hard credit pull |
| Best Egg | Up to $50,000 | Refer to website | Refer to website |
| Avant | Refer to website | Refer to website | |
| OneMain Financial | $1,500 – $30,000 | Starting at 1 hour | No credit score impact |
| OppLoans | Refer to website | Same-day options available | Does not affect FICO score |
Leading Lenders for Accessible Borrowing
1. JetzLoan
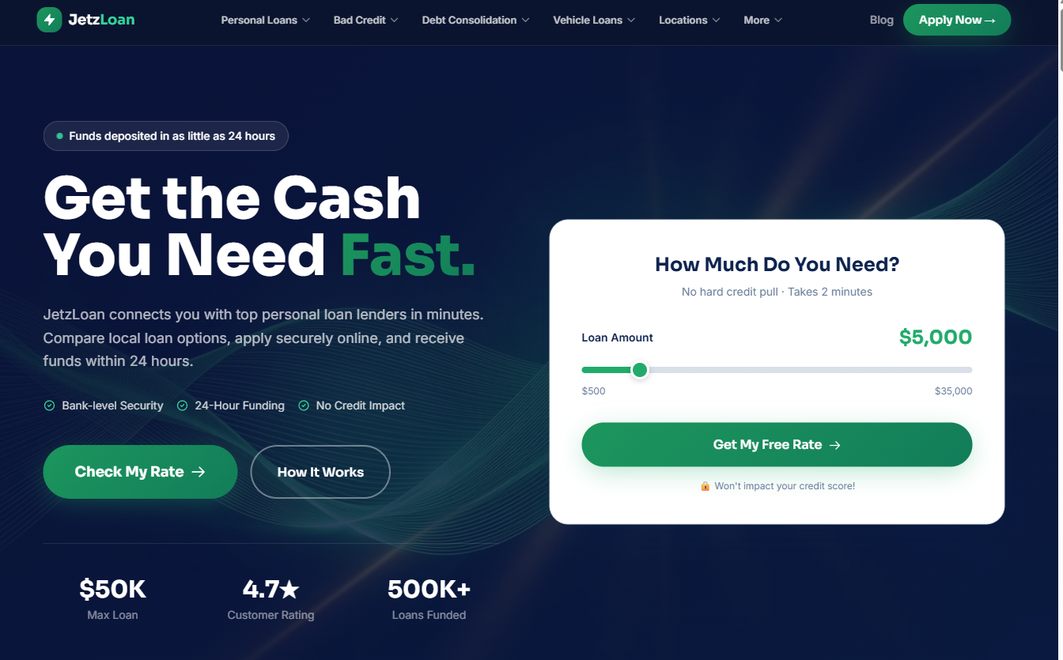
JetzLoan acts as a rapid bridge between you and a wide array of premier lenders in merely a few minutes. This platform is engineered for pure velocity and ease of use. It serves as a powerful tool for anyone racing to consolidate debt or quickly settle a car loan.
The entire procedure is stripped down to remove unnecessary tension. By adopting a digital-first mindset, they cater to those who simply cannot afford to wait on the slow gears of traditional banking. You can visit them at jetzloan.com to get started.
If your credit score makes you feel a bit shaky, this service might be your best friend. They allow you to scout different rates through a soft check, meaning your score remains untouched during the comparison phase. This pre-qualification step is a total game-changer.
Before you ever sign a formal contract, you will know your potential interest rates and the length of your terms. They have carved out a reliable niche in a very busy market. With a 4.7-star rating and a track record of over 500,000 loans funded, they truly understand the drill.
Pros:
- Checking rates won’t impact your credit score
- Cash can arrive in as little as 24 hours
- Loan amounts reaching up to $35,000
Cons:
- Maximum loan cap is set at $35,000
2. Best Egg
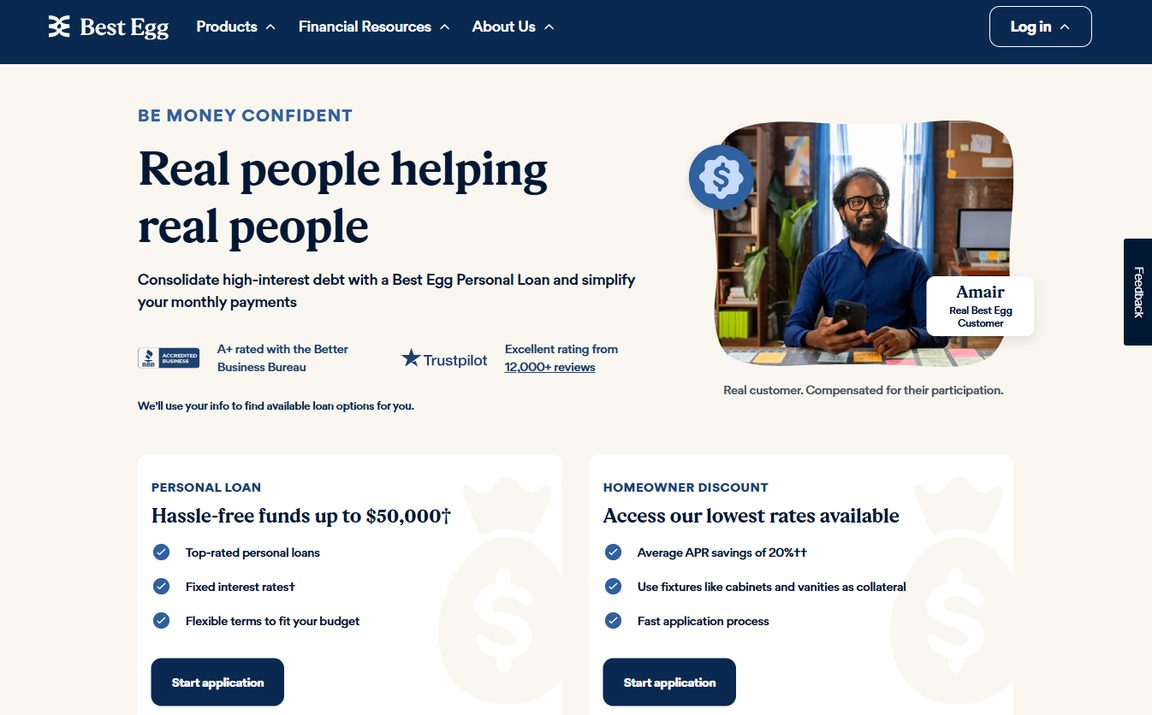
In the vast landscape of personal financing, Best Egg is a heavyweight contender. They have earned a reputation for helping people sweep away high-interest debt. Their primary mission is to streamline your monthly financial obligations into a single, easy-to-manage payment.
Imagine turning a messy mountain of various credit card balances or expensive medical bills into one tidy, predictable chunk. This consolidation often unlocks lower interest rates than your current individual cards. It is like cleaning up a cluttered room to find your peace of mind.
This strategy can lead to massive long-term savings and a much faster trek toward being debt-free. Their trustworthiness is backed by an A+ rating from the Better Business Bureau and thousands of satisfied customers. They aren’t just a name; they are a proven entity.
Homeowners might find extra perks here by using assets like vanities or cabinets as collateral to snag even better rates. However, most people simply utilize their standard unsecured loan options. It is a more disciplined way to borrow, perfect for those seeking a long-term financial roadmap rather than a temporary bandage.
Pros:
- High borrowing limits up to $50,000
- Top-tier BBB rating
- Special rates may be available for homeowners
Cons:
- Application process requires detailed documentation
3. Avant
Avant operates on the principle that no two financial paths are exactly the same. They offer a versatile toolkit, ranging from installment loans to credit cards. Their entire suite of services is built to help you move forward, regardless of where you are starting from.
Whether you are facing a sudden emergency or looking to upgrade your kitchen, they aim to provide options that actually fit your lifestyle. They don’t rely on the rigid, “yes or no” automated scoring used by old-school banks. Instead, they try to see the full picture of your financial health.
By acting more like a partner than a cold institution, they offer flexible paths for those who find traditional banking a bit of a struggle. This makes them a great pick for people who need a specific tool, like debt consolidation, rather than a generic product.
Their digital platform is designed for anyone tired of hunting for answers to tough financial questions. You get a smooth online experience that cuts through the mountain of paperwork usually found in this industry. It is built for the modern era where people want quick answers, not endless forms.
Pros:
- Variety of credit card and loan choices
- Tailored for different stages of life
- Dedicated to your financial progress
Cons:
- Specific eligibility requirements can be vague
4. OneMain Financial
If you find digital apps a bit cold, OneMain Financial is a breath of fresh air. With a massive network of over 1,300 physical branches, you can sit down and talk to a real person. This human connection is a lifeline when you are staring at confusing legal terms.
Sometimes, your life has nuances that a computer algorithm might simply miss. Having a local branch provides a sense of security for those who want to handle their money face-to-face. It turns a stressful transaction into a conversation between people.
The speed of their operations is truly remarkable. You could potentially have your funds in hand just one hour after signing the paperwork. They offer loans from $1,500 to $30,000 with fixed monthly installments, which makes budgeting much easier for families on tight schedules.
Knowing exactly what will leave your bank account every month provides a vital sense of predictability. It is an excellent choice for urgent needs like a sudden car repair or a broken water heater. You can walk in, talk through your options, and get back to your day.
Pros:
- Wide network of branches for in-person support
- Extremely rapid funding after signing
- Predictable payments for 24 to 60 months
Cons:
- Interest rates can fluctuate quite a bit
5. OppLoans
OppLoans operates on the belief that a single FICO number shouldn’t define your entire future. Their lending partners look past that one number to examine your income stability and employment history. This opens doors for people who might have been rejected elsewhere due to temporary setbacks.
Life happens, and if you have dealt with a medical crisis or a period of unemployment, they might still be willing to help. They focus on providing a practical way to get cash without being tripped up by hidden fees or confusing fine print. It’s straightforward and honest.
The application is incredibly fast, often delivering a decision within a matter of minutes. If you get the green light, the money could land in your bank account as early as that very same business day. It is built for those high-speed moments when every hour counts.
Whether you are trying to keep the lights on or bridge a gap in living expenses, they offer quick relief. Because they are transparent about their costs, you won’t be blindsided by the total price of your loan. It is a high-velocity option for pressing, real-world needs.
Pros:
- Possible to receive funds the same day
- Applying won’t damage your credit score
- No sneaky or hidden fees
Cons:
- Might not be the best choice for long-term debt
Calculating the Real Price of Your Debt
When money is tight and the pressure is on, most people tend to fixate on the interest rate alone. It is a common mistake that can lead to a massive headache down the road. You shouldn’t just look at the headline number; you need to look at the big picture.
It is vital that you learn the difference between a standard interest rate and the APR. While interest rates sound simple, the APR tells the real story by bundling in extra charges. These often include pesky things like processing or origination fees that add up quickly.
Think of it this way: a 10% interest rate looks manageable on paper. However, if a $2,000 loan comes saddled with a $300 origination fee, your APR jumps through the roof. You aren’t just paying for the money; you’re paying for the privilege of getting it.
To truly see how this hits your wallet, try running a “monthly impact test” before signing any contracts. Simply take your monthly installment amount and multiply it by the total number of months you will be paying. Once you have that total, subtract the original amount you actually received.
The final number you are left with represents the true cost of the loan in cold, hard cash. Let’s say you grab $2,000 to fix a broken car, but the math shows you’ll fork over $600 in interest over time. You have to decide if your budget can actually swallow that extra expense.
Navigating these numbers carefully is the only way to avoid falling into a vicious “debt trap.” If you aren’t careful, you might find yourself spinning your wheels, working every single day just to cover the interest on old loans. Don’t let your paycheck disappear into a bottomless pit of interest payments.
Mistakes to Steer Clear Of During the Application Process
It is incredibly easy to fall into the trap of over-borrowing. You might feel like you should grab every dollar a lender offers just because it is available. For example, you might find yourself signing for a $5,000 loan when the actual need was only for $3,500.
The catch is that a larger principal directly translates to a heavier monthly burden. If your paycheck varies from week to week, this extra weight can become an anchor. You could quickly find yourself caught in a downward spiral of debt that is incredibly difficult to break.
Before you sign on the dotted line, ensure your budget has a little wiggle room. I always tell people to build a safety net for those sudden, annoying surprises like a car repair. You never want your loan installment to collide with your utility bills.
Navigating Credit Checks and Debt Traps
Watch out for the distinction between different types of credit inquiries. Many services allow you to peek at your potential rates using a “soft pull,” which is harmless to your standing. However, once you officially commit, the lender performs a “hard inquiry.”
This formal investigation into your credit history can cause your score to drop momentarily. Think of it as a heavy toll you pay for accessing deep financial data. Make sure you are absolutely sure about the contract before you transition from browsing to signing.
Finally, stay away from the dangerous habit of rolling over short-term debts. Many people think they are just delaying the inevitable, but they are actually making a mountain out of a molehill. It is a deceptive tactic that turns small issues into massive crises.
It feels like you are keeping your head above water, but the truth is much darker. In reality, you are just sinking a bit more slowly each month. Avoid these cycles to keep your financial future bright and stable.
Leave a Reply