Top-Rated Bad Credit Loans Texas Providers for Fast Online Approval
Last updated: 2026-10-17
Navigating the financial landscape of the Lone Star State often feels like sailing through a heavy fog without a compass. If your credit score has taken a hit, searching for a reliable lender becomes a grueling uphill climb rather than a simple errand. You aren’t just looking for a quick infusion of cash; you are hunting for a safety net that won’t snap under pressure.
The weight of a broken transmission in Houston or a surprise hospital invoice in Dallas can feel overwhelming. When the walls are closing in, the urge to jump at the nearest loan offer is incredibly strong. However, you need an option that truly eases the burden instead of throwing more fuel onto the fire.
This compilation serves Texans grappling with sudden emergencies, ranging from automotive fixes to healthcare costs. Finding a solid lender means looking deep beneath the shiny marketing to discover real reliability. We searched for organizations that value clarity and ease of access, helping you regain your footing without sinking into a pit of debt.
As the price of living swings wildly between the sprawling metro areas and the quiet rural stretches, staying informed is your strongest shield. Learning to read the small print is your best defense against shady lenders who prey on people in desperate situations. Staying educated is the most effective way to keep your bank account in the green.
- Texas Bay Credit Union
- Solarity Credit Union
- TexasLoansToday
- Wisetack
Our Process for Reviewing Texas Lending Options
Hunting for a bad credit loan in the Lone Star State is a delicate dance. It’s not merely a race to see who can drop cash into your account the fastest. While quick access to funds is a major plus, you must weigh that against the actual price of borrowing.
If a company hands out money like candy, you better look closer at the interest. A lender that rolls out the red carpet too quickly might be hiding astronomical rates. These costs can act like an anchor, dragging down your finances for a long, exhausting period.
We sat down with the fine print to dissect various lending structures. Our team measured the Annual Percentage Rate (APR) against how quickly money hits your bank account. We wanted to see if the speed of the transaction justified the total cost to your wallet.
After all, getting cash in a pinch is wonderful, but it shouldn’t feel like you’re selling your future. We looked for a sweet spot where rapid disbursement meets reasonable repayment terms. Balancing immediate relief with long-term financial health was our primary mission throughout this entire investigation.
Our deep dive centered on a handful of vital metrics. We scrutinized how simple the application process felt and how fast the funds arrived. We also looked at whether the repayment terms allowed for any breathing room when life gets unpredictable.
The scope of our research covered a diverse array of Texas municipalities. We specifically hunted for companies offering unique tools, such as credit builder products. Each provider was thoroughly vetted to confirm they truly assist individuals navigating the choppy waters of poor credit.
We gave extra weight to lenders that utilize “soft pulls” for their pre-qualification stages. This is a lifesaver for Texans who want to window shop without hurting their scores. When your credit is already on thin ice, every unnecessary inquiry can feel like a heavy blow.
Protecting your report from unnecessary damage is a cornerstone of financial stability. By prioritizing lenders that don’t trigger a hard inquiry during the initial phase, we help you maintain a steadier path toward recovery. It’s about making informed choices without the fear of further setbacks.
| Provider | Borrowing Limits | Payout Timing | Score Effect | Ideal Use |
|---|---|---|---|---|
| Texas Bay Credit Union | Up to $2,000 (Starter) | See site | See site | Building Credit |
| Solarity Credit Union | See site | See site | See site | Business & Personal |
| TexasLoansToday | $500 – $35,000 | 24 Hours | No Hard Pull | Fast Funding |
| Wisetack | See site | Under a minute | See site | Home Services |
Leading Texas Lending Options for 2026
1. Texas Bay Credit Union
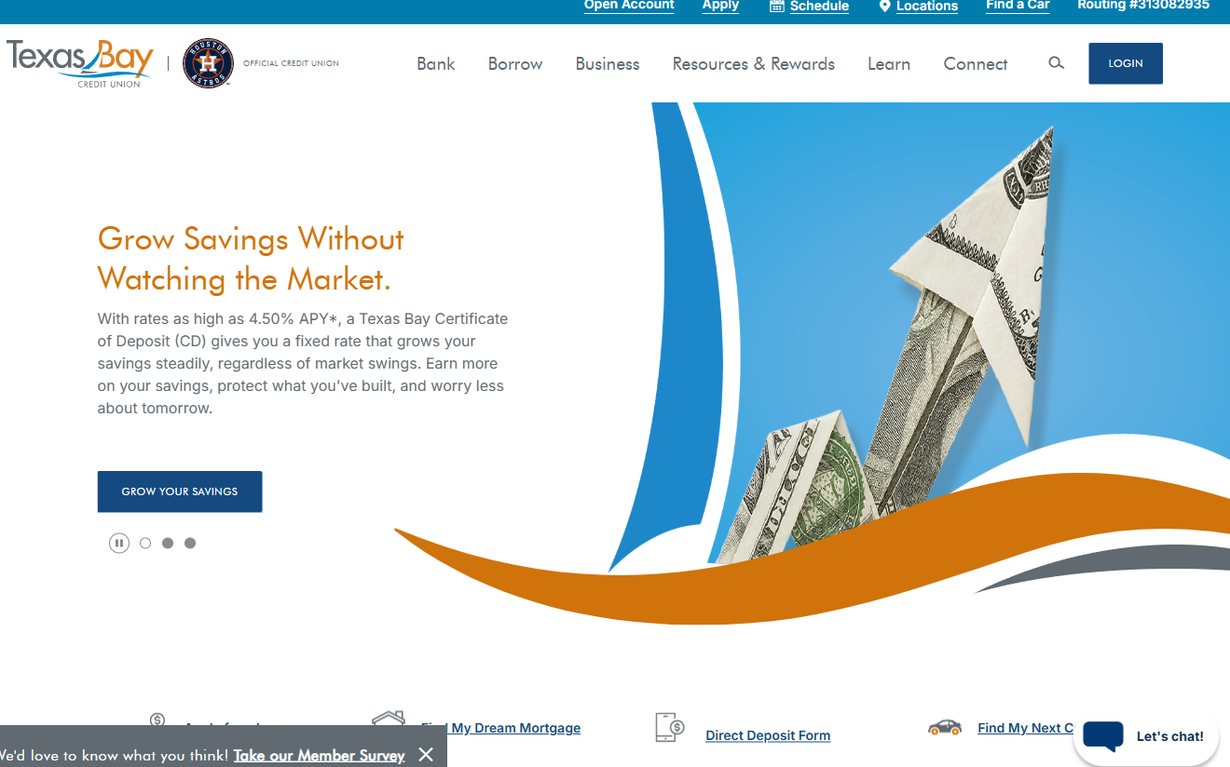
For individuals just beginning to navigate the financial landscape, Texas Bay Credit Union serves as a reliable anchor. They specialize in introductory loans tailored specifically for those with minimal or non-existent credit histories. By capping these amounts at $2,000, they provide a manageable stepping stone for anyone eager to prove their fiscal responsibility to future lenders.
Large, traditional banks often slam the door on applicants with thin credit files, but this institution looks deeper. They evaluate your overall financial stability rather than just a single number. It is a refreshing approach that acknowledges everyone has to start somewhere while offering the necessary tools to move upward.
Their offerings extend well beyond simple credit-building tools to include versatile auto financing. These programs are designed to keep you moving without the predatory interest rates often found at shady “buy here, pay here” dealerships. This flexibility ensures your monthly budget remains intact and your transportation stays reliable.
Pros:
- Specialized loans intended for credit construction.
- Adaptable financing for automobiles.
- The security of an established credit union.
Cons:
- Initial starter loans are restricted to $2,000.
2. Solarity Credit Union
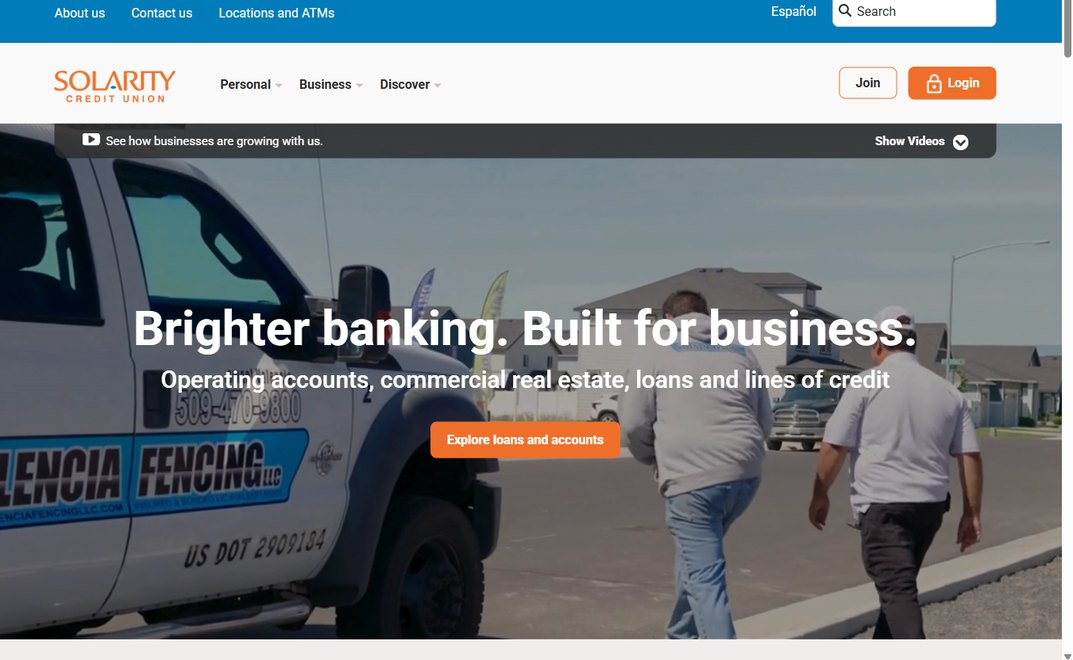
Solarity Credit Union brings a sense of clarity and simplicity to the banking world. Their reach is vast, serving a diverse crowd that includes individuals needing personal assistance and businesses seeking commercial real estate or lines of credit. They combine modern digital interfaces with a heavy emphasis on human guidance.
Think of them as the perfect middle ground between a sleek fintech app and a sturdy, traditional bank. For those managing both a household budget and a growing business, their comprehensive suite of services is hard to beat. They strive for a “brighter” banking experience by employing staff who actually listen.
Whether you are an entrepreneur in Austin looking to stock up on inventory or a San Antonio resident trying to consolidate high-interest debt, they act as your navigator. They do not just hand over a check; instead, they help you grasp the long-term consequences of your financial decisions.
Pros:
- A diverse array of personal and commercial products.
- Significant focus on professional support and advice.
- Contemporary digital banking technology.
Cons:
- Paperwork requirements may exceed those of online-only competitors.
3. TexasLoansToday
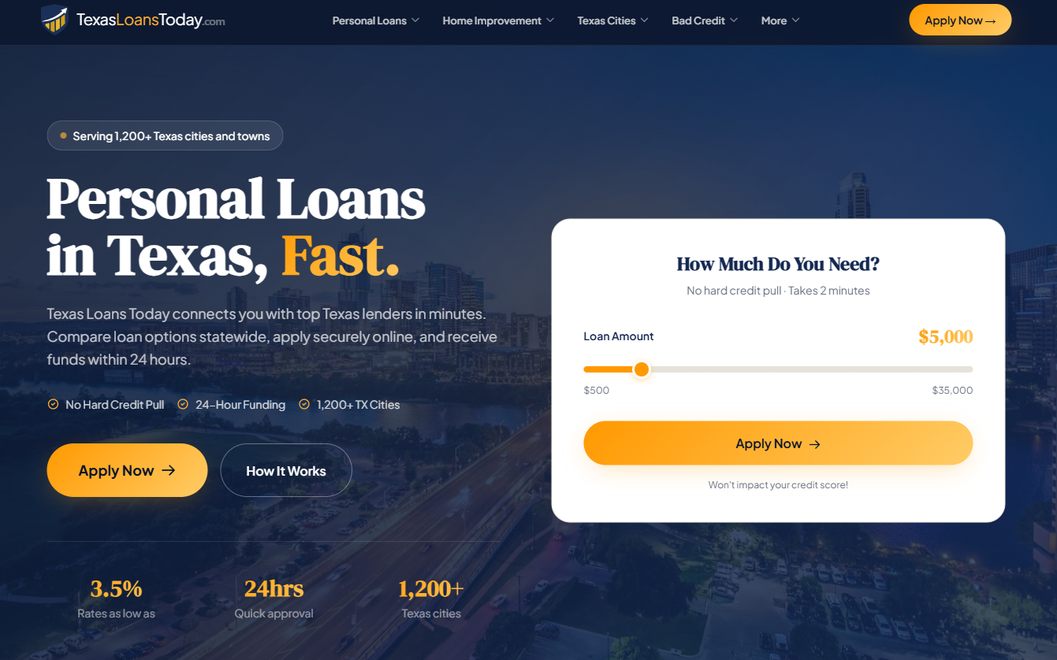
When the clock is ticking, TexasLoansToday is ready to jump into action. Operating as a true powerhouse across the Lone Star State, they serve over 1,200 different Texas towns and cities. Their standout feature is sheer velocity, with many applicants receiving a decision in under twenty-four hours.
In the middle of a sudden plumbing disaster or a car repair that keeps you from working, that speed is a lifeline. They are built for real-world emergencies where waiting weeks for a bank’s committee to meet is simply not an option. They bridge the gap between catastrophe and stability.
This lender is also a friend to those watching their credit scores closely. By offering a “no hard credit pull” option, you can scout your rates and eligibility without damaging your standing. This is vital for those rebuilding their reputation, as avoiding unnecessary hard inquiries helps keep your score intact.
Pros:
- Rapid funding, often within 24 hours.
- Initial rate checks do not require a hard credit pull.
- Massive coverage area across Texas.
Cons:
- Interest rates can be high for certain borrowers.
4. Wisetack
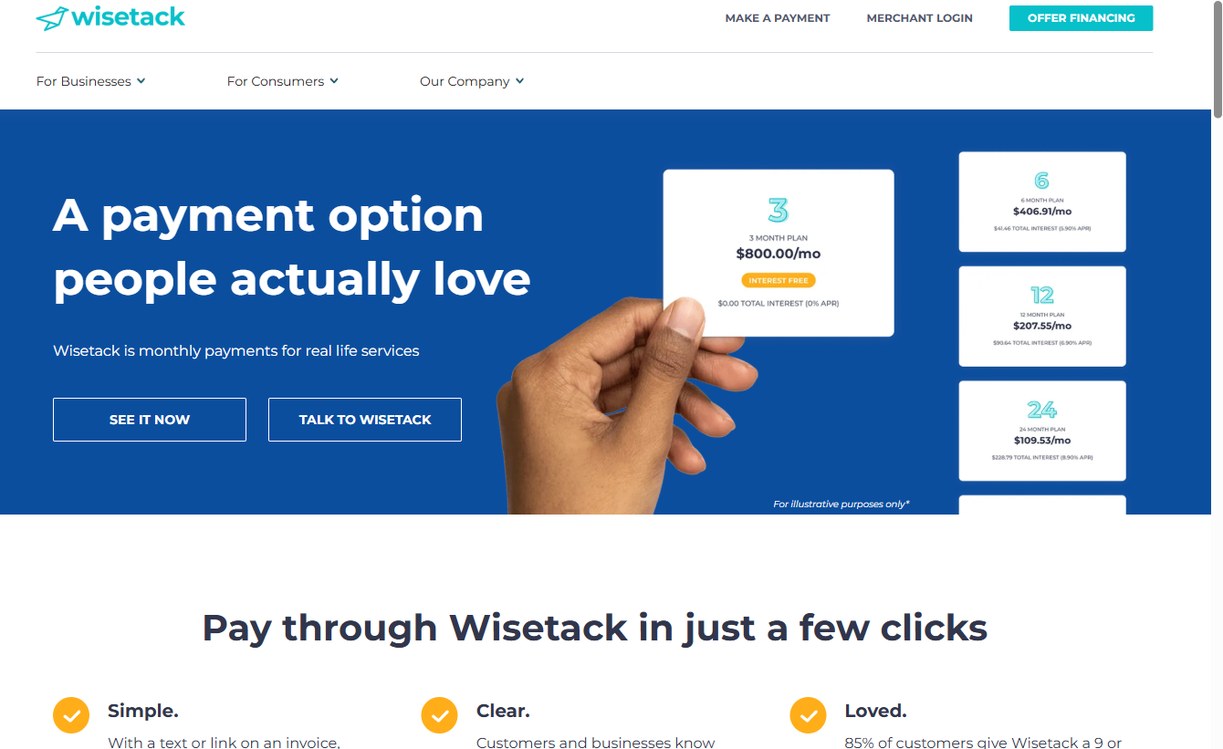
Wisetack functions quite differently from your standard bank, acting as a bridge between homeowners and professional service providers. If your roof is leaking or your HVAC system has quit, this is your primary resource. You can view your financing details in less than sixty seconds via a simple link or text.
This method completely bypasses the dread of filling out mountain-high stacks of paperwork at a physical branch. Transparency is the name of the game here. Both the homeowner and the contractor see the exact costs immediately, preventing that dreaded “sticker shock” when the job is finished.
The system operates as a closed loop, sending funds directly to the service professional to ensure the work is completed. This protects the consumer while providing a seamless, digital-first experience. It is a highly efficient way to handle specific home improvement costs without the usual headache.
Pros:
- Immediate access to financing options through text or links.
- Top-tier ratings for customer satisfaction.
- Easy integration with various home service businesses.
Cons:
- Only available for specific home-related service transactions.
Measuring the Real Financial Burden
Before putting pen to paper on a contract, you need to dissect the fine print like a surgeon. It is easy to get blinded by a small monthly installment, but relying on that single figure is like navigating a storm without a compass. A tiny monthly bill is often just a smokescreen for a much longer repayment period.
If you stretch your timeline too far, you might find yourself paying back double or even triple what you originally took out. It is a classic trap that can leave your bank account feeling light for years. You must look past the surface to see the actual damage to your budget.
To truly grasp the weight of your debt, you need to calculate the Total Cost of Loan. Following a structured approach ensures you aren’t caught off guard by hidden math. Here is a straightforward way to figure out exactly how much cash is actually leaving your pocket:
- Pinpoint the APR: Ignore the basic interest rate for a moment. Instead, focus on the Annual Percentage Rate, as this number incorporates all the extra fees into one percentage.
- Determine Total Interest: Take your monthly installment amount and multiply it by every month in your term. Once you have that sum, subtract your starting principal to find the interest cost.
- Include All Fees: Don’t forget to add any administrative costs, processing fees, or origination fees to your previous calculation. These small bites can add up to a massive meal.
- Execute a Comparison: Take this final, comprehensive figure and weigh it against competing offers. This tells you which lender is truly the most affordable over the long haul.
Consider a $2,000 loan with a 5% interest rate spanning 12 months. Now, compare that to a $2,000 loan with a 25% interest rate stretching across 36 months. Even if the second option feels easier on your weekly budget, it is a whole different beast entirely.
The latter scenario will drain thousands more from your savings through interest alone. What started as a quick fix for a car repair or a household emergency can quickly morph into a massive, long-term financial weight around your neck.
Smart Ways to Boost Your Score While Tackling Debt
Securing a loan to bridge a financial gap doesn’t have to be a life sentence of bad credit. If you play your cards right, this temporary lifeline can actually act as the spark that ignites a financial comeback. Think of it as using quick cash to extinguish a current fire while building a much sturdier house for the future.
The real trick lies in using that immediate liquidity to settle pressing matters while simultaneously cultivating habits that keep you away from predatory, high-interest lenders down the road. It is all about working smarter, not harder, with the money you have access to right now.
Consider the following tactical steps to ensure your borrowing experience leads to growth:
- Focus on Specialized Credit Building Tools: If you are truly aiming to repair your credit score, a dedicated credit builder product might be a much wiser path than a typical installment loan. For example, options like those from Texas Bay Credit Union are specifically engineered to show a history of on-time payments to the bureaus. These tools help your score grow without demanding a massive amount of cash upfront.
- Automate Your Payments: Missing a deadline is like throwing gasoline on a fire when you are trying to save your credit. A single payment that is 30 days overdue can send your score plummeting toward the floor. To stay safe, set up automatic withdrawals so that life’s many distractions don’t cause you to miss a single due date.
- Resist the Urge to “Stack” Debt: It might feel easy to grab several tiny loans to cover various bills, but this is a dangerous path toward a debt spiral. Instead of layering loans, try to find a single consolidation plan. Alternatively, tackle your most expensive debt first by utilizing the “Avalanche Method” to save on interest.
- Conduct Monthly Statement Audits: Do not sit around waiting for a collection agency to knock on your door. By scrutinizing your credit reports and bank statements every month, you can spot mistakes or fraudulent charges. Catching these errors early prevents them from snowballing into massive legal headaches or long-term financial disasters.
Navigating Your Financial Decisions Wisely
When Texans find themselves hunting for bad credit loans, the most common pitfall is jumping headfirst into the very first deal that lands in their inbox. It feels like a lifeline when you are desperate for immediate liquidity, but chasing the fastest check can lead to a crushing landslide of interest.
Before signing anything, you must demand a clear breakdown of the total amount you will eventually repay. This includes every hidden fee and the complete APR. If a lender tries to bury these vital numbers in the tiny, illegible text of an online form, run the other way.
Honesty is the best policy when it comes to your money. You want a partner who lays everything out on the table from day one. A transparent company is always a safer bet than a shady one that plays hide-and-seek with your actual cost of borrowing.
You should also weigh whether a standard personal loan actually fits your current situation. Sometimes, a generic installment loan is like using a sledgehammer to crack a nut. If your main objective is repairing a bruised credit score, you might need a different tool entirely.
A credit builder loan can be a lifesaver for those trying to climb out of a financial hole. These specialized products are often far more effective for long-term score improvement than a basic loan. It is about playing the long game rather than just surviving the night.
Stop for a second, look at the math, and pick a route that fosters progress. You want to build a staircase, not a treadmill that keeps you running in place. The way you handle these high-pressure moments will ultimately dictate your financial health throughout the Lone Star State.