Best Places to Secure a 500 Credit Score Personal Loan Fast
Last updated: 2026-10-16
Navigating a financial downturn when your credit score sits at 500 can feel like wandering through a dense mist without any direction. Many folks believe a low score acts as a permanent barrier to borrowing. In reality, the modern lending landscape suggests it is merely a bump in the road.
Success usually boils down to locating a creditor willing to look beyond a solitary digit. You shouldn’t let a subpar rating dictate your entire economic future. Finding the right partner can provide much-needed breathing room during tough times.
Generally, a 500 rating is classified as “very poor.” You will likely face swift rejections from major mortgage providers or premium credit card companies. It is not a dead end, however. You just need to pivot your search away from mainstream banks toward specialty lenders.
When hunting for capital, simply grabbing the first check isn’t wise. You must hunt for terms that won’t drag you under later. Excessive interest can transform a minor loan into a crushing weight of debt. Consider how a $5,000 loan at 36% APR compares to a $5,000 loan at 25% APR over a 36-month window.
The difference is staggering. That extra 11% can add thousands to your total interest costs over those three years. That is money that could have boosted your savings instead of feeding a bank’s bottom line. Our list highlights lenders that focus on speed and inclusivity for people rebuilding their lives.
- Avant
- OneMain Financial
- FastLendGo
- Reprise
- United Finance
- OppLoans
Our Methodology for Selecting Lenders
Our team centered the entire review process on finding real solutions for individuals sitting in the “poor” credit bracket. We know that a 500 score can feel like a brick wall when trying to walk through the doors of a traditional bank. Consequently, we focused our search on specialists who actually welcome those with fragile credit histories.
We placed a premium on firms that provide a straightforward application journey. Our goal was to highlight lenders who won’t slap you with a penalty to your FICO score just for peeking at their offers. It is about making sure the door is open before you even try to step inside.
A “soft pull” is essentially your best friend in this scenario. It permits you to scout potential interest rates and loan terms without triggering a “hard pull” on your credit report. When your score is already teetering on the edge, you shouldn’t have to worry about making things worse just by exploring your options.
Speed and clarity acted as the next two pillars of our investigation. Life doesn’t wait for you to fix your finances; it hits you with a sudden car repair or a medical bill when you least expect it. In these frantic moments, you aren’t just looking for a loan; you are looking for a lifeline.
Lenders that prioritize rapid decision-making or even same-day transfers earned a top spot in our list. However, we weren’t willing to sacrifice sanity for speed. Every company had to maintain fair and reasonable repayment structures to qualify for our recommendation.
We relied heavily on a specific metric we call “time-to-cash.” This measures the literal clock starting from the second you click “submit” until that money lands in your bank account. If a lender takes too long to move, they simply didn’t make the cut for our high-speed ranking.
The Financial Reality of Subprime Borrowing
Before you sign on the dotted line with any provider on this list, you must face the cold, hard numbers. If your credit score sits at 500, you are essentially walking into a storm of high interest. Lenders see a significant risk in your profile, which means they will demand a higher premium to protect themselves. This risk premium manifests as a much steeper APR.
Don’t let the interest rate fool you; it is only half the story. You really need to keep a sharp eye on the Annual Percentage Rate, or APR. This figure is the real truth-teller because it bundles the basic interest with every hidden fee and origination charge. It is the most honest way to see the actual damage to your wallet over time.
Let’s look at how these numbers play out in the real world. Imagine you are standing at a crossroads with a $3,000 debt. The difference between a decent profile and a struggling one isn’t just a few extra dollars each month; it is a massive gap in total wealth. The table below breaks down how your credit standing changes the math of your repayment plan.
| Principal Amount | Annual Rate (APR) | Duration | Every Month | Cumulative Interest Cost”>Cumulative Interest Cost |
|---|---|---|---|---|
| $3,000 | 15% (Good Credit) | 24 Months | $145.46 | $491.04 |
| $3,000 | 30% (Fair Credit) | 24 Months | $171.18 | $1,108.32 |
| $3,000 | 45% (Poor Credit) | 24 Months | $199.63 | $1,791.12 |
Take a close look at those final columns. It is quite staggering to realize that merely doubling your interest rate can result in triple the total expense by the end of the term. It’s a heavy price to pay for immediate liquidity, which is why you must be incredibly discerning about where you turn for help.
Your primary objective shouldn’t be finding the easiest path to cash, but rather finding a partner in your financial recovery. You want a lender that acts as a ladder to help you climb out of a low score. Avoid the sharks that only aim to bleed your monthly income through excessive interest, and instead, look for a way to rebuild.
Evaluating Premier Borrowing Providers
Finding the right lender often feels like hunting for a needle in a haystack, especially when your score is hovering around the 500 mark. You want a partner that won’t turn their back on you just because your financial history is a bit bumpy. It’s about finding that sweet spot between quick cash and reasonable terms.
Some companies focus on speed, acting like a lightning bolt to solve your immediate cash crunch. Others prioritize flexibility, offering longer repayment windows so you can breathe a little easier each month. It is crucial to weigh these different approaches before signing any paperwork that binds your budget.
I remember a friend who rushed into a high-interest deal just because the money arrived instantly. While the speed was great, the long-term cost was a bitter pill to swallow. Take your time to scan the landscape, comparing how each provider stacks up against your specific needs and constraints.
The table below breaks down how several prominent players compare. While some specialize in helping those with less-than-perfect credit histories, others might offer more significant loan totals. Use this snapshot to guide your research as you hunt for the best possible deal for your wallet.
| Company | Principal Range | Duration of Loan | Processing Time | Eligibility Criteria |
|---|---|---|---|---|
| Avant | Visit website | Visit website | Visit website | Suited for Low Credit |
| OneMain Financial | $1,500 – $30,000 | 24 – 60 months | In as little as 1 hour | Visit website |
| FastLendGo | Visit website | Visit website | Visit website | Poor or No Credit History |
| Reprise | Visit website | Visit website | Visit website | Visit website |
| United Finance | Max $20,000 | Visit website | Visit website | Visit website |
| OppLoans | Visit website | Visit website | Funds sent same-day | FICO score is unaffected |
Leading Lending Institutions Evaluated
1. Avant
Think of Avant as a financial companion walking beside you on your journey toward stability. They don’t just provide loans; they offer a suite of instruments, such as installment loans and credit cards, tailored to your current life circumstances. Their mission is to empower people to navigate unexpected hurdles or untangle messy debt cycles.
Many lenders out there are like quick fixes that leave you worse off later, but Avant plays the long game. They strive to foster lasting connections with their customers rather than just facilitating a one-off transaction. For anyone needing more than a bandage for their finances, their diverse ecosystem provides real utility.
If your current headache is a mountain of high-interest credit card debt, an installment loan from Avant might be your lifeline. By merging those scattered payments into a single monthly obligation, you could find much-needed breathing room, assuming the interest rates align with your goals.
Pros:- Provides various instruments including credit cards and debt consolidation tools.
- Focuses on assisting clients in reaching long-term financial objectives.
- Adapts solutions to suit different stages of life.
- Specific terms and interest rates aren’t publicly disclosed for every credit bracket.
2. OneMain Financial
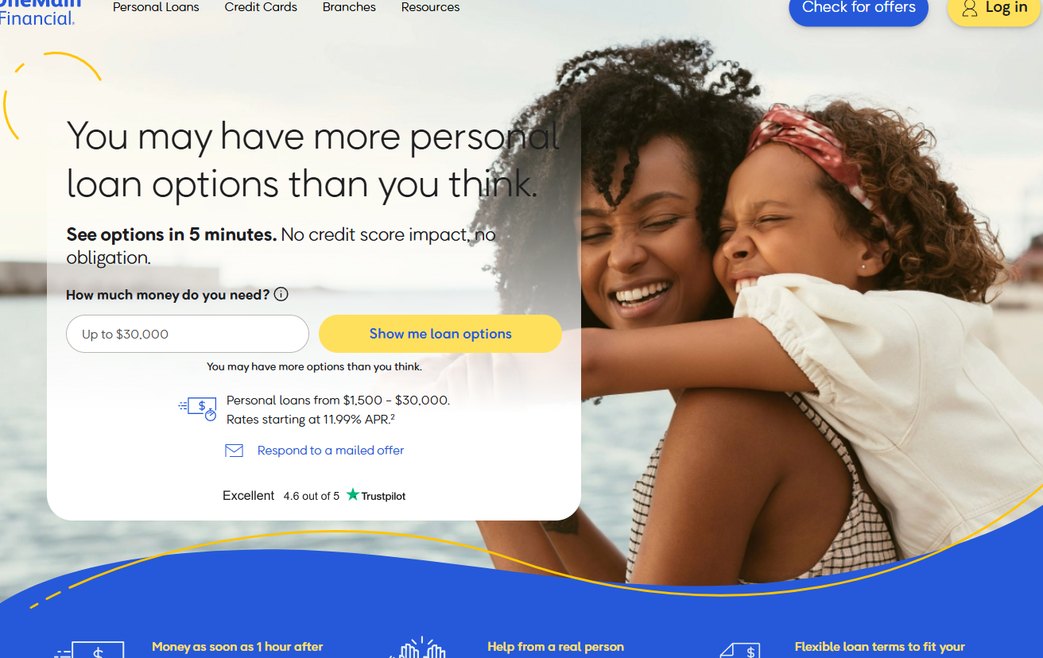
Sometimes, you just need to look a human being in the eye to get things done. OneMain Financial offers exactly that, boasting a massive physical footprint of over 1,300 local branches. This setup is a goldmine for those with non-traditional income streams, like freelancers or self-employed workers, who might get lost in the gears of a digital algorithm.
Walking into a branch allows you to sit down and tell your story to a loan officer directly. This personal touch can often pave the way for better lending terms than a cold, automated system ever could. They offer a wide range of personal loans from $1,500 all the way up to $30,000.
Whether you are tackling a major home renovation or consolidating old debts, they have the muscle to help. If you are in a rush, you could potentially have your funds in hand just one hour after signing your paperwork, provided you handle the in-person verification.
Pros:- Extensive network of physical locations for face-to-face assistance.
- Rapid disbursement, potentially within a single hour of signing.
- Loan amounts reaching as high as $30,000.
- Certain options may necessitate a branch visit or a response to a mailed offer.
3. FastLendGo
FastLendGo serves as a digital shortcut, helping you bypass the exhaustion of calling bank after bank. By acting as a high-speed aggregator, the FastLendGo platform pulls multiple local loan offers into one easy-to-read view. They cover the whole spectrum, from a tiny $500 boost for a quick repair to larger sums for roofing or vehicle needs.
The interface is built for the modern, mobile-first world, making it a breeze to apply while you are on the move. They are particularly helpful for those facing credit hurdles, offering paths for individuals with no credit history or bad credit scores. It is the ideal way to find a “lender near me” without the headache of traditional waiting periods.
Ultimately, this tool puts the power back in your hands. By presenting a side-by-side comparison, you can see exactly which provider offers the most competitive rate for your specific profile, giving you a clear view of the entire landscape at once.
Pros:- Accommodates various needs like dental or auto expenses.
- Accessible to many credit profiles, including those with no history.
- Streamlined comparison of various local providers.
- Functions as a comparison engine, so actual terms vary by the specific lender matched.
4. Reprise
Reprise enters the chat by using sophisticated AI to handle data and demonstrations. While they aren’t a standard consumer lender, they represent how cutting-edge technology is reshaping professional services. They stand as a testament to the sheer power of modern data management in an increasingly automated world.
For the professional who lives and breathes tech, they offer advanced features like full clones and data injection. They are much more of a specialized tool for high-level business management than a place to get a personal loan. It is a fascinating outlier in a list otherwise dedicated to consumer finance.
Pros:- State-of-the-art AI capabilities for creating demos.
- Expertise in high-level data injection.
- Highly efficient for managing professional presentations.
- Does not function as a traditional consumer lender for personal debt.
5. United Finance
United Finance is a true veteran of the industry, having navigated the financial waters since 1922. They focus on making personal and auto loans as straightforward and accessible as possible. Their long history provides a sense of stability that is often missing in the modern world of volatile fintech startups.
Because they have seen it all, they possess a deep-seated understanding of risk and market cycles. They offer personal loans with ceilings of $20,000. Additionally, residents of Oregon can take advantage of their high-yield certificates, showing a diverse range of services from lending to savings.
If you prefer a traditional institution with deep roots, this is a very solid choice. Their dual focus on both credit and investment products makes them a versatile player for those looking for established financial reliability.
Pros:- Decades of proven stability and a very long history.
- Provides both auto and personal loan options.
- Offers investment products like high-yield certificates.
- Specific products like investment certificates may be limited by geography.
6. OppLoans
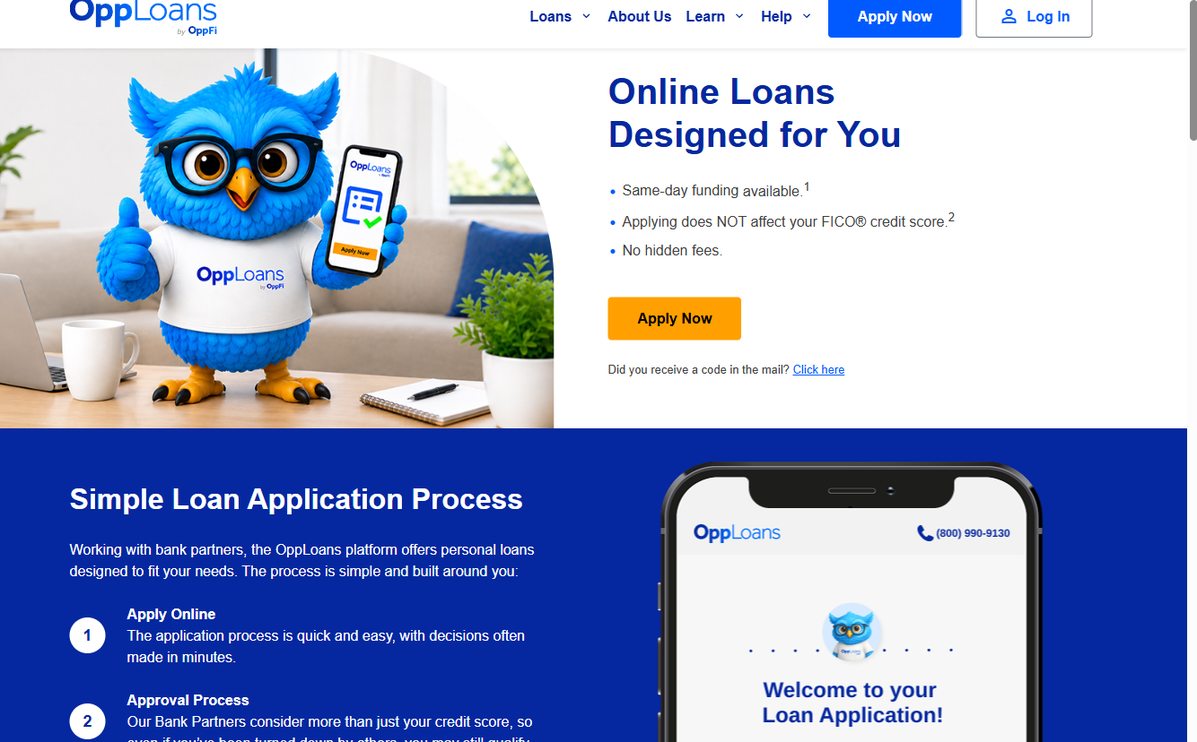
When speed is the name of the game, OppLoans is a serious contender. A major benefit for those working to improve a 500 credit score is that applying for their loans won’t ding your FICO rating. In the delicate process of rebuilding credit, avoiding that “hard inquiry” penalty is like finding money on the sidewalk.
They partner with various banks to deliver lightning-fast decisions, often in just a few minutes. For those facing a sudden emergency, same-day funding is available to keep your head above water. Their process is stripped of unnecessary fluff, focusing instead on getting you an answer quickly.
This makes them an excellent choice for those urgent situations where a single day’s delay could lead to a late fee or a utility shut-off. It is a solution built for the “right now” moments of life.
Pros:- Applying for a loan does not impact your FICO score.
- Same-day funding is available for those who are approved.
- Decisions are delivered with extreme speed.
- Best suited for urgent, short-term needs rather than long-term financial planning.
Hunting for the Right Financing
Staring down a 500 credit score can feel like looking into a dark abyss. You might feel an intense urge to jump at the very first deal that comes your way. Yet, chasing the path of least resistance often leads straight into a financial trap.
The easiest loan to secure isn’t necessarily the friendliest one for your wallet. It is absolutely critical to scrutinize the microscopic details regarding how much this debt will truly cost you. A quick cash injection that seems simple to obtain can quickly transform into a crushing weight if the interest rates are predatory.
Keep a sharp eye out for those sneaky “origination fees.” These are essentially upfront deductions stripped from your total loan amount before you even touch the cash. It is a classic bait-and-switch that can leave you feeling light in the pocket.
Picture this: you secure a $1,000 loan, but the lender clips $100 off the top for fees. You only walk away with $900 in hand, yet you are still on the hook for interest on the full $1,000. This hidden expense is a sting that lingers long after the money is spent.
A frequent blunder is failing to distinguish between a soft inquiry and a hard credit pull. You want to be a smart shopper, not a victim of your own curiosity. Always hunt for lenders that permit you to verify your eligibility through a soft pull.
This specific approach allows you to scout various rates and compare different options without further bruising your credit score. Use this window of opportunity to collect a variety of quotes. Comparing the APRs is the only way to ensure you aren’t paying a premium for the mere privilege of borrowing.
Another trap involves overlooking how the repayment timeline impacts your long-term health. It is a delicate balancing act. A short term keeps your monthly obligations high, whereas a long term balloons the total interest you eventually pay back.
If you opt for a 60-month term just to keep monthly payments low, the math might surprise you. You could end up paying back nearly twice what you originally borrowed. It is a high price to pay for temporary relief.
Select a term that fits comfortably within your existing monthly budget. Make sure you leave a little breathing room to build a savings cushion and eventually boost that credit score. Your goal is to use this loan as a bridge over a gap, not to build a permanent cage of debt.