Top-Rated Online Bad Credit Loans Maryland: Instant Approval Options
Last updated: 2026-10-17
Managing your money in Maryland often feels like wandering through a heavy mist without a map. When a sudden engine failure, an unplanned doctor’s visit, or a leaking roof hits you all at once, the anxiety can become overwhelming.
Living in the busy Baltimore-Washington corridor is expensive, and many people find themselves in a tight spot. Perhaps a period without work or a health crisis caused your credit score to drop, even though you are a reliable person.
Chasing down a loan involves much more than a frantic tap on a smartphone. You have to balance how fast you get the cash against what it will eventually cost you in interest.
You also need to distinguish between secured loans and unsecured debt. It is vital to find companies that look at your whole life story rather than just a single, three-digit number on a screen.
Whether you live in the bustling streets of Baltimore or the quiet suburbs of Montgomery County, knowing how local lending works is key. This knowledge helps keep your long-term finances from sinking.
We have curated this list to showcase lenders specifically for residents of the Old Line State. These options are perfect for anyone needing to patch a hole in their monthly budget quickly.
- FastLendGo
- MaxCash
- LendingPoint
- OppLoans
- SECU
Our Selection Process for Maryland Credit Options
To curate this list, we didn’t just glance at the surface. We performed an extensive investigation into what various companies actually offer to people living in Maryland. Our main goal was to find lenders that truly cater to individuals struggling with low or subprime credit scores. We wanted to ensure these services are practical for people facing urgent financial pressure.
Finding quick cash is one thing, but avoiding a downward spiral is quite another. We steered clear of providers that lure users into predatory cycles with sneaky costs or astronomical interest rates. It’s about finding a lifeline, not a heavy anchor that drags you deeper into debt. We vetted every option to ensure they act as a genuine bridge to financial stability.
Each potential candidate underwent a rigorous inspection against several vital benchmarks:
- Available Funding Ranges: We sought out a wide spectrum of borrowing options. This includes everything from a quick $300 for a sudden electric bill to larger $15,000 sums meant for consolidating various debts.
- Processing Velocity: When an emergency strikes, waiting a week is simply not an option. Our team checked if lenders deliver instant verdicts, same-day payouts, or if you’ll be stuck waiting several days.
- Clarity and Terms: Honesty is paramount. We checked that their online disclosures are upfront, ensuring the fine print matches the digital promises before you ever sign a contract.
- Impact on Your Score: We gave preference to companies using “soft pull” methods for preliminary quotes. This allows you to compare rates freely without causing further damage to your FICO score.
| Company | Borrowing Limits | Payout Timing | Eligibility Criteria |
|---|---|---|---|
| FastLendGo | $500 – $5,000+ | Fast access | Bad/Fair/Good Credit |
| MaxCash | $250 – $10,000+ | Minutes | Bad Credit Loans |
| LendingPoint | $1,000 – $36,500 | Fast decision | See site |
| OppLoans | See site | Same-day funding available | Does not affect FICO score |
| SECU | $300 – $30,000 | See site | Unsecured Signature Loans |
Deciphering the Differences: Secured and Unsecured Borrowing
Before you start browsing the lenders listed below, you must grasp exactly how your chosen debt functions. Within the state of Maryland, most financial institutions provide two main frameworks: secured or unsecured. Making the wrong choice is like walking into a storm without a raincoat; it can turn a small debt into a massive loss of your personal belongings.
Understanding these nuances is the first step toward financial stability. You shouldn’t jump into a contract without knowing what you are putting on the line. Every borrower needs to weigh their options carefully to avoid a trap that could haunt them for years to come.
Think of it as choosing a path through a forest. One path might be easier to walk, but the other might have a much steeper cliff at the end. You need to know which one you are stepping onto before you take that first, critical stride.
Unsecured Debt Options
When you opt for an unsecured loan, you aren’t putting any physical property up as a guarantee. If you apply for an unsecured personal loan—similar to what you might find through LendingPoint or SECU—the company is essentially betting on your word alone. They trust that you will fulfill your promise to repay the borrowed funds.
Since there is no house or car for the bank to grab if things go south, they tend to be quite picky. They will likely perform a deep dive into your bank statements and your current salary to ensure you are reliable. It is a bit like a handshake agreement, but with much more paperwork and scrutiny.
For many Marylandans, this is the “gold standard” for safe borrowing. If your paycheck is consistent but your credit score is currently in the basement, these loans allow you to access cash without the fear of losing your car or your home. It keeps your assets safe even when your credit is struggling.
Secured Debt Options
A secured loan operates on a much different principle, relying on what is known as collateral. To put it simply, you are pledging something you own to back the money you borrow. If you decide to pursue a title loan, for instance—a type of financing discussed in the MaxCash part of this guide—your car becomes the safety net for the lender.
This setup works as a double-edged sword. If you find yourself unable to meet your monthly obligations, the lender holds the legal hammer to take your vehicle to recover their money. It is a heavy price to pay for immediate liquidity, and you must be absolutely certain of your ability to pay it back.
Because the lender has a fallback plan, these loans are often much easier to secure when your credit score is in the gutter. However, the personal stakes are incredibly high. If your financial situation takes a turn for the worse, the very thing you use for transport could be gone before you can blink.
Premier Maryland Financing Solutions for Credit Challenges
1. FastLendGo
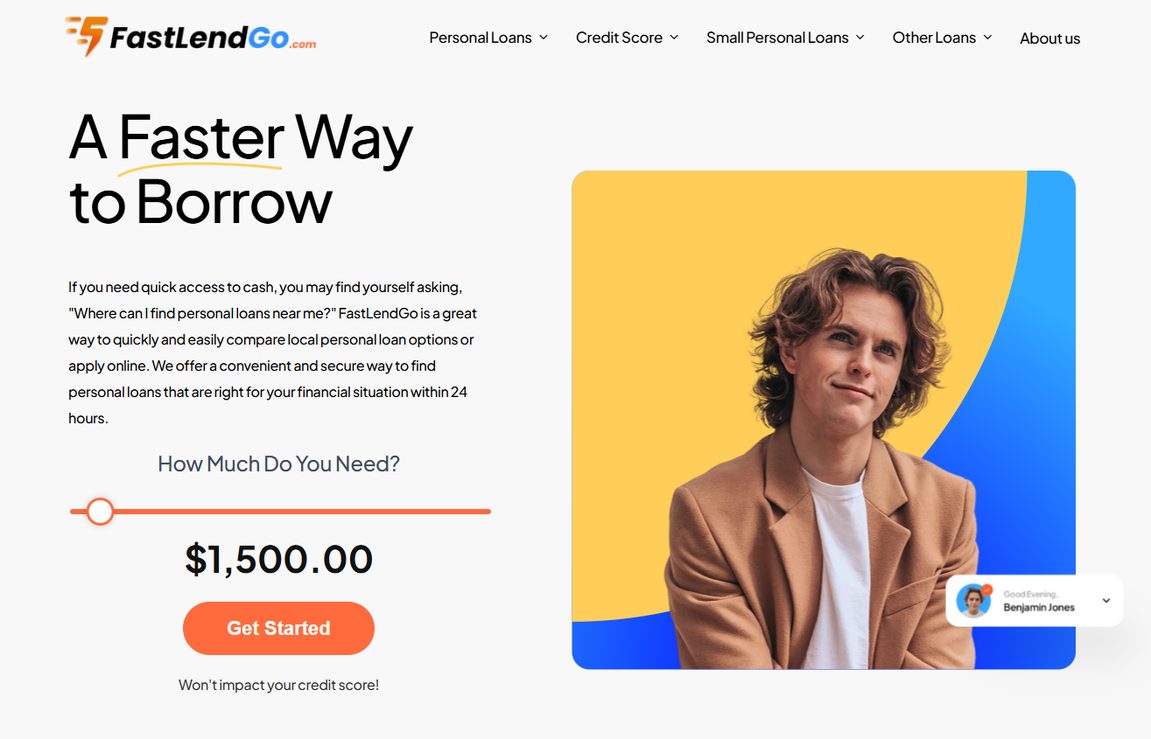
Think of FastLendGo as a digital compass for anyone navigating the tricky waters of local borrowing. It serves as a vital connection point, helping you weigh different regional personal loan opportunities against one another in a hurry. Sometimes, life throws a curveball, like a sudden dental bill or a car that refuses to start.
When those unexpected expenses strike, you don’t have the luxury of waiting for the next paycheck to arrive. This platform is built to cut through the red tape that typically makes big banks feel like a fortress. It prioritizes a smooth, rapid experience for borrowers who are essentially racing against the clock. (fastlendgo.com)
Whether you need a small $500 boost or a more substantial $5,000 personal loan, their range is quite versatile. They don’t turn their noses up at different credit backgrounds, making them a go-to for Marylanders in tight spots. By acting as a gateway to numerous providers, they often find a match that a standard bank might simply ignore.
Advantages:
- Provides funds for various needs, including dental and auto repairs.
- Accommodates everything from poor credit to excellent credit scores.
- Simplifies the process of comparing local lending options.
Drawbacks:
- Exact interest percentages are not listed in the summary.
2. MaxCash
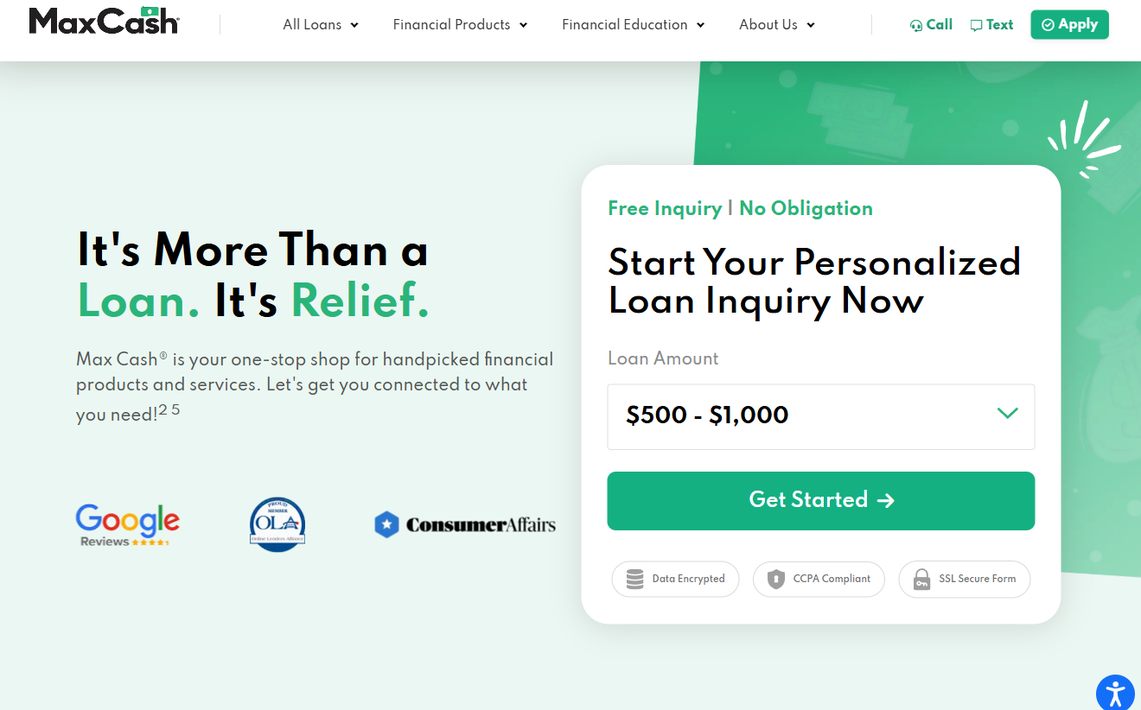
MaxCash acts less like a cold institution and more like a lifeline when things get tough. For people living in Maryland facing urgent crises—perhaps a looming utility shut-off or a broken appliance—this service steps up. It allows you to secure title loans or installment loans with incredible speed, often within just a few minutes.
This is high-octane financial support, specifically designed to plug holes in your cash flow when you need it most. The variety in their loan amounts is a major selling point, starting as low as $250 and climbing past the $10,000 mark. It truly functions as a comprehensive toolkit for your most pressing financial needs.
If your goal is to find a quick cash advance to bridge the gap until your next payday, you’ll find this is a top-tier option. It is perfect for those who demand immediate liquidity. Why wait days for a bank transfer when you could have the funds almost instantly?
Advantages:
- Processing happens at lightning speed, sometimes in minutes.
- Offers significant maximum limits for title-based loans.
- Provides a diverse selection of loan products.
Drawbacks:
- Title loans require you to use your vehicle as security.
3. LendingPoint
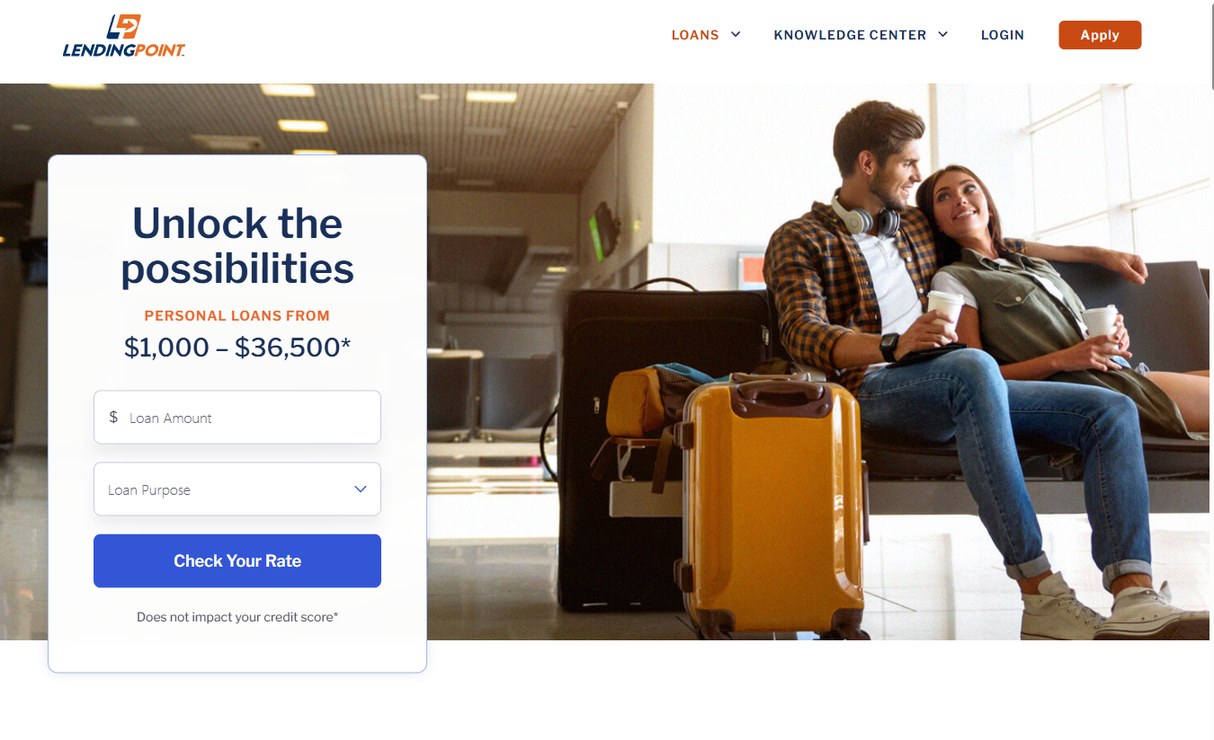
LendingPoint is geared toward those looking to spread their wings with larger capital injections. With the ability to borrow up to $36,500, it is a heavyweight option for major undertakings. This might include large-scale home renovations or perhaps the heavy lifting required for debt consolidation.
If you find yourself drowning in high-interest credit card debt that nibbles away at your monthly budget, a larger loan here could be your escape hatch. It serves as a strategic method for restructuring your finances and regaining control of your long-term stability.
The digital experience is remarkably streamlined, allowing you to peek at your potential rates without any damage to your credit score. This “soft pull” feature is a total lifesaver for savvy shoppers. It lets you hunt for the best deal without making your credit history look like a crime scene.
Advantages:
- Provides a high ceiling for substantial financing needs.
- Rate checking won’t harm your credit score.
- Offers a wide array of specific loan purposes.
Drawbacks:
- Might demand a better credit standing than niche bad credit lenders.
4. OppLoans
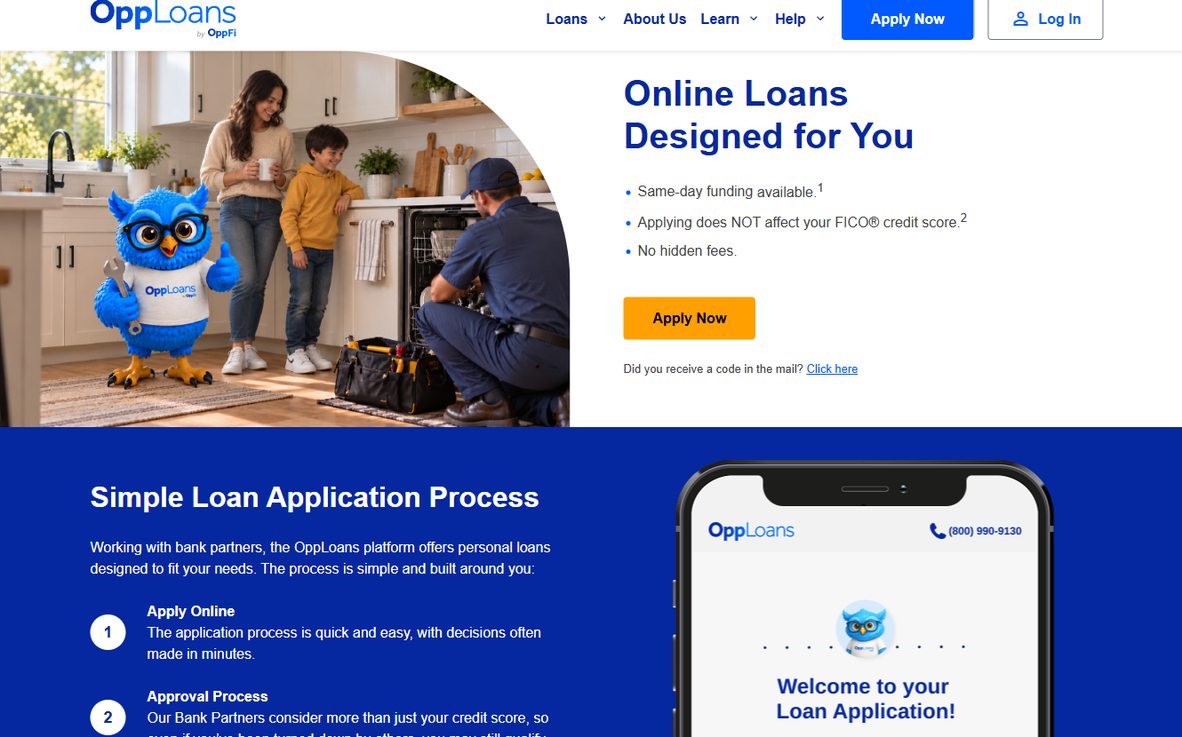
OppLoans operates on the philosophy that a single number shouldn’t define your financial worth. By teaming up with various banking partners, they offer personal loans tailored to unique life circumstances. This is especially helpful if a recent dip in your score has caused other lenders to slam the door on you.
They provide a much-needed safety net for those who feel ignored by the rigid, automated robots that run the big banks. If you are staring down a crisis—like a furnace dying in the middle of a freezing Maryland winter—time is of the essence. Their ability to offer same-day funding can be an absolute game-changer in such moments.
The application itself is stripped of unnecessary complexity to ensure you aren’t bogged down by paperwork. It is designed for efficiency and speed, getting you moving toward a solution without a mountain of documentation.
Advantages:
- Approved applicants can access funds the very same day.
- Applying does not impact your FICO score.
- Maintains transparency with no hidden fees in their ads.
Drawbacks:
- Approval decisions vary and aren’t solely tied to credit.
5. SECU
As the largest state-chartered credit union in Maryland, SECU offers a much more traditional and community-centered banking feel. Their unsecured signature loans are a fantastic way to build a lasting relationship with a financial institution. Because they are member-owned, you get a sense of alignment that big national banks simply can’t replicate.
You can access loans ranging from $300 all the way up to $30,000 without worrying about pesky application or prepayment penalties. This level of freedom is refreshing. If a work bonus or a tax refund comes your way, you can wipe out that debt early without being hit with extra interest fees.
It is a breath of fresh air compared to the predatory tactics and “early repayment” traps often used by high-interest lenders. For those looking for stability and fairness, this community-focused model is a solid choice for long-term growth.
Advantages:
- No penalties for paying your loan off early or applying.
- Provides high limits for unsecured loan products.
- Maintains a deep, reliable presence throughout Maryland.
Drawbacks:
- You may need to meet specific membership criteria.
Evaluating Your Financing Options
Selecting a creditor is far from a solo endeavor that happens in isolation. You shouldn’t dive headfirst into a contract without scrutinizing the microscopic details hidden in the fine print. While the rush of an immediate green light feels great, sprinting toward a quick fix can leave you stranded on a costly island if you skip your homework.
Don’t fall into the trap of focusing exclusively on what you owe each month. A tiny installment amount frequently signals an extended repayment period, which ultimately forces you to cough up much higher interest totals by the time you’re finished. It’s a classic case of “pay more later.”
Consider a scenario involving a $2,000 loan. Opting for a $100 monthly bill over 36 months ends up being much pricier than paying $200 every month for a single year. Always tally the entire amount you will have handed over by the end—the cumulative sum of every installment—prior to signing on the dotted line.
It is also easy to misjudge how a company’s character aligns with your personal circumstances. Suppose you are facing an eviction and require cash immediately to stay housed. In that high-stakes moment, a credit union might move at a snail’s pace, even if they offer more favorable interest rates than other options.
On the flip side, if your goal involves taking a $20,000 lump sum to roll your various debts into one manageable package, a tiny payday lender will be useless. They simply lack the capital for such a large task and might actually deepen your financial hole instead of helping you climb out of it.
Finally, never fall for the siren song of “guaranteed approval,” as that phrase is a complete fantasy in the financial industry. Because of consumer protection regulations, real lenders are required to verify that you actually have the means to pay them back. Any outfit promising they never say no is likely a scammer or a shark.
Avoid those wolves and stick with established, trustworthy entities. These professional outfits will clearly explain their requirements and prioritize your fiscal health while you weather the storm of economic hardship.